
Subscribe for daily free DeFi news covering launches, tradable catalysts, and actionable farming opportunities.
Today’s News Headlines:
Uniswap UNI becomes the first DeFi token with CME futures
Frax launches on-chain FX on Base, six stablecoins
Lighter launches binary options on Lighter Core
Echo Protocol winds down, withdrawals and repayments open
Papertrade says PAPER will not be transferable
Strategy buys 267 BTC, raises buyback to $3B
Silhouette launches RFQ system for Hyperliquid perps
Key Takeaways:
Crypto held up better in a risk-off environment
Bitcoin fell 2% while NQ fell 5.5% amidst a higher-than-expected inflation report. Funding rose to 5.59% from 2.63%, above the 4.79% cost to borrow stablecoins. Stablecoin supply fell $1.5B and spot ETFs lost about $550M in a second week of outflows, with the Nasdaq down about 4% and ETH/BTC below its 20-week average.
BSC added $1.5B of weekly DEX volume (+29.5%), the most of any chain.
A PancakeSwap proposal to give liquidity providers 88% of swap fees and cut CAKE emissions by 69% passed the same week. Ethereum’s 17% volume drop and Arbitrum’s 122% fee jump, each traced to a single day.
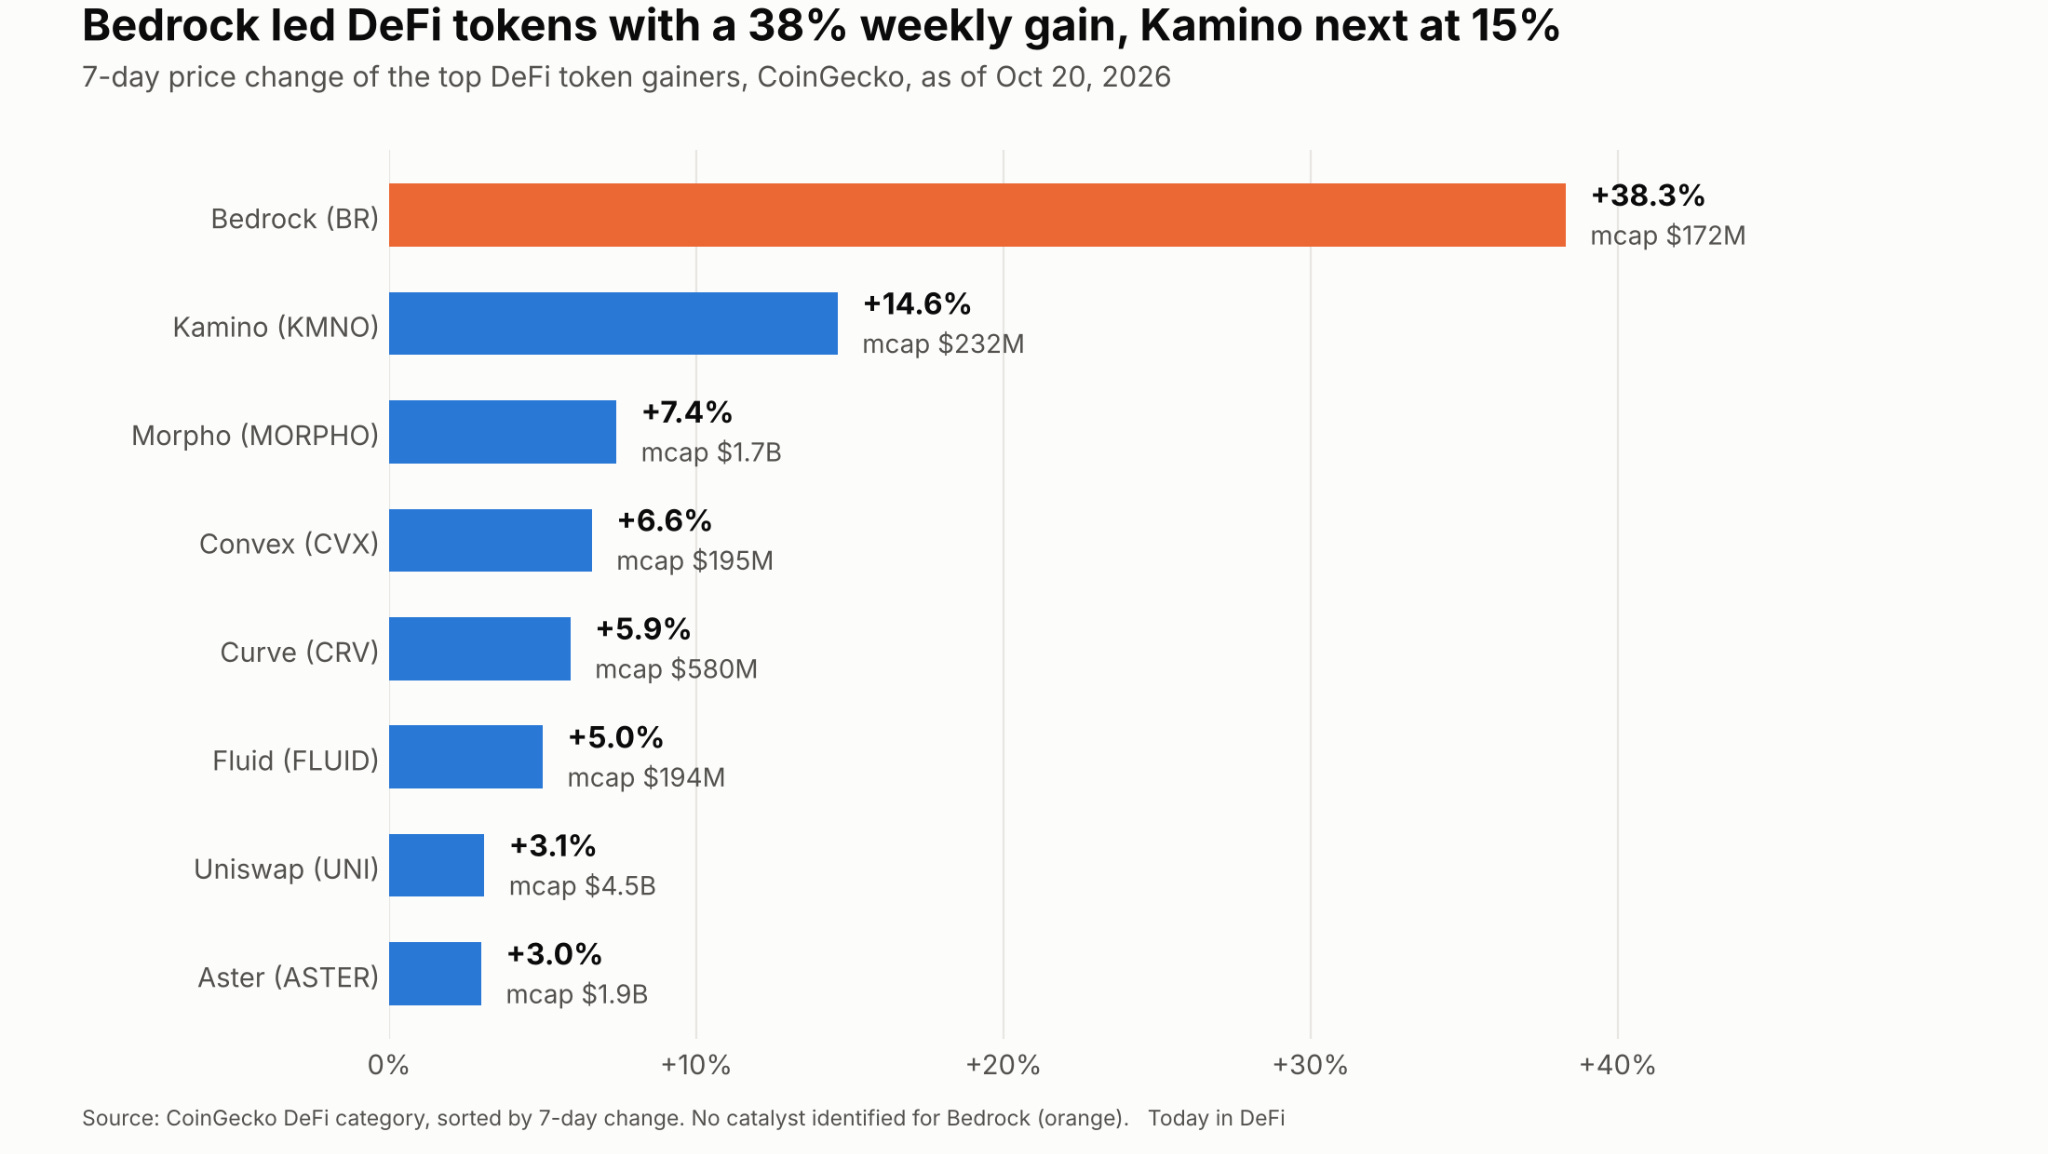
Kamino rose 15% in a week of product news, while Aster’s buyback barely moved its token.
Kamino Fixed Rates passed $55M in active loans, and tokenized-equity supply passed $50M. Aster says 99% of daily fees now go to buybacks, plus an extra $100K a day, yet the token is up only 3% on a $1.9B market cap.

Your Rate Doesn’t Move Unless You Move It
Aave and Morpho set your borrow rate based on utilization —it can spike overnight. Liquity V2 lets you set your own fixed rate, with up to 91% LTV and up to 11x multiplier on ETH exposure.
<Open a position now on DeFi Saver> | Today in DeFi is supported by Liquity
Macro brief: stocks fell, bonds sold off, Bitcoin lost less

The Nasdaq fell about 5% and the S&P 500 about 2%, the worst week since June. Hot CPI (3.7% against 3.6% expected) and PPI, Brent oil near $110, and AI-debt worries did the damage.
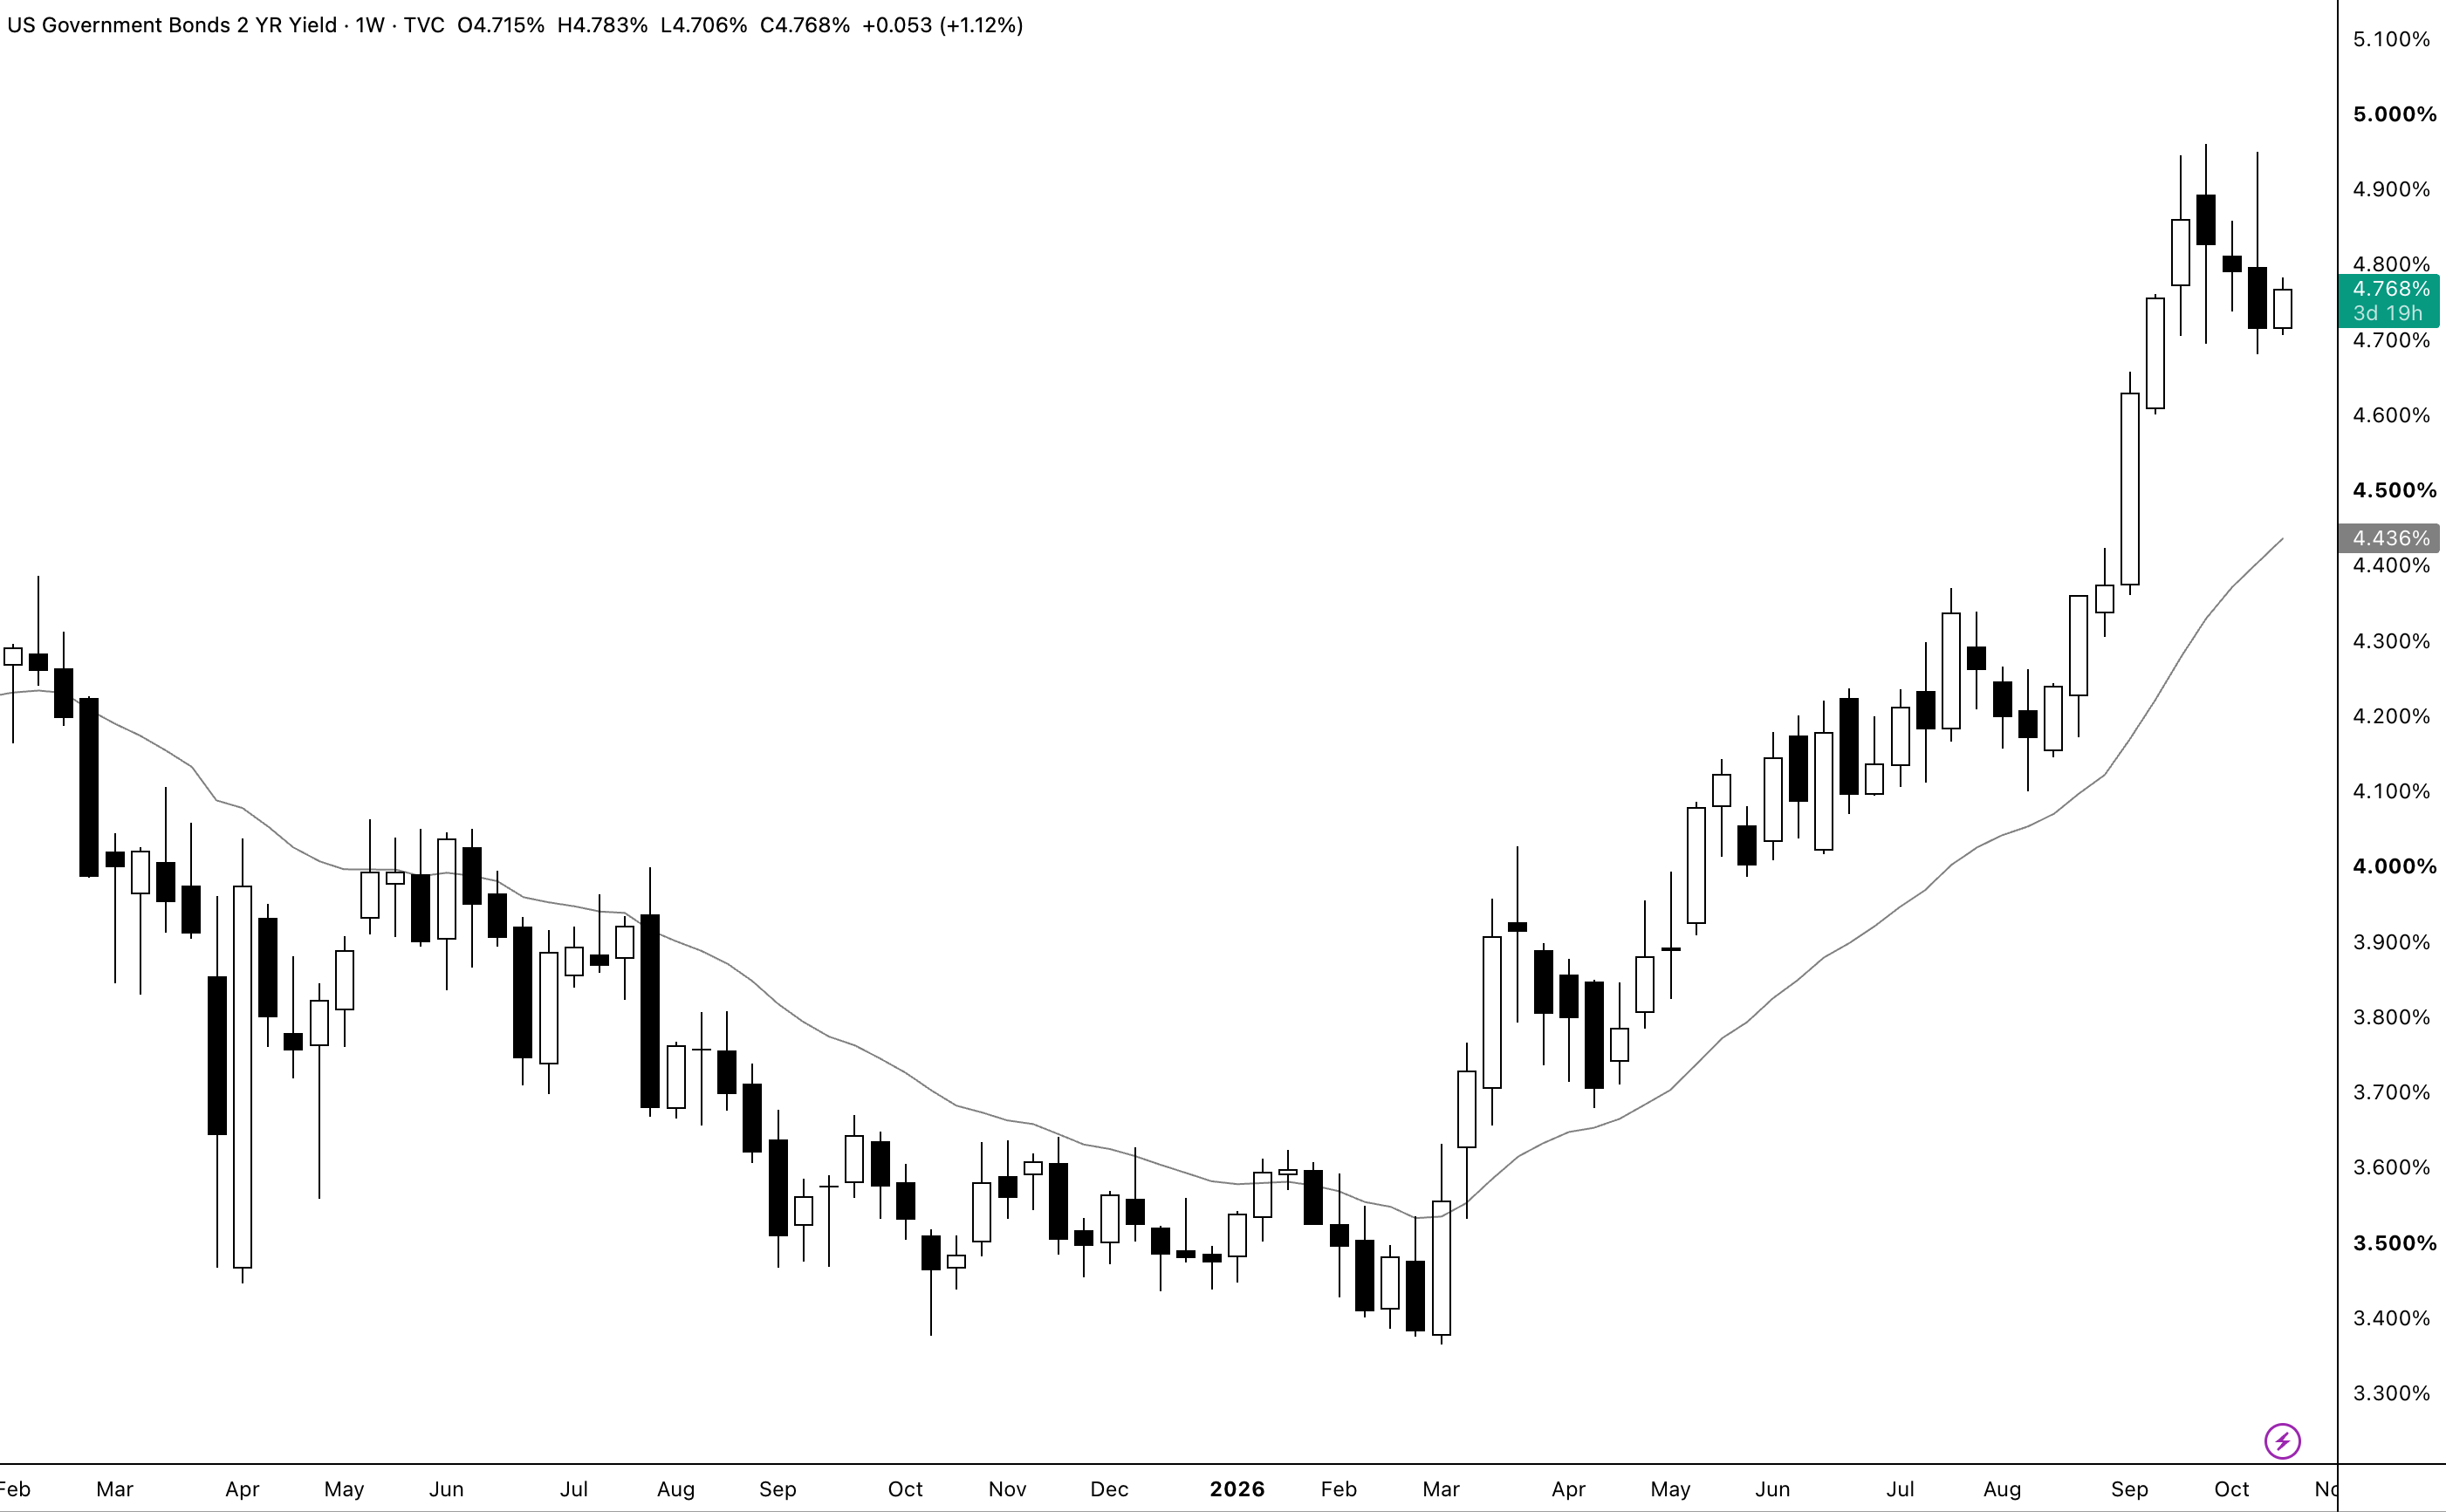
The 2-year yield, a read on Fed expectations, spiked to about 4.95% on CPI day and closed near 4.72% (down 7 bps), still above its 20-week average of 4.43%. The dollar index closed near 101.8, also above its 20-week average of 100.48.
Fed Chair Warsh gave no rate guidance on Oct 16. October hike odds fell from about 60% after CPI to 16-20%, while December hike odds sit near 89%. The next decision is Oct 28.
1B. Crypto Capital On-Ramp
Total stablecoin supply 7d change (level + WoW)
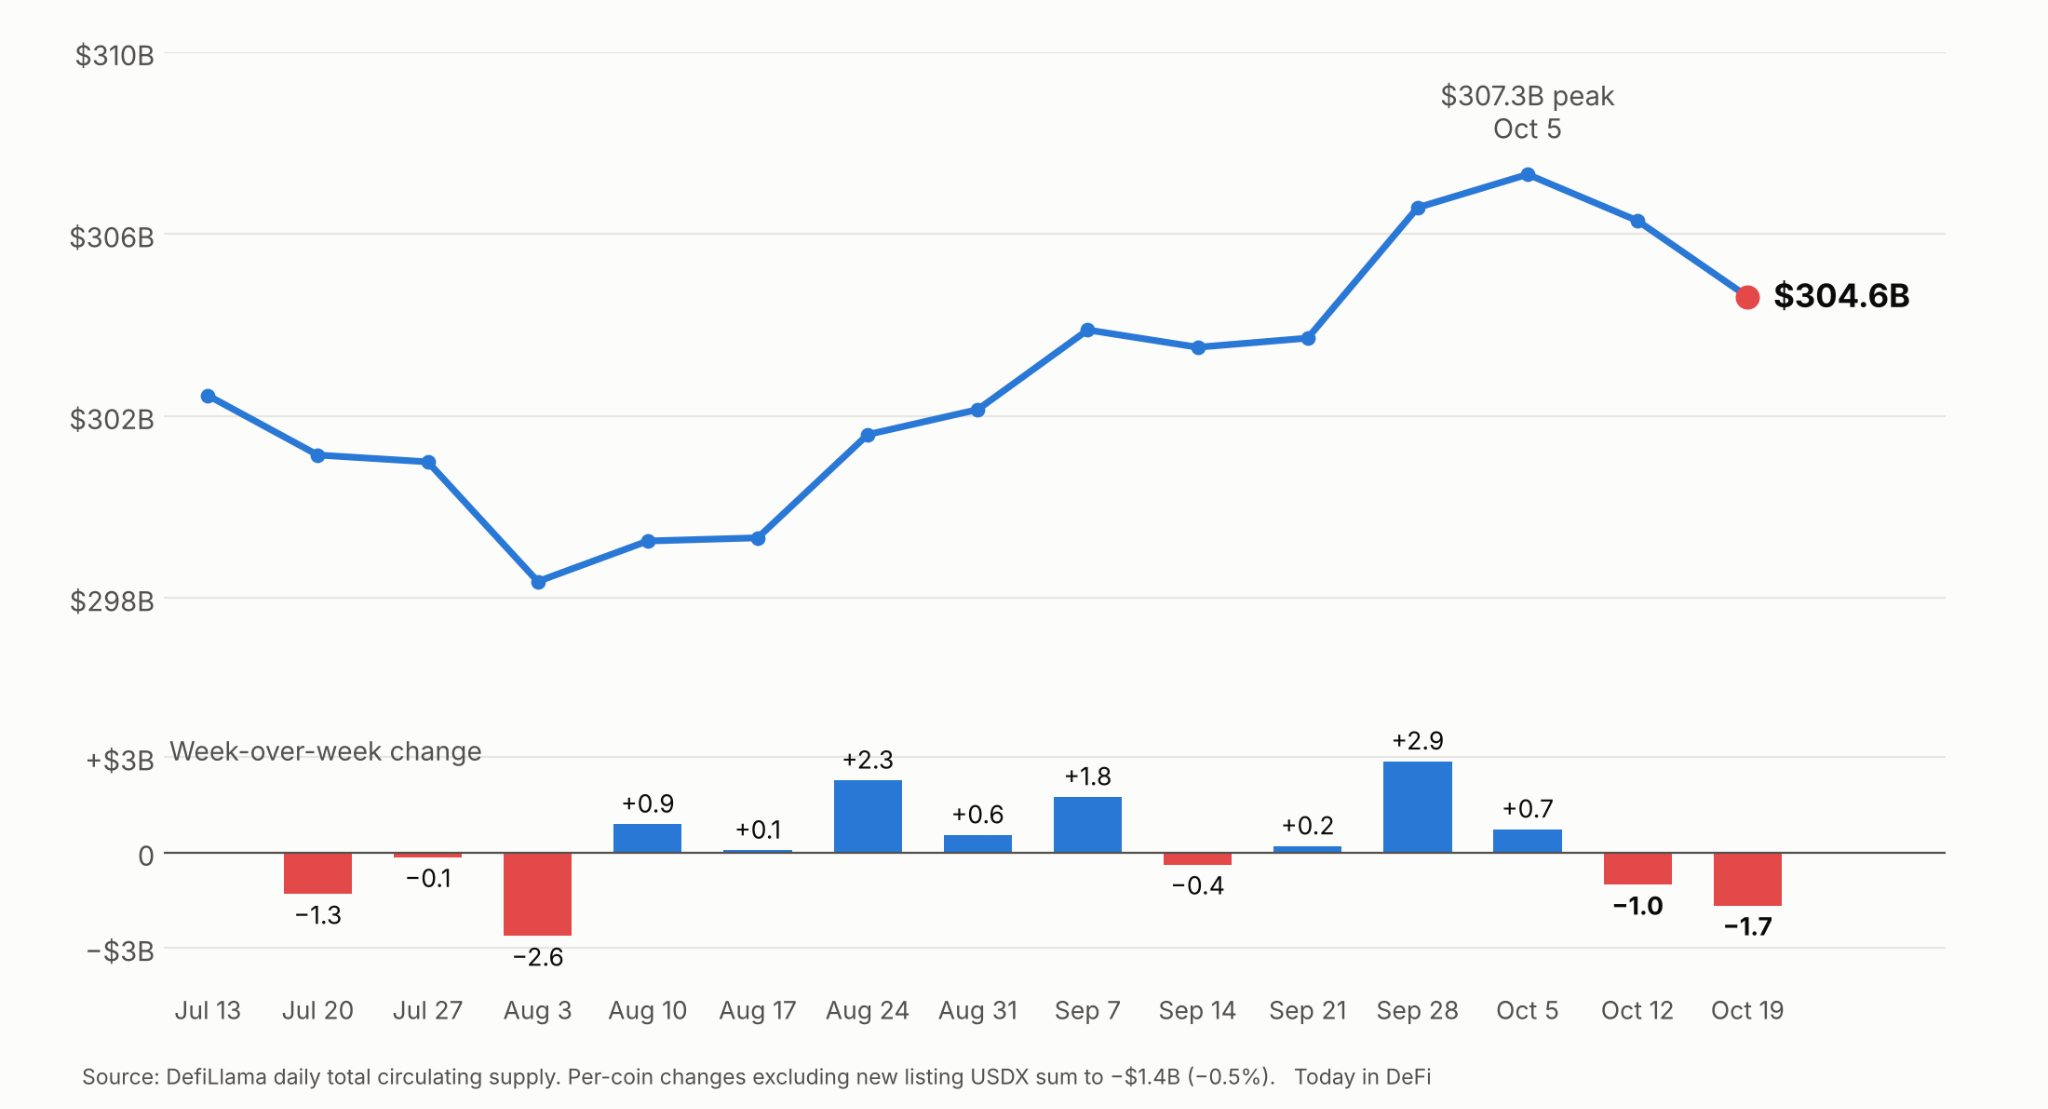
Stablecoin supply fell about $1.7B (−0.5%) to roughly $304B, marking the second consecutive week of declines.
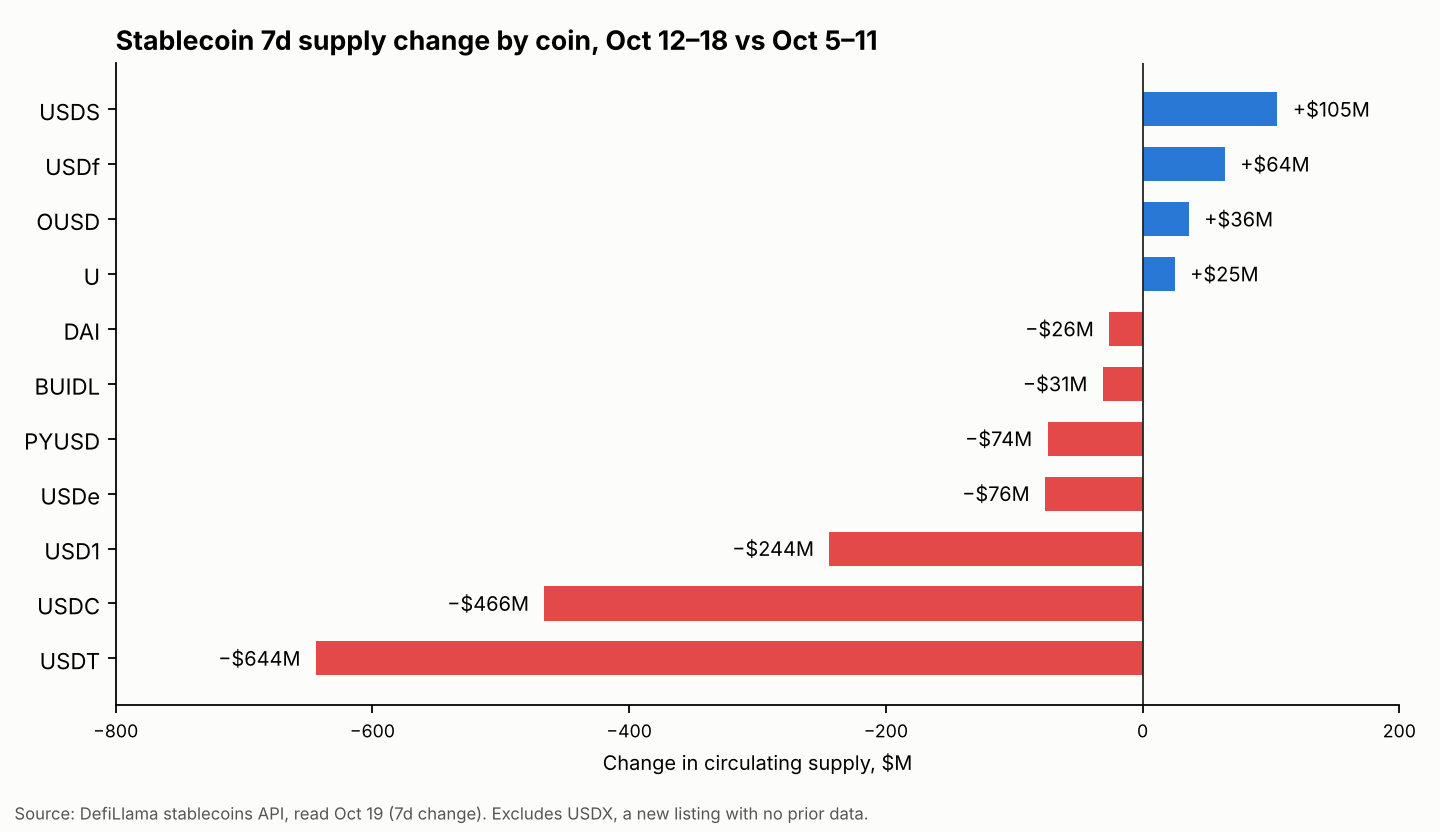
USDT lost $644M (- 0.35%), and USDC lost $466M (- 0.64%), the clearest sign of less fresh trading cash. Meanwhile, Sky’s USDS grew $105M (+1.5%), continuing its traction after raising sUSDS yields to 3.8% from 3.6%. Last week’s stance clearly signals de-risking, as trading capital shrank and yield-bearing stables like USDS and USDf gained traction.
BTC and ETH Exchange Flows

Exchange reserves edged up, which adds sell-side supply: bitcoin on exchanges rose about 7K BTC to 2.686M, and ether about 22K ETH to 14.928M.
ETF flows:

US spot ETFs lost money for a second week. Bitcoin funds had net outflows of $228M (Oct 5-9: $679M) and Ether funds lost $320M (Oct 5-9: $542M). CPI day, Oct 14, was the worst for both: Bitcoin lost $261M and Ether lost $ 130 M. Bitcoin funds took in money only on Oct 13 (+$176M) and Oct 15 (+$5M). Outflows are smaller than last week’s, but they have not stopped. (Farside BTC, Farside ETH)
1C. Week-Ahead Catalysts
Tue Oct 20: The SEC’s comment period on its proposed “Regulation Crypto Assets” framework ends, which does not make its fundraising exemptions effective. A final decision on Zcash’s NU7 activation is expected (target Nov 5).
Wed Oct 21: Solana targets its Alpenglow consensus upgrade (finality from about 12.8 seconds to 150 milliseconds). Fhenix targets its mainnet launch. Tesla reports, so any change to its Bitcoin holdings could show up.
Wed–Thu Oct 21–22: Bitwise’s liquidated Dogecoin ETF (BWOW) sets its net asset value, then pays remaining investors in cash.
Thu Oct 22: Aerodrome and Velodrome target merging into one “Aero” network across seven chains. AERO converts 1:1 and VELO at about 0.044 AERO.
Fri Oct 23: REX-Osprey targets an effective date for its SEI staking ETF and 24 other crypto ETFs.
Upcoming promising launch: Kinetiq’s Elysium Layer 2 launch on Nov 9

Find and execute the 15%+ stablecoin yields in minutes
Save time without checking every protocol manually. DeFi Saver’s Discover page surfaces rates across Aave, Morpho, Spark, and more, lets you simulate leverage before committing, and handles the full loop in one click. Stop leaving yield on the table.
<Discover Yields on DeFi Saver> | Today in DeFi is Supported by DeFi Saver
Onchain Risk Regime
Aave / Sphere Rates
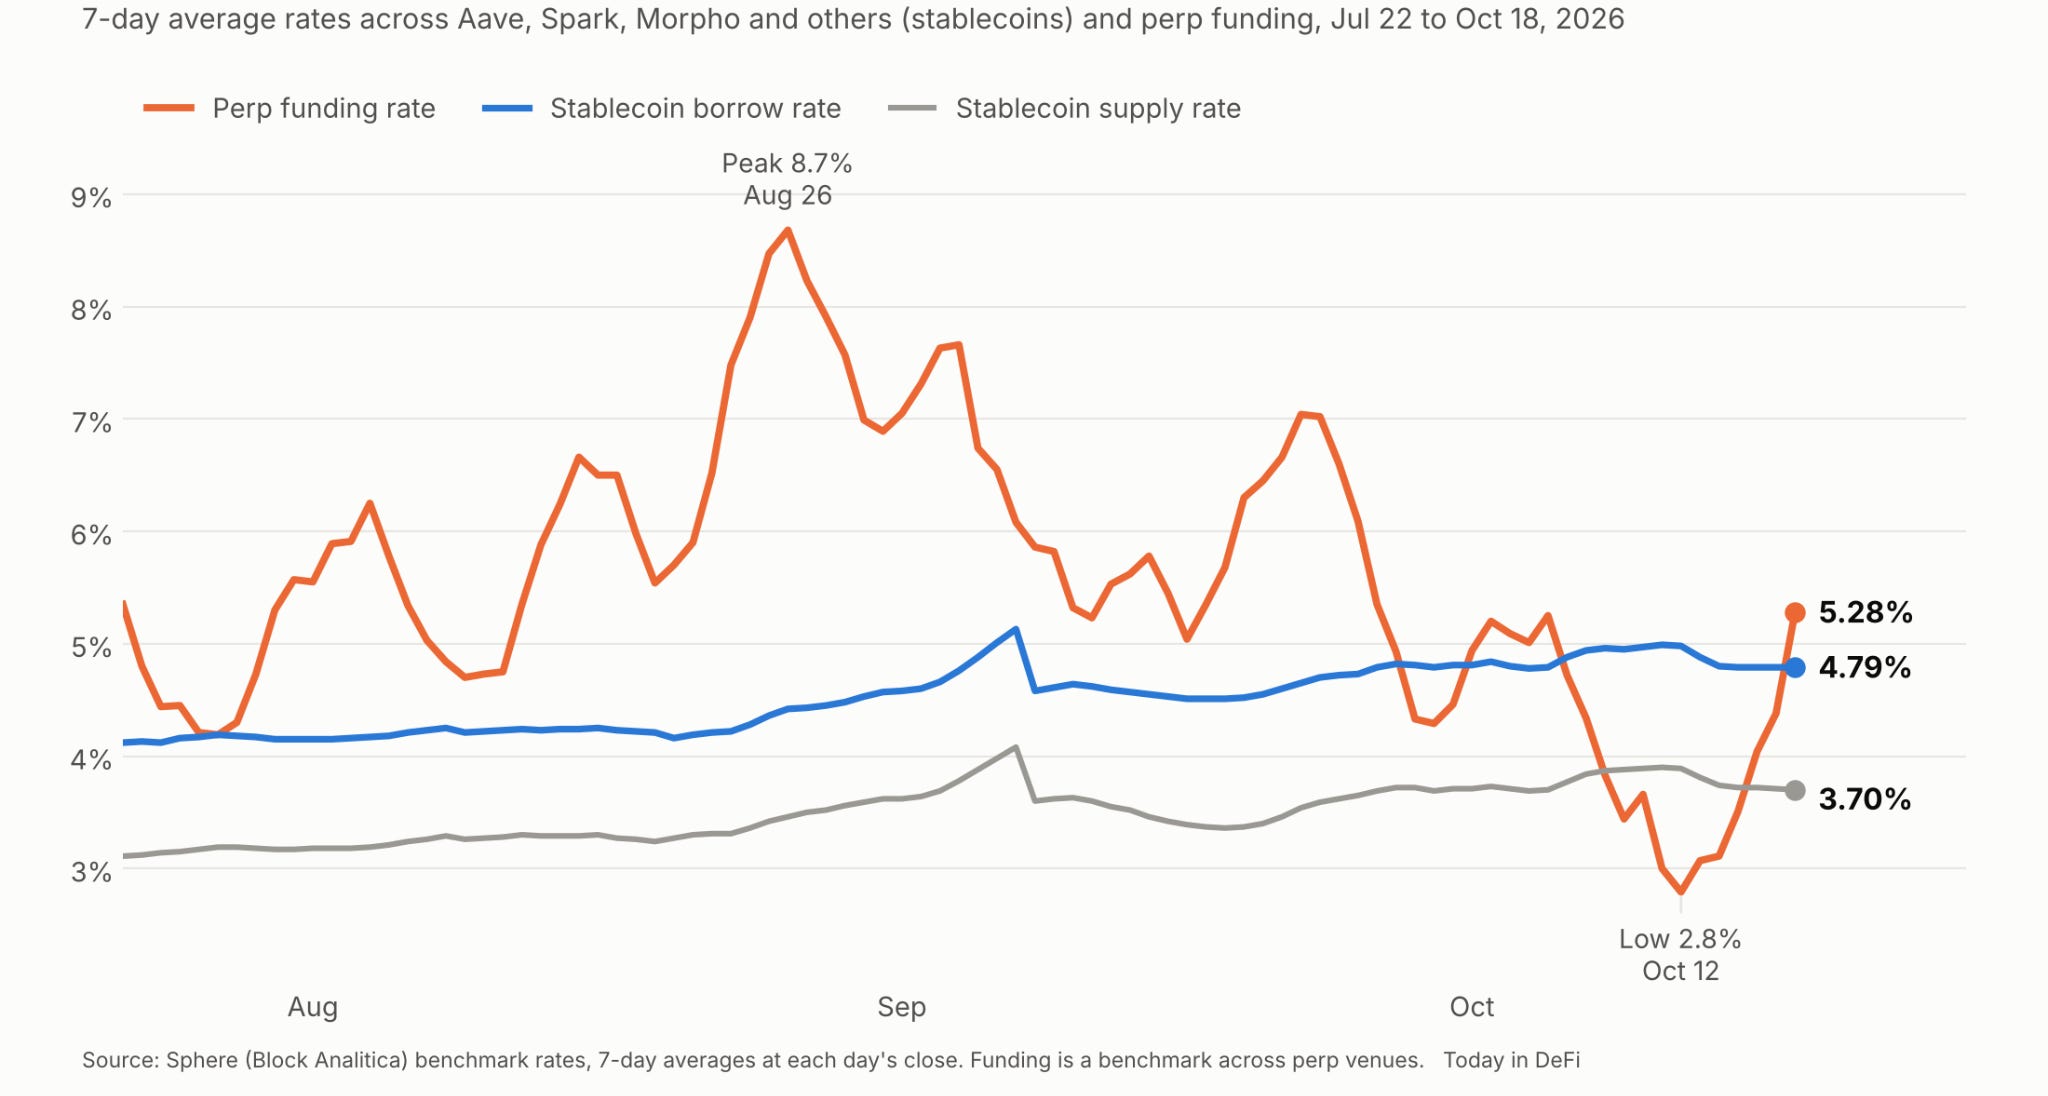
Across Aave, Spark, Morpho, and others, the average cost to borrow stablecoins eased to 4.79% (5.01% last week), and suppliers earned 3.70% (vs 3.93% last week). Cheaper borrowing suggests demand for on-chain leverage is cooling. (Sphere)
Perpetual futures say the opposite. The funding rate, the fee longs pay to hold a leveraged position, jumped to 5.59% from 2.63%. It now sits above the borrowing cost, so traders are paying more to stay long even as prices fall. That is a crowded trade, and crowded longs are where sharp drops start.
ETHBTC vs 20W MA
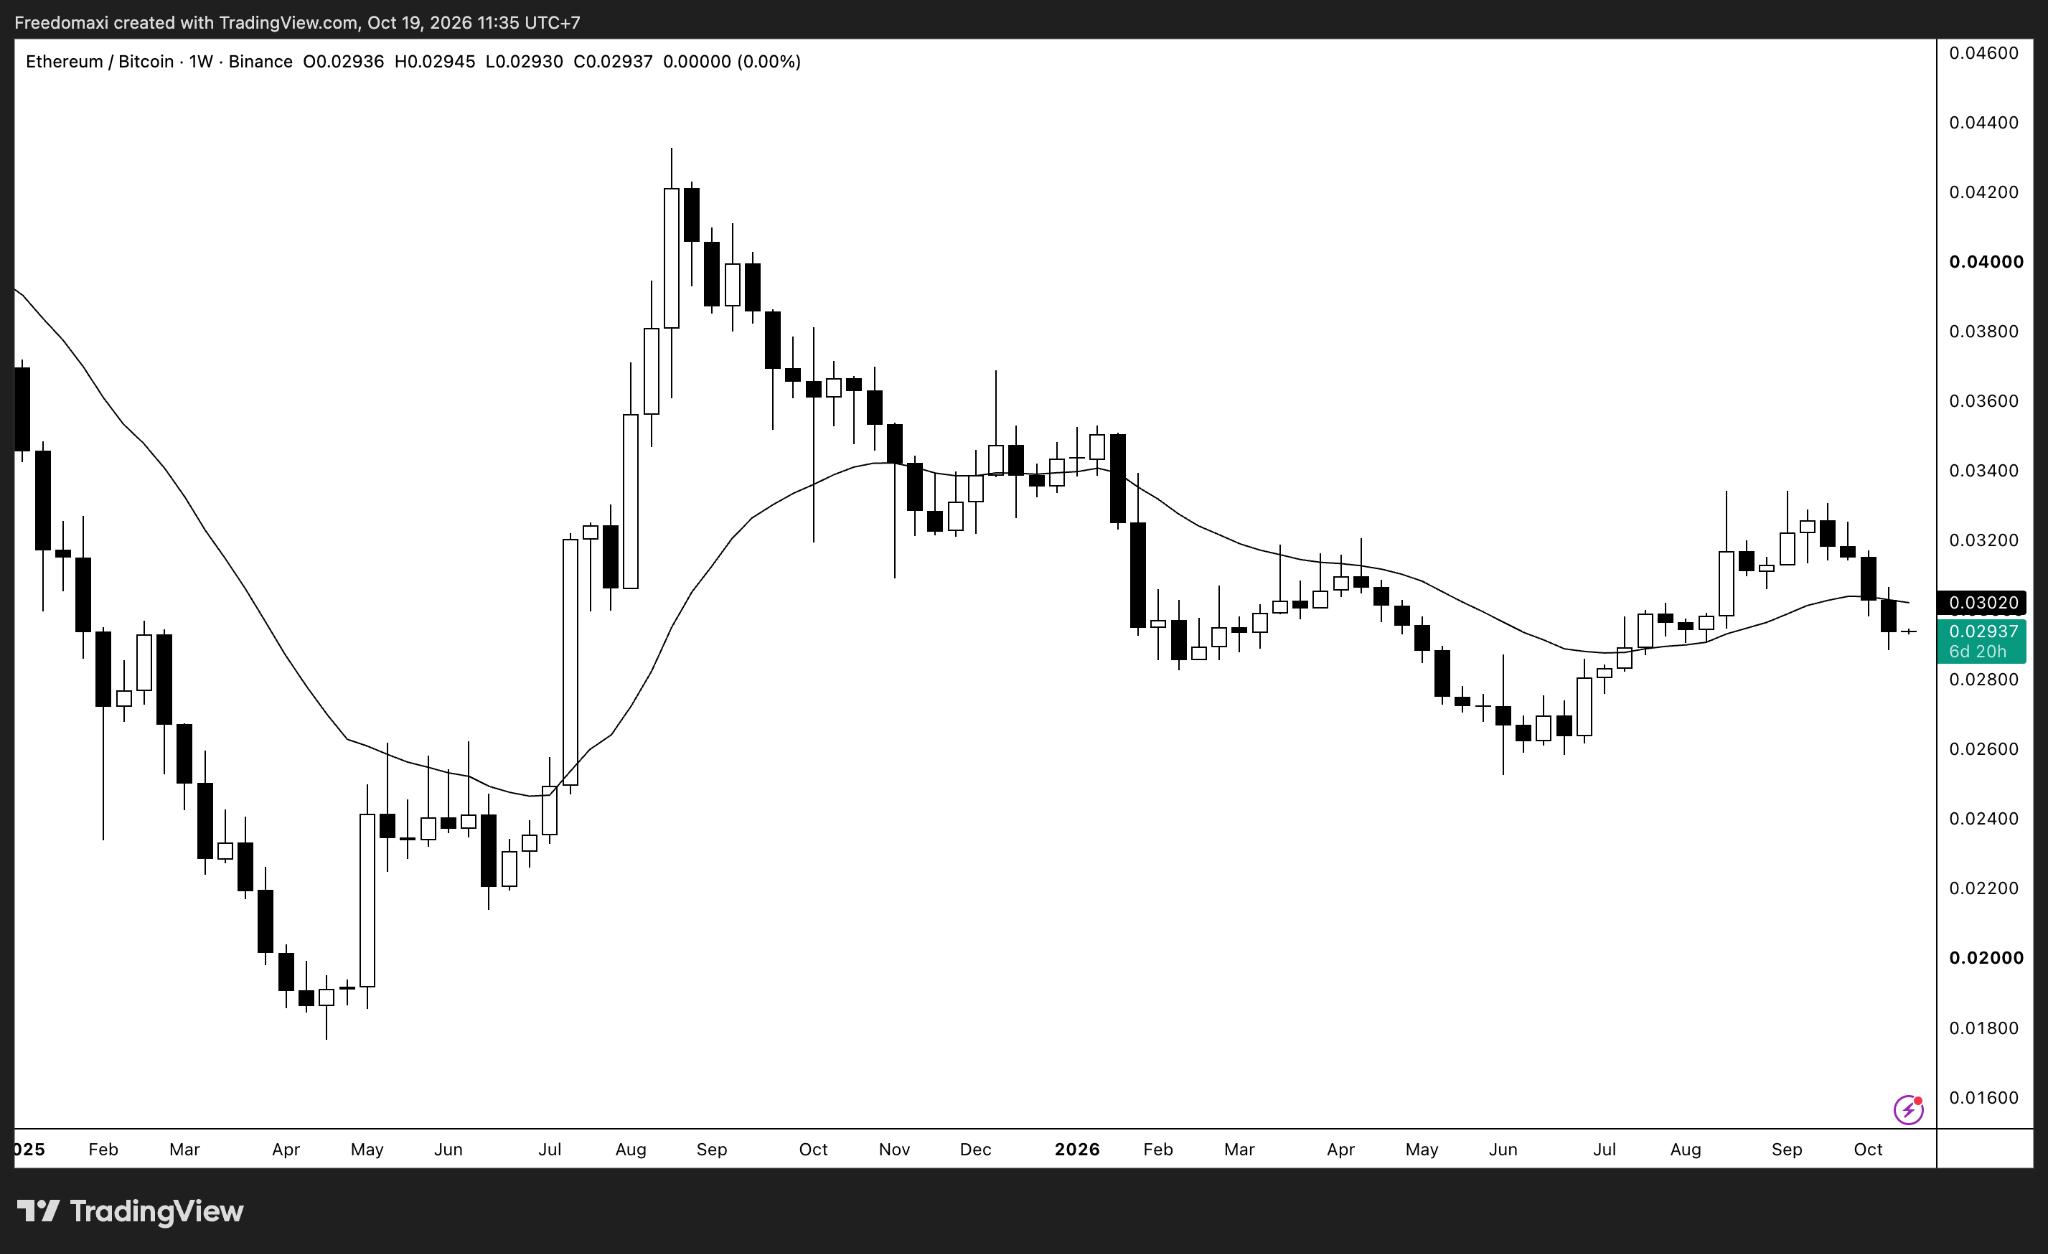
ETH/BTC fell again, closing near 0.0294, down about 2.8% after last week’s 3.9% drop. It is now below its 20-week average of about 0.0304, where it was level last week. Ether is losing to Bitcoin, which favors Bitcoin over alts. (TradingView ETHBTC)
Structural Shifts on Onchain activity: BSC is the real story
DEX volume held up this week.
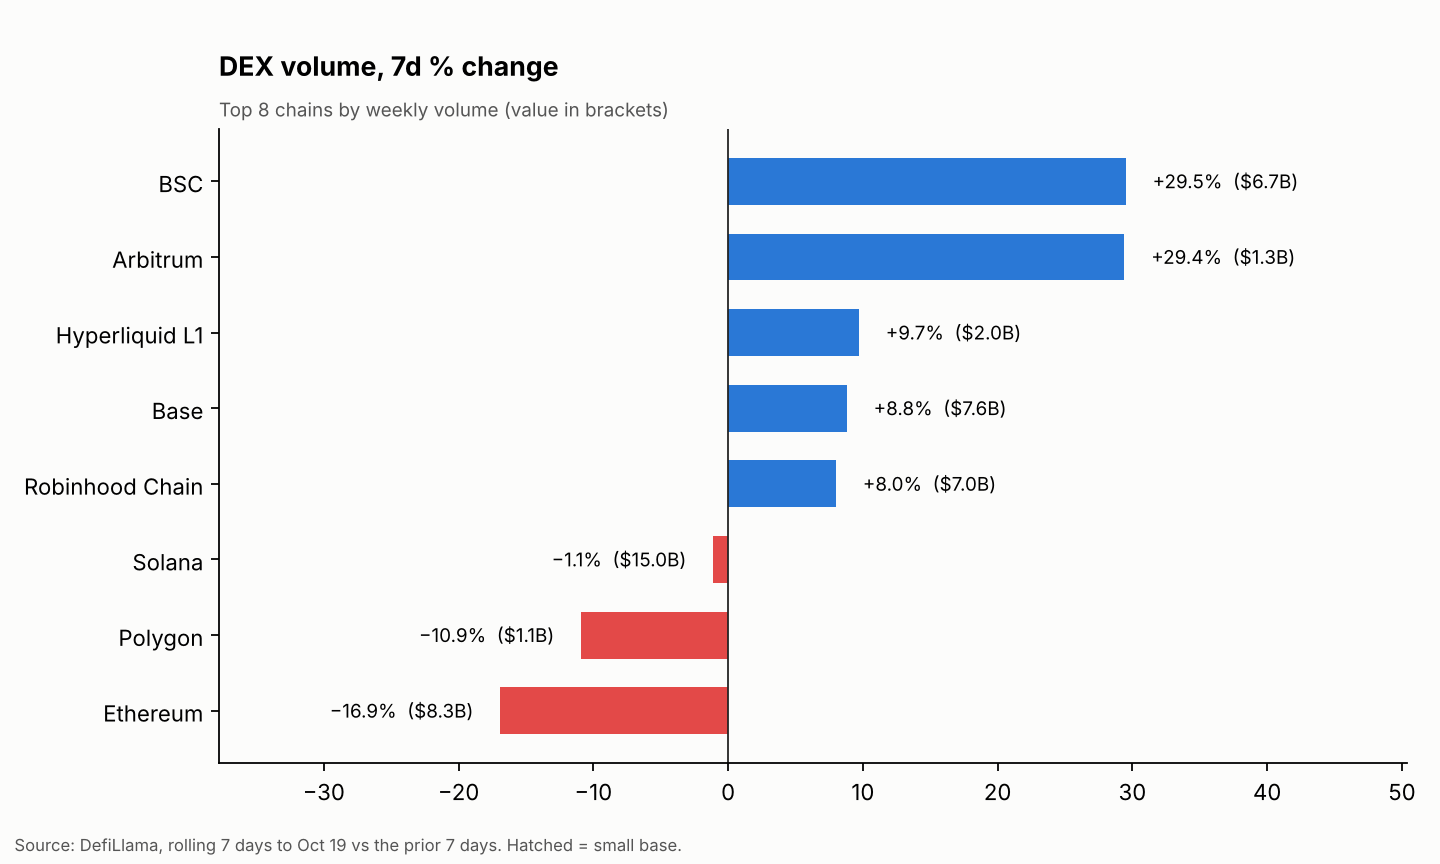
Across the 19 chains with data, weekly volume rose 1.1% to $52.2B (up about $0.6B), with 11 chains up and 8 down. BSC added the most (+$1.5B, +29.5% to $6.7B), then Base (+$0.6B) and Robinhood Chain (+$0.5B).
Where activity fell: Solana is weaker underneath.
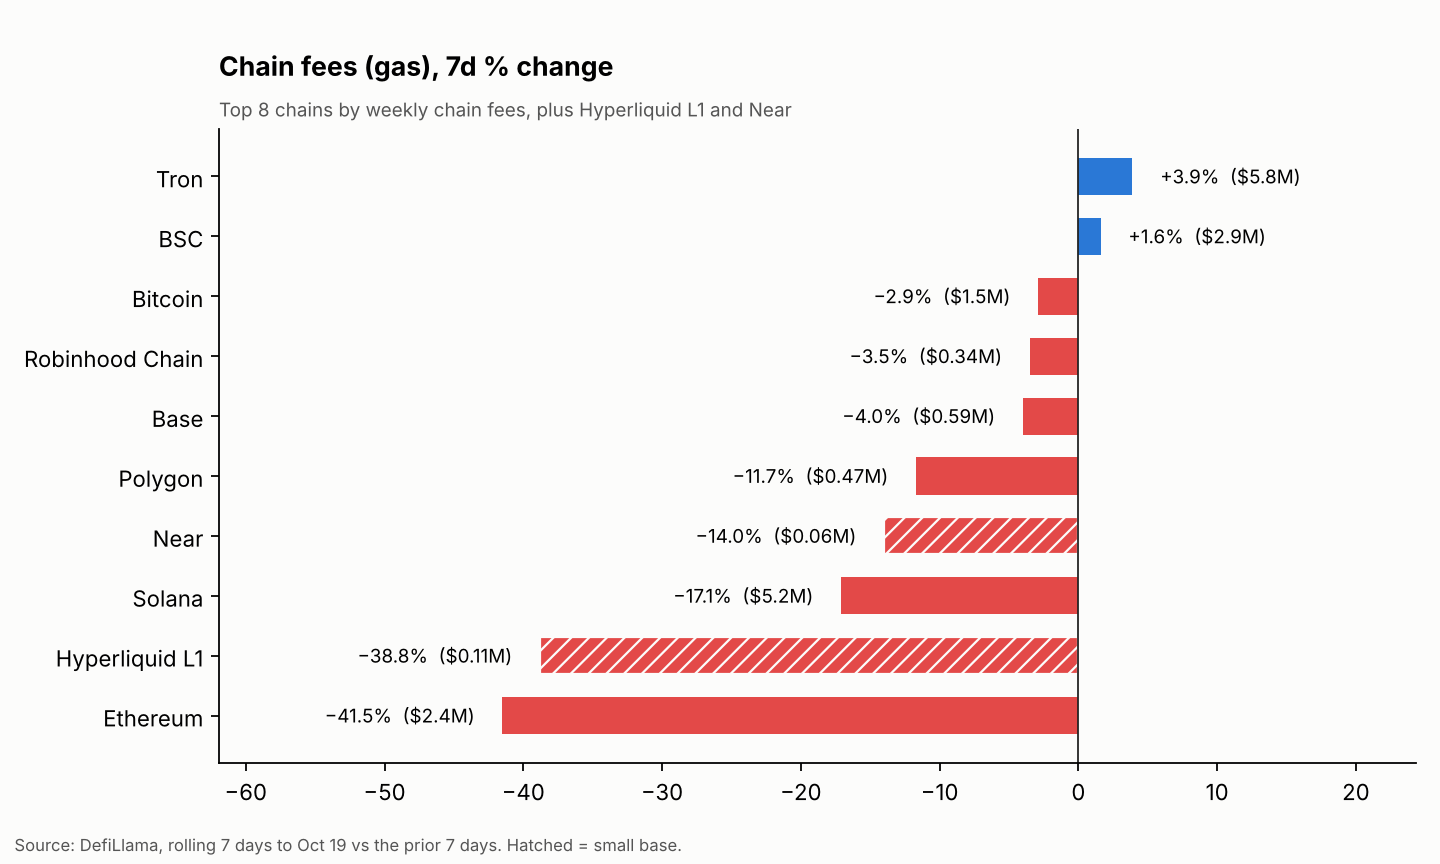
DEX volume was flat (-1.1% to $15.0B), but perp volume fell 16.8% to $8.0B, nearly all GMX on Solana (-$1.65B, -20%). Trading terminals keep sliding: Axiom Pro is down 45% and FOMO 36%. App fees fell 21.6% to $74M, and chain fees fell on Ethereum (-41.5%), Hyperliquid L1 (-38.8%) and Solana (-17.1%). (DefiLlama fees)
BSC has a catalyst, and the data backs it.
BSC is the only large chain with rising volume and TVL (+2.9% to $5.75B), though app fees fell 4.1% to $15.6M. PancakeSwap drives it.
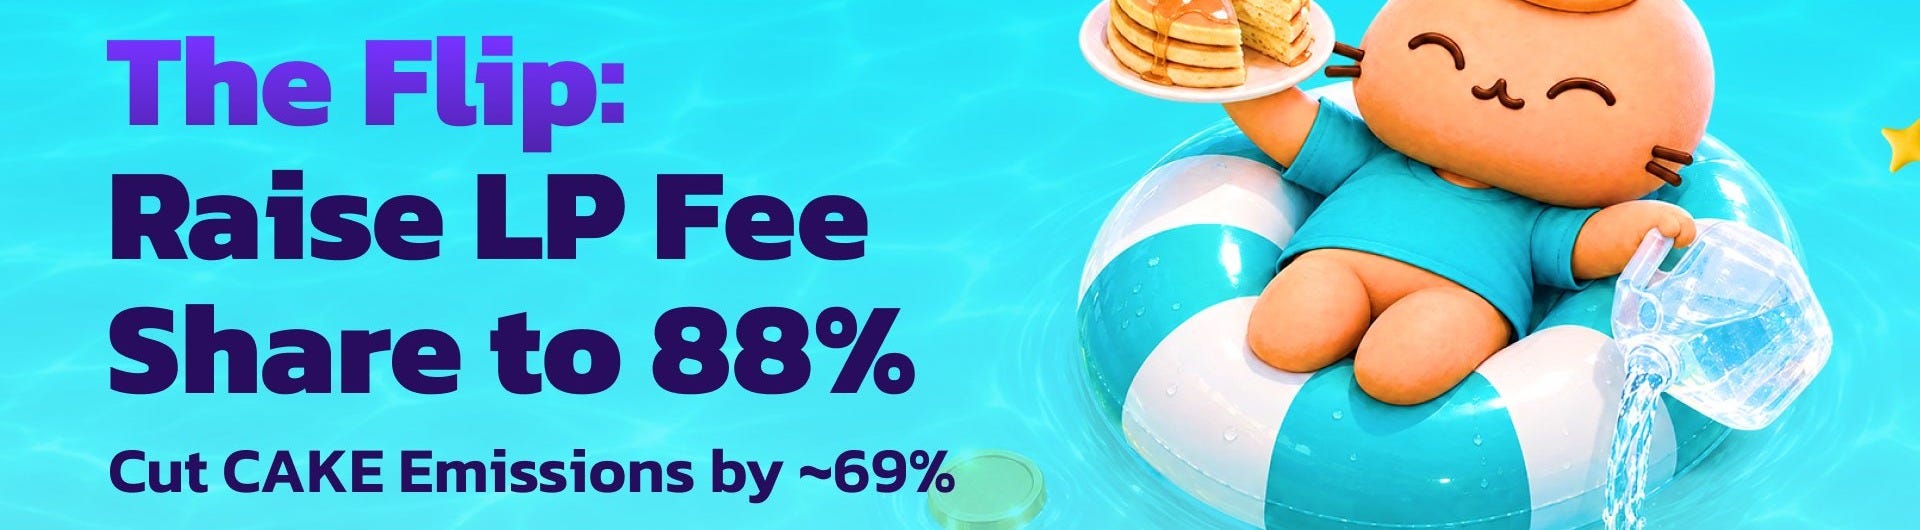
The catalyst is “The Flip” proposal (Oct 14, still in discussion): v3 and Infinity liquidity providers would keep 88% of swap fees, up from 66-68%, and daily CAKE emissions would fall from 22,500 to 7,000 (-69%), with the 7,000 going to an ecosystem fund. v2 is unchanged.
Plasma’s TVL gain is mostly a rebound.
Plasma TVL rose 6.3% to $555M. Aave added $36M (+8%) to $487M after falling on Oct 1, and it is back near late-September levels, so this is recovery, not new money. Plasma One, the stablecoin card and savings app, is up 3.5% on the week and 21.6% over 30 days to $15.2M. Chain transactions rose 20.2% while daily users fell 1.6%, so activity per user rose rather than the user base. (Plasma on DefiLlama)
Arbitrum is growing, led by Spiko, and incentives should add more.
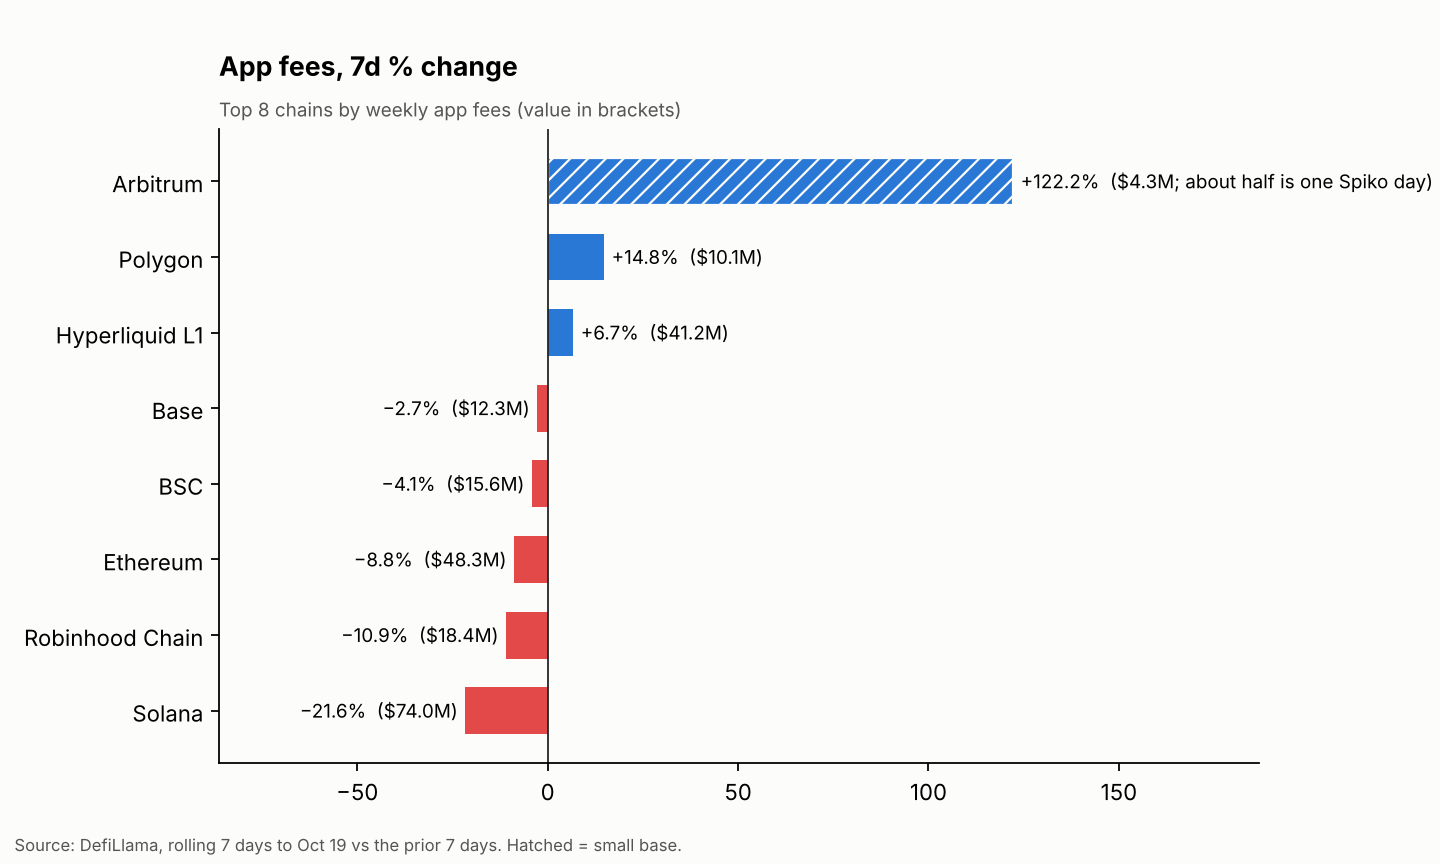
App fees rose 122% to $4.3M. Spiko, which tokenizes euro and dollar money-market and T-bill funds, accounts for about $2.06M of that, including $1.9M on Oct 15 alone, up from roughly $19K on a normal day.
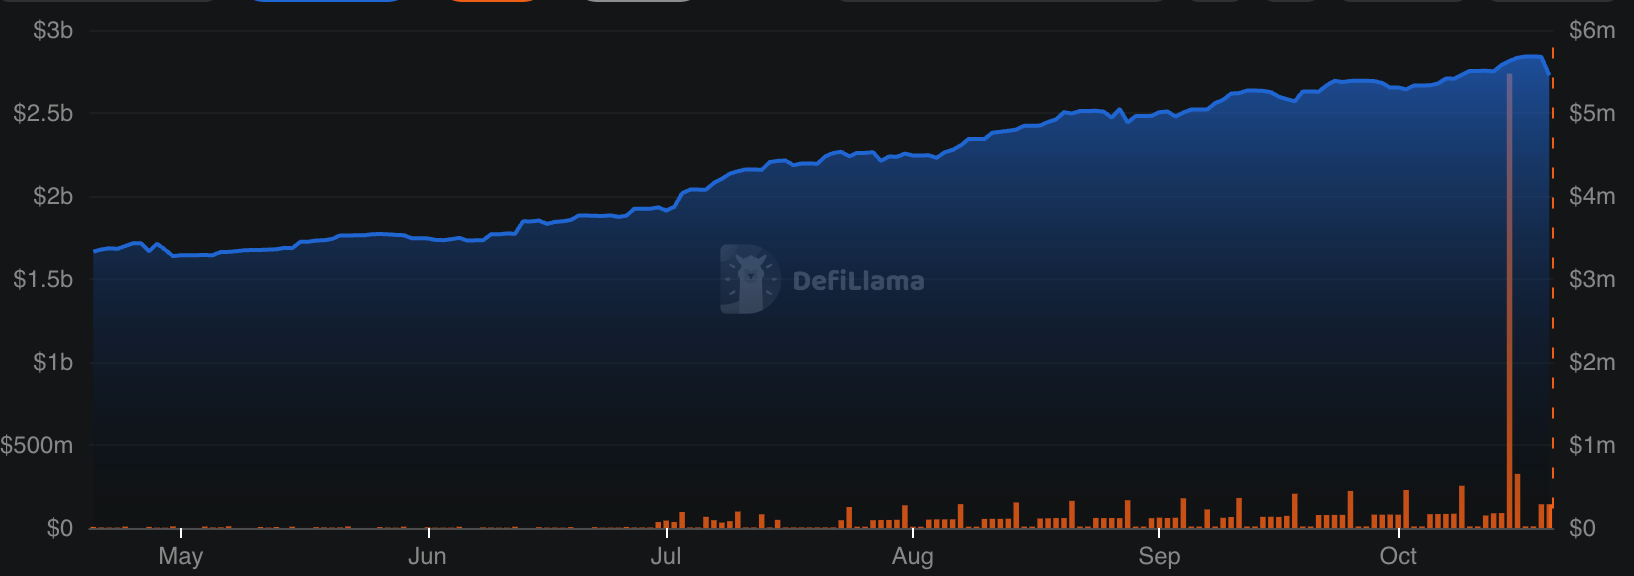
The same-day spike appears on every chain Spiko is on, so it looks like a step in the funds’ price feed, not a sudden rush of users. Spiko’s fees are yield from tokenized funds rather than trading demand, so read it as growth in tokenized assets, not in usage. Take Spiko out and Arbitrum’s app fees still grew about 13%.
The next push is DRIP, Arbitrum’s incentive program. Season 2 began on Oct 6 and focuses on USDG, and the DRIP page lists USDG vaults on GMX and Morpho paying about 8% APR. A separate proposal to add 100M ARB to the program has not been voted on. If the rewards keep flowing, expect more deposits to land on Arbitrum.
Project & Protocol Discovery
Token Price Movers - Observations, not trade ideas.
Fluid (FLUID), +5.0%
USDGO, the OCC-regulated stablecoin from OSL, launched with trading liquidity on Jupiter Lend’s AMM, which Fluid powers. That same day, it said the AMM had passed $1B in volume over two months, with only five pairs live. Fluid’s Ethereum DEX volume also rose about $205M over the week. (DefiLlama: Fluid)
Kamino (KMNO), +14.6%
Kamino’s Fixed Rates passed $55M in active loans, its AUTO market reached $150M, and tokenized-equity supply on Kamino passed $50M. It also launched Confidential SOL Yield on NEAR, run through a Gauntlet-curated vault. (Kamino on X)
Aster (ASTER), +3.0%
99% of its daily platform fees went to buybacks between Oct 5 and Oct 19, buying back 2.72M ASTER and burning an equal amount. A second post on Oct 14 added an extra buyback of about 1.4M USDT, at roughly $100K a day for 14 days starting Oct 15. (Aster on X)
Curve (CRV), +5.9%
Curve’s DEX fees hit $1.01M, up 61.7% from $623K the week before. But $374K of that came on Oct 12 alone, and fees were back to about $40K a day by the weekend. The week before had a similar one-day spike ($273K on Oct 7). The jump comes from a few big days, not a steady climb. (DefiLlama: Curve)