
Subscribe for daily free DeFi news covering launches, tradable catalysts, and actionable farming opportunities.
Today’s News Headlines:
Ari Paul alleges Coinbase covered up $1B+ in hacks
Bitget resumes BTC withdrawals post-$387.5M exploit
Jumper‘s JUMP token sale opens September 29
Aave mobile app adds direct Ethereum deposits
Ondo Perps launches spot trading for Ondo Stocks
Avant Protocol launches on Base via Morpho
WOO X launches dedicated MiCA-aligned EU platform
Maple Finance upgrades Syrup tokens to CCIP 2.0
Key Takeaways:
Leverage got about 40% cheaper to hold this week, and ETFs pulled in $2.39B, the highest weekly inflow in 2026.
Funding rates fell from ~7% to 4.42% below the average stablecoin borrow cost; BTC and ETH kept leaving exchanges; stablecoin supply grew $1.32B; and funding fell from ~7% to 4.42% — all reading as accumulation.
Solana and Hyperliquid L1 absorbed 93% of this week’s stablecoin growth
For opposite reasons: one is a minting rebound, the other is a brand-new lending market that just launched.
Six of the week’s seven biggest token gainers are tied to stocks moving onchain
ONDO gained 33% on a new BlackRock-designed portfolio product, ENA gained 31% on stock-backed collateral, and three others moved on related news.

Find and execute the 15%+ stablecoin yields in minutes
Save time without checking every protocol manually. DeFi Saver’s Discover page surfaces rates across Aave, Morpho, Spark, and more, lets you simulate leverage before committing, and handles the full loop in one click. Stop leaving yield on the table.
<Discover Yields on DeFi Saver> | Today in DeFi is Supported by DeFi Saver
This Week’s Signal: Stocks Are Becoming DeFi’s Collateral

The single biggest thread this week wasn’t a chain or a token — it was stocks moving onchain, and it touched almost every section of this letter.
It started with regulation. On Sept 17, the SEC granted a temporary exemption letting onchain liquidity pools trade tokenized equities, clearing a legal hurdle that had kept most DeFi apps from listing them directly. Within days, five separate protocols built products on top of it.
Ondo launched Intelligent Portfolios on Sept 24 — three tokens, each wrapping a full BlackRock-designed portfolio strategy into one transferable onchain instrument. Ondo issues and manages the tokens; BlackRock supplied the strategy design only. ONDO rose 33.4% on the week.
Ethena began backing USDe with Binance’s tokenized stocks on Sept. 25, hedged with equity futures the same way it’s long-hedged crypto. Ethena says this expands its addressable collateral from $2.5T of crypto to $150T+ of real-world assets — its own framing, not an independent estimate. ENA rose 31.4%.
Raydium said Solana crossed 1 million tokenized stockholders on Sept. 24, a self-reported figure. RAY’s most-traded pairs this week included SPX and STONK, both memecoins that piggyback on the “stocks onchain” narrative rather than real equities. RAY rose 34.8%, extending a rally that started with a 97% jump in the week to Sept 12.
Aerodrome’s merger with Velodrome, going live Oct 21, is deploying on Robinhood Chain specifically because that’s where the tokenized-stock trading volume is landing. AERO rose 28.3%, mostly in one day.
Pyth, meanwhile, became an external distributor of Nasdaq’s real-time quote data on Sept 22 — the data layer underneath all of this. PYTH rose 44%.
Macro in 3 Lines
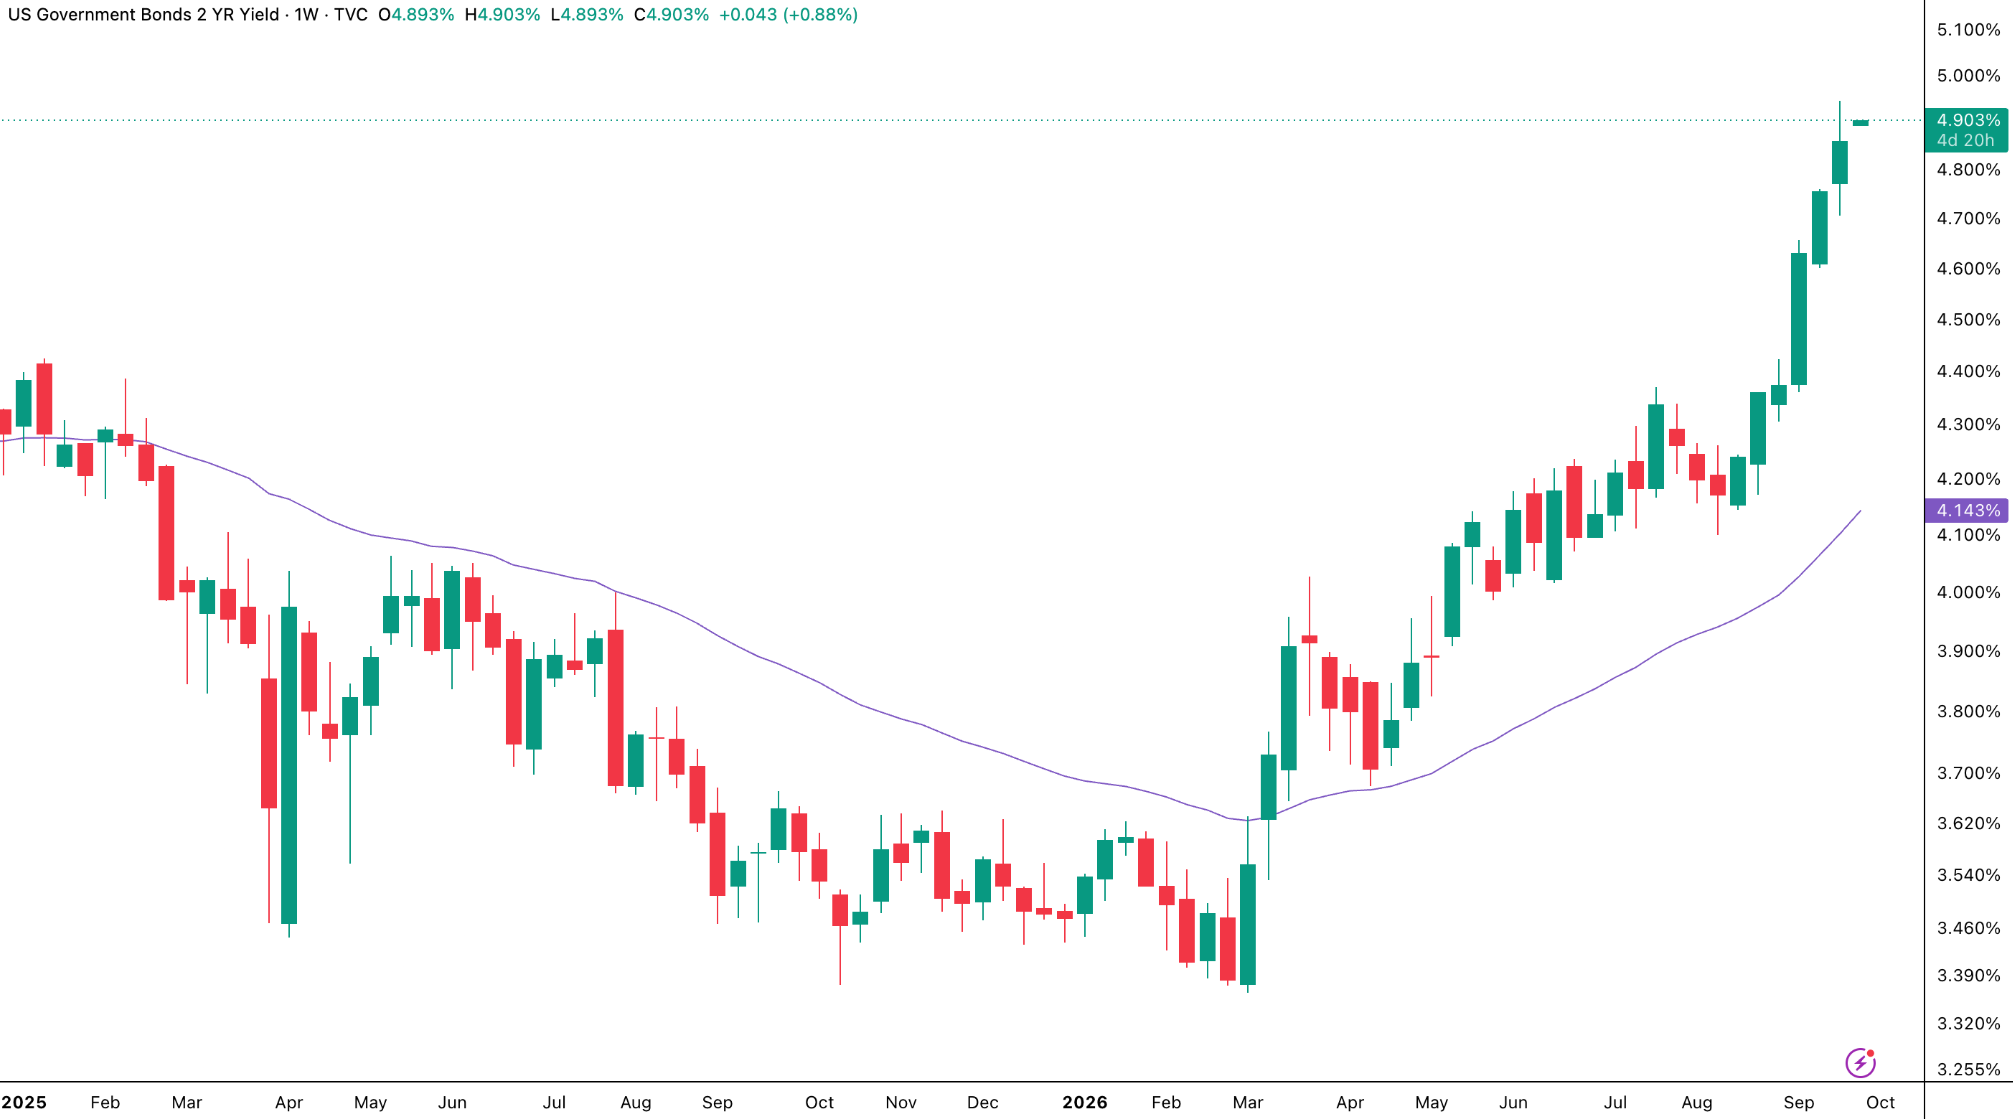
Rates and the dollar. The 2-year Treasury yield, the one most tied to Fed expectations, rose about 10bp to 4.86%. The dollar index gained 0.8% to 101.0, its first back-to-back weekly gain since June.
Both moved on the same Wednesday: business surveys came in far hotter than expected, Fed Governor Barr said more hikes are likely, and a weak 5-year auction pushed yields higher.
Week-Ahead Catalysts
Macro:
Wed Oct 1: August PCE and Q2 GDP, 8:30 AM ET. PCE is the Fed’s preferred inflation gauge — the first reading since markets moved to pricing in about a two-in-three chance of an October hike.
Fri Oct 2: September jobs report, 8:30 AM ET. Forecasts call for +100K jobs, down from 162K, with unemployment rising to 4.2%.
Three crypto events to watch:
Jumper (JUMP), Sept 29 to Oct 2: first token sale. The cross-chain trading app has processed $40B+ in lifetime volume with 100,000+ monthly users. Sale runs on Legion; no company equity, so the token is the only way in. US, UK, and UAE are excluded.
Hyperliquid (HYPE), Sat Oct 3: first buyback funded by USDC yield. ~90% of interest earned on USDC held on Hyperliquid funds a market buy of HYPE. Analysts estimate $135–160M/year, but the amount moves with USDC balances and rates.
Ethena (ENA), Mon Oct 5: all remaining investor tokens unlock at once. Ends the vesting schedule 17 months early. Ethena hasn’t disclosed the size; trackers estimate ~14% of circulating supply. ENA roughly doubled in September heading in. Buyback stays off until USDe supply hits $7.5B.
Capital On-Ramp

Spot Bitcoin ETFs took in $2.39B from Sept 21–25, their strongest week of 2026, beating the previous high of $1.92B in August. Every day was positive, but the pace fell sharply — from $999M Monday to $134.5M Friday. Ether ETFs added $689.8M, reversing last week’s −$140.9M outflow (their first since July). Solana ETFs added $188.1M.

Exchange balances fell at the same time. BTC held on exchanges dropped 1.4% to 2.689M BTC, reversing last week’s rise — coins moving off exchanges usually means holders are keeping them rather than preparing to sell. ETH on exchanges fell 1.1% to 14.64M, most of it on Sept 22–23.

Stablecoin supply grew $1.32B (+0.43%) to $306.4B — new stablecoins arriving onchain, though modest against the ETF number.
Verdict: Institutional demand was the strongest of the year and held Bitcoin up through a bond selloff, but it was front-loaded and didn’t carry price higher after Monday.
Onchain Risk Regime
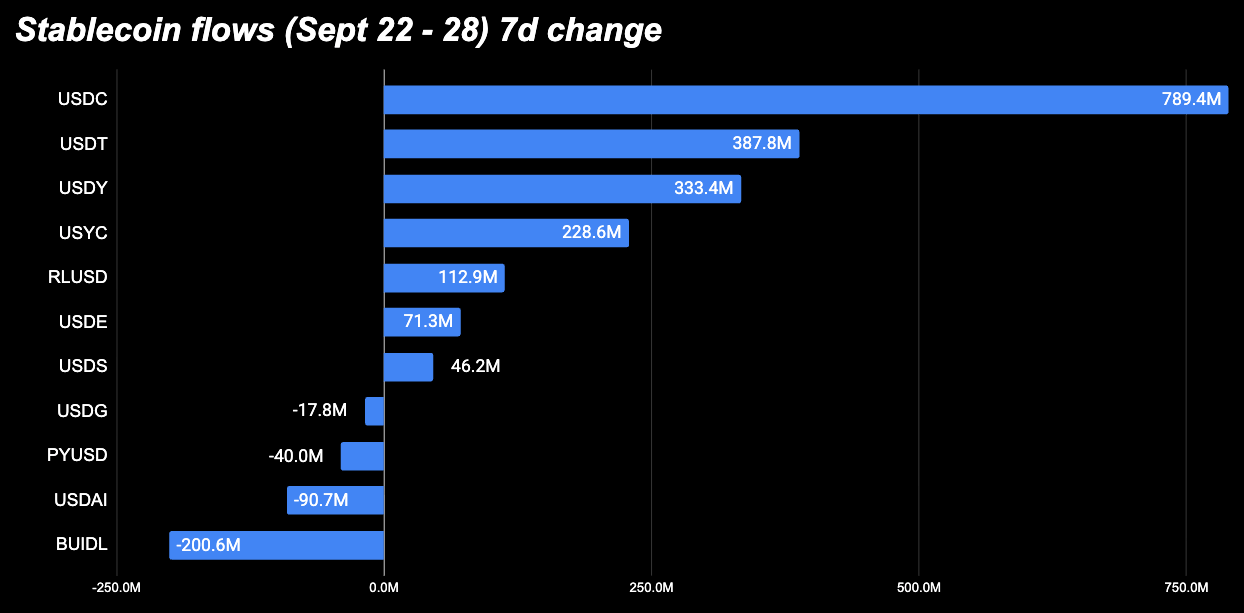
USDC added $789M, and USDT added $388M. Tokenized Treasury funds, held mainly for yield rather than trading, split: Ondo’s USDY grew $333M and Circle’s USYC grew $229M, while BlackRock’s BUIDL fell another $201M (−24.4% over 30 days).
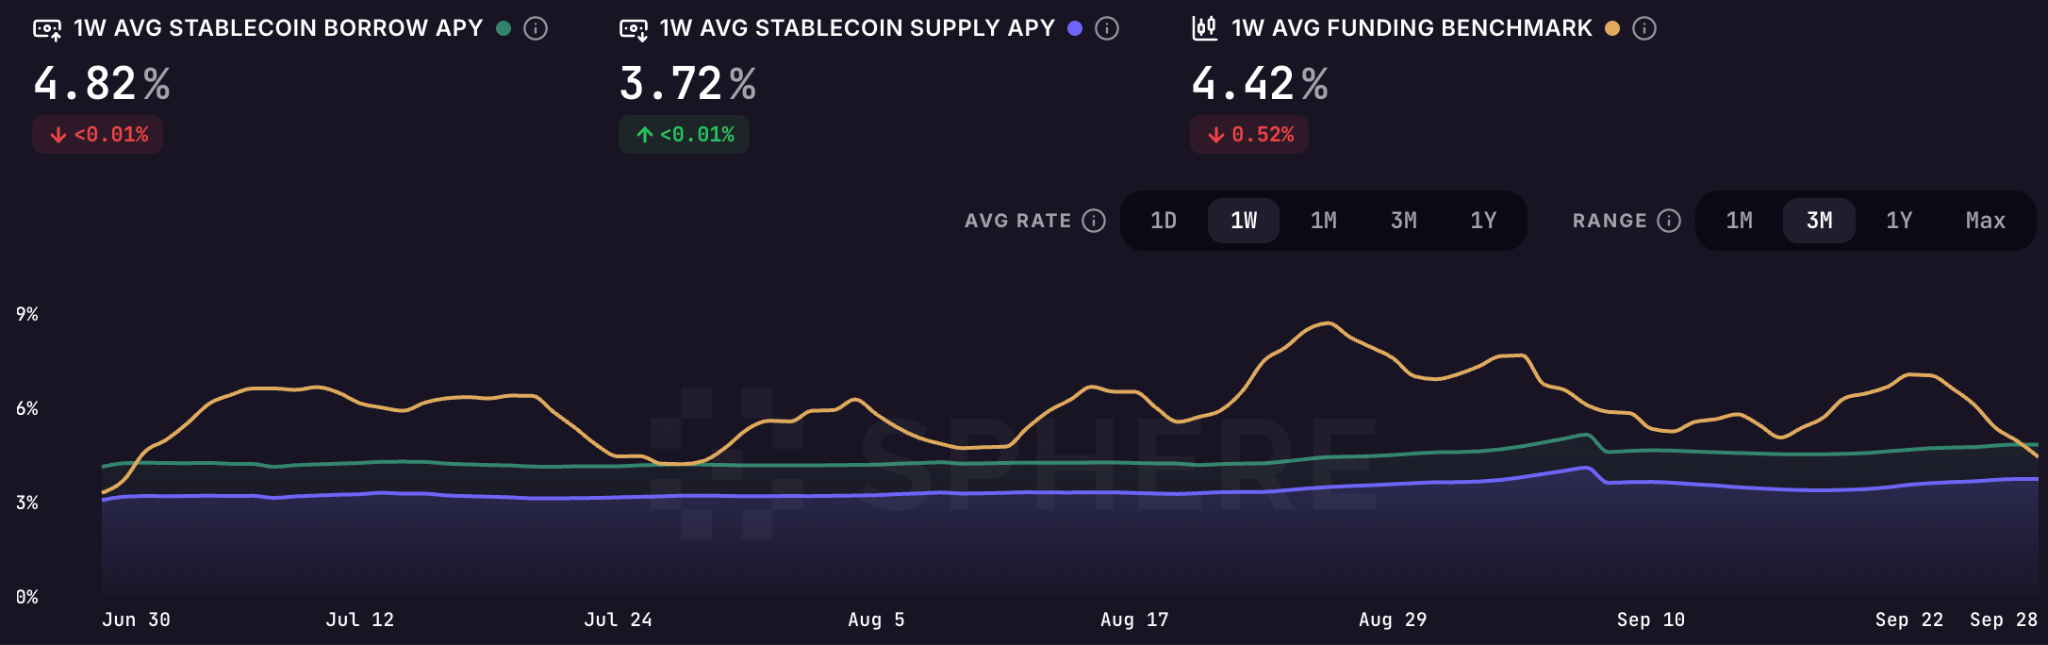
The cost of borrowing stablecoins was 4.82%, and lenders earned 3.72%. The funding rate — what leveraged perpetual-futures traders pay to hold positions — fell to 4.42% from about 7% around Sept 20, now sitting just under the borrow rate. The gap that made leverage expensive last week has closed.
ETH/BTC closed down about 2% at 0.0318, still above its 20-week average of 0.0304. ETH lost ground to BTC, even though Ether ETFs saw $690M in inflows compared with Bitcoin’s $2.39B.
Verdict: Trading cash is arriving, and leverage got cheaper to hold, while ETH lagged BTC and a top tokenized-Treasury fund shrank for a second straight week — MIXED, tilted risk-on.
Chain Comparison: Solana and Hyperliquid L1 took 93% of the week’s growth
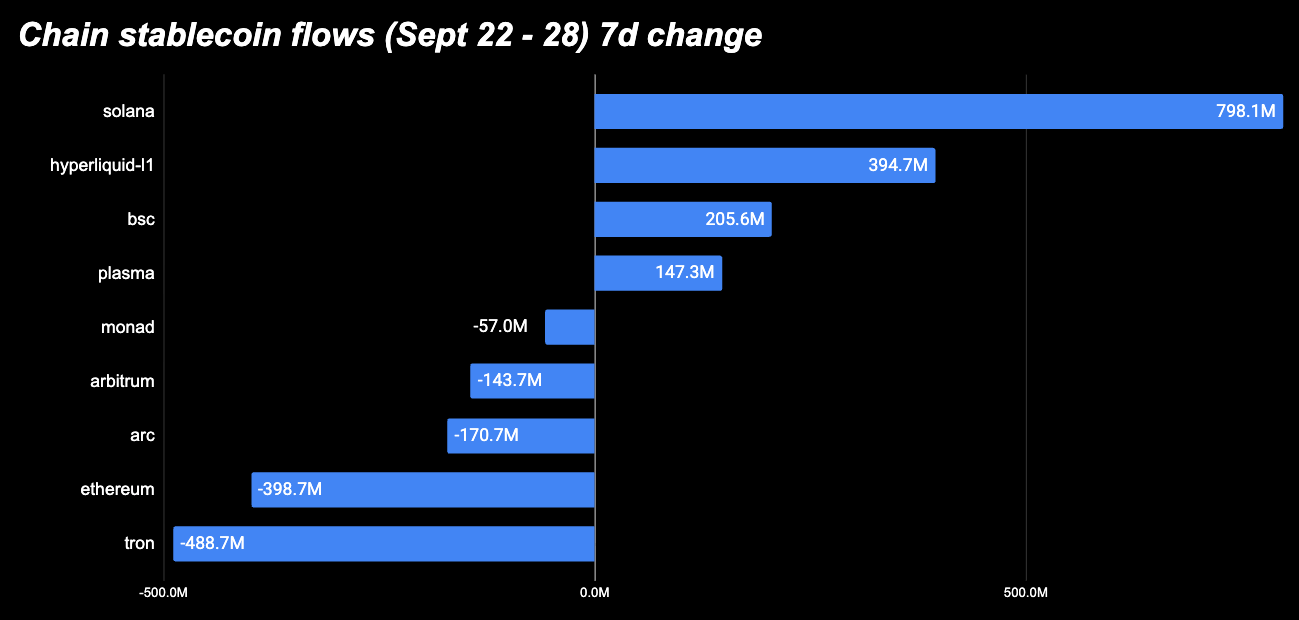
Stablecoin supply rose $1.32B (+0.43%) to $306.4B in the last 7 days. Solana added $835M and Hyperliquid L1 added $396M, together 93% of that. The two gains came from different coins, and Hyperliquid’s is all USDC, not USDT plus USDC as first thought.
Solana: +$835M (+5.35%), two-thirds of it USDT
USDT rose 26%, about +$550M, to $2.67B.
USDC added about $186M, to $7.24B.
This is a rebound. USDT on Solana fell about $720M over the prior three weeks, so this week recovered most of it.
The trigger was a burst of minting when issuers created new coins for a customer who deposited dollars. SolanaFloor reports that Tether minted $530M of USDT and Circle $751M of USDC on Sept 25, pushing supply to a record $17.3B by Solana’s own count. That is single-sourced, and DefiLlama’s total is lower. USDC’s net gain of $186M against $751M minted shows gross minting overstates growth, because redeemed coins are burned.
Where are the stables flowing?
Jupiter Lend hit a record $2.41B in deposits on Sept 22, up 27% from August over about six weeks. With $823M borrowed, utilization is 34%, meaning most supplied money is idle.
Kamino Lend holds about $2.6B supplied with $1.07B borrowed.
Kamino widened what stablecoins can be borrowed against. On Sept 22 it launched Fixed Rates, which lock a borrow rate for a term. The first vault, built with Hastra and Figure, charges 5.3% on rolling 30-day terms. It also opened a sterling market (tGBP) and, on Sept 24, a market for USD.AI’s sUSDai token. These add credit demand, but at these sizes they don’t account for a $550M USDT increase.
Hyperliquid L1: +$396M (+5.46%), all USDC
USDC on Hyperliquid is now $7.55B, more than Solana’s $7.24B. USDT there is only $85.5M and grew $1M.
On Sept 18, Hyperliquid launched a lending market built into its exchange. Users pledge HYPE or BTC as collateral to borrow USDC or USDT, and $269M was borrowed on day one. HYPE hit a record $94.45 the next day. The timing fits the USDC gain.
Only $634M, about 8%, sits in the separate HyperEVM lending apps (HyperLend $429M, Morpho $193M). Most of the rest is collateral for trading.