
Subscribe for free daily news headlines, weekly news recap, on-chain trading outlook, airdrops, and actionable farming opportunities.
Find and execute the 15%+ stablecoin yields in minutes
Save time without checking every protocol manually. DeFi Saver’s Discover page surfaces rates across Aave, Morpho, Spark, and more, lets you simulate leverage before committing, and handles the full loop in one click. Stop leaving yield on the table.
<Discover Yields on DeFi Saver> | Today in DeFi is Supported by DeFi Saver
Farming Benchmarks:
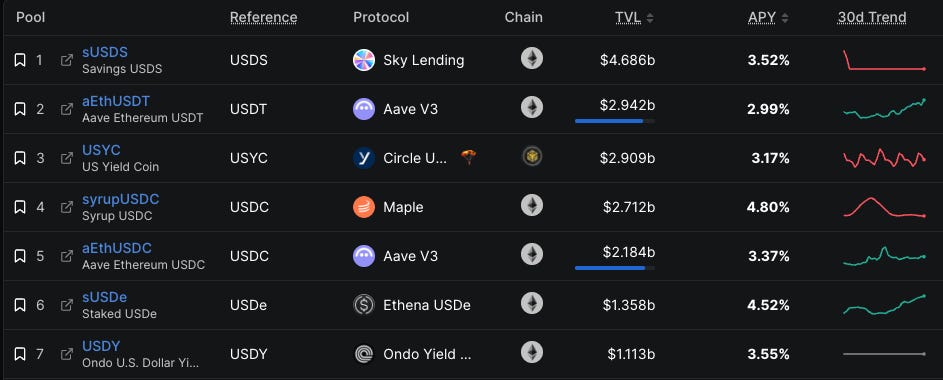
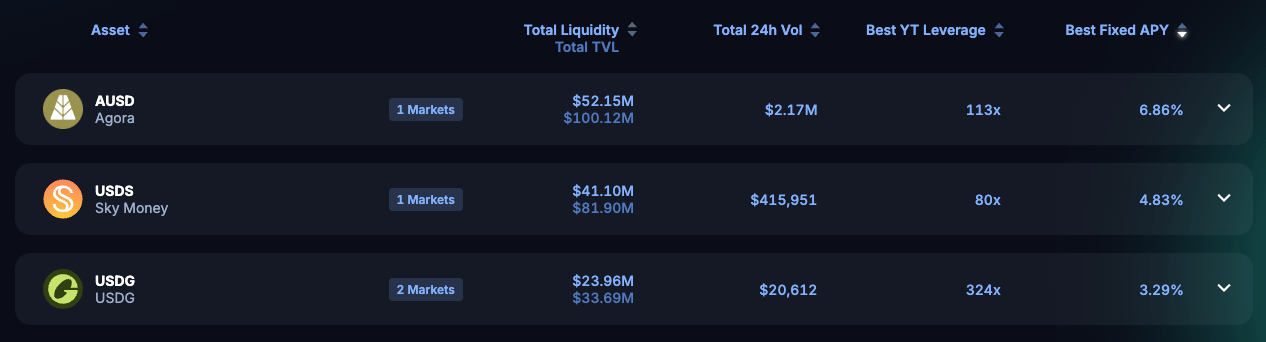
Every farm below beats that baseline. When a rate looks too good relative to this range, that gap is usually the incentive/emissions component, not organic yield — check the breakdown in each card.
Curve Llamalend (Arbitrum – Lending) – crvUSD/WETH Market – 6.5% Net Supply APY

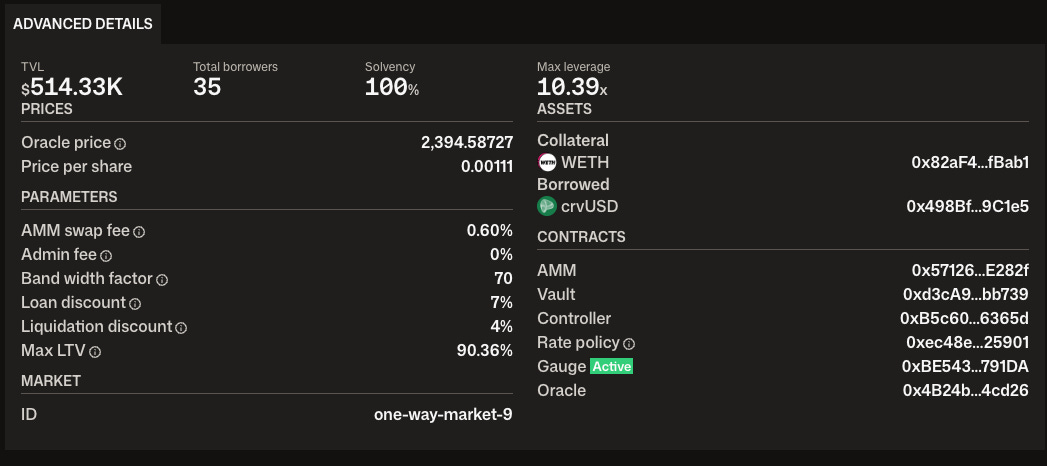
You’re supplying crvUSD into a Curve Lend market where WETH is posted as collateral. Borrowers deposit WETH and borrow crvUSD against it — often to open leveraged WETH longs, since the market offers up to 10x through its built-in leverage feature — and the interest they pay is what flows to you as the Net Supply APY.
Risk notes: the native risk in any lending market like this is that collateral value falls faster than the system can liquidate it. Llamalend uses a “soft liquidation” (LLAMMA) mechanism that gradually rebalances a borrower’s WETH into crvUSD as price drops, instead of a one-shot liquidation — gentler in an orderly decline, but it can still fall behind in a violent crash, leaving bad debt that suppliers absorb.
There’s also oracle risk (liquidations depend on price feeds staying accurate and timely) and liquidity risk — utilization is already at 72% here on a small market (~$513k TVL, ~$66k actually available), so if several suppliers want out at once, you may be waiting on borrowers to repay rather than withdrawing on demand.
Risk — Low ⚠️
The native risk in any lending market like this is that collateral value falls faster than the system can liquidate it. Llamalend uses a “soft liquidation” (LLAMMA) mechanism that gradually rebalances a borrower’s WETH into crvUSD as price drops, instead of a one-shot liquidation — gentler in an orderly decline, but it can still fall behind in a violent crash, leaving bad debt that suppliers absorb. There’s also oracle risk (liquidations depend on price feeds staying accurate and timely) and liquidity risk — utilization is already at 72% here on a small market (~$513k TVL, ~$66k actually available), so if several suppliers want out at once, you may be waiting on borrowers to repay rather than withdrawing on demand.
Fluid (Plasma – Lending) – GHO – 8.05% Net APR
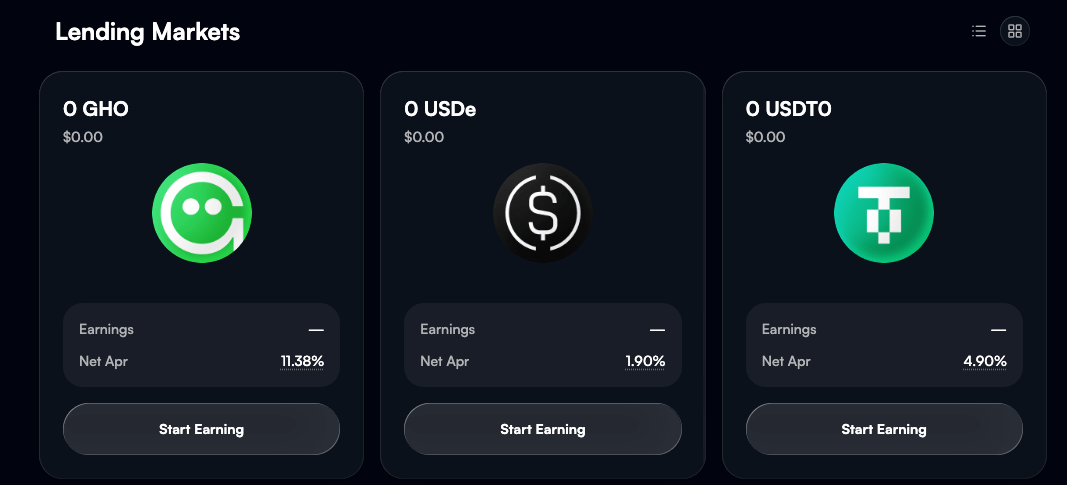
How the yield is generated: same basic shape, different venue. You supply GHO, and borrowers post collateral (whatever assets Fluid supports on its Plasma deployment) to borrow GHO against it, typically to lever up or free up stablecoin liquidity without selling their holdings.

On collateral exposure: as a GHO supplier, you are exposed to the underlying collateral, including, and mostly, sUSDai. sUSDai is the yield-bearing token of USD.AI, a protocol that lends against GPU/AI-infrastructure hardware — it’s backed by a book of GPU-collateralized loans to data center operators, plus a Treasury-bill buffer for idle cash.
sUSDai “is not a stablecoin” and “is not instantly redeemable at par” — unstaking runs on 30-day epochs processed FIFO, and the protocol will not liquidate its own active loans early just to meet redemptions.
Fluid’s liquidation process depends on being able to sell or unwind sUSDai quickly at a fair price. If a liquidation can’t clear cleanly under stress, GHO suppliers on this market are the ones who’d absorb that shortfall.
Risk - Medium ⚠️
The native lending risk is the same category as farm 1 — if collateral backing the GHO borrows drops faster than liquidations clear it, suppliers eat the shortfall.
That risk is arguably a bit higher here than on an Ethereum mainnet market simply because Plasma is new: less time for its oracle feeds and liquidation bots to be stress-tested, shorter track record generally.
Same utilization/withdrawal risk applies if a lot of GHO suppliers want out at once.
IPOR – Liquity ETH Carry Vault – 6.5% Spot APY
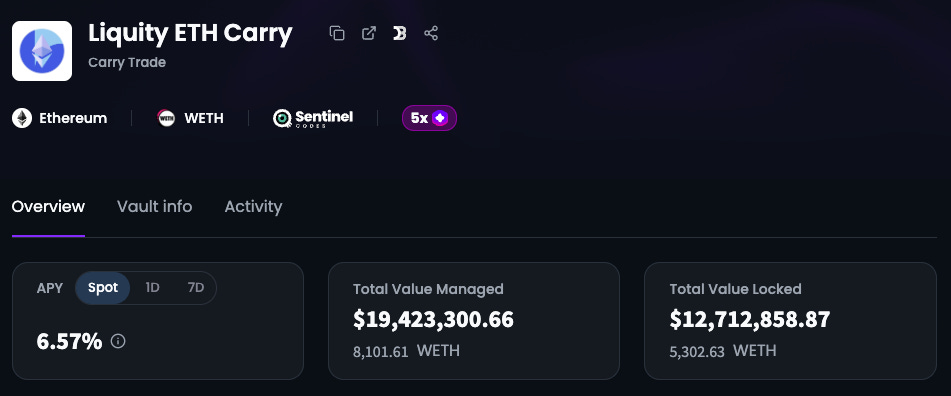
The vault currently optimizes wstETH rates by collateralizing it in a Liquity Trove, borrowing BOLD at the branch-specific fixed rate, and deploying the BOLD into a Curve BOLD/USDC LP — all programmatic, with conservative LTV constraints and continuous monitoring of borrow spreads, peg stability, and unwind capacity.
Leverage expands only when net carry is positive and contracts automatically if spreads invert or liquidation buffers deteriorate. Only 705 WETH is still available to deposit before caps are filled.
<Farm the Liquity ETH Carry on Ipor> | Today in DeFi is supported by Liquity
Risk — Medium-Low
(1) your WETH is converted to wstETH or rETH and deposited as collateral on Liquity V2 to mint/borrow BOLD — standard CDP liquidation risk applies here if wstETH’s value drops relative to the debt;
(2) the borrowed BOLD is then supplied into the BOLD/USDC Curve pool to farm BOLD from PIL emissions and CRV rewards — this adds impermanent loss exposure and CRV emissions risk on top of the borrowing position;
(3) LTV targets a relatively conservative 55%. BOLD itself carries peg risk as its a CDP stablecoin without strong arbitrage mechanisms.
Convex (Ethereum – Boosted Curve LP) – ETH+/WETH LP – 7.5% Projected vAPR

You deposit into a Curve pool holding ETH+ and WETH and earn a cut of the trading fees generated when people swap between them. On top of that, Curve pays CRV emissions to the pool’s gauge, and staking your LP token on Convex adds CVX rewards on top, with your CRV leg boosted 2.21x through Convex’s pooled veCRV lock.
So the 7.67% is fees plus boosted CRV plus CVX combined — and since two of those three legs are token emissions rather than fee income, the rate moves with CRV/CVX prices and gauge-weight votes, not just trading activity.
ETH+ isn’t backed by a single asset — it’s 100% collateralized by a basket of four ETH liquid staking tokens:

Blended native yield across the basket is 2.35%, and there’s an 8% Staked RSR buffer sitting on top as a first-loss cushion — funded by RSR stakers, designed to absorb losses before ETH+ holders are affected. 1 ETH+ currently redeems for 1.10 ETH.
Risk notes⚠️: the native risk in any LP position like this is impermanent loss — if ETH+ and WETH drift apart in price, the pool automatically shifts you into more of whichever asset got weaker, so you can end up worse off than just holding the two separately. Because both sides are ETH-pegged, day-to-day divergence is usually small, similar to a stable pool, but it can widen fast and sharply if ETH+ comes under stress.
This Week’s Farming News:
Bitwise’s Premium RWA Vault (PAPY) surpassed $20M in deposits on Morpho within two weeks of launch — earning 7% yield by lending AUSD against RWA collateral from Huma Finance, USDai, and Hastra.
Maple launches syrupUSDC on Arc, establishing an institutional lending market with approximately $1B in loans.
Aave announces the launch of a specialized RWA lending market on Avalanche.
Aave plans to enable on-chain borrowing against assets held in qualified custodians, powered by Anchorage and Chainlink.
Strata’s Senior nOPAL launches on Pendle with a maturity date of January 7, 2027. Existing users can migrate to srnOPAL to continue earning >10% APYs.
Today’s News Headlines:
Arc Mainnet Launches With BlackRock, DTCC as Validators
Aerodrome Deploys on a New Chain for the First Time in 3 Years
Senate Democrats commit to passing CLARITY Act before year-end
Tera Portföy fails redemptions on ~$7.5B in funds, threatening DeFi carry trade products like Tori and Piku
Ostium faces lawsuit after unpaid $15M loan
Robinhood employees charged with insider trading on Hyperliquid
Federal Reserve raises interest rates by 25bps.