
Subscribe for daily free DeFi news covering launches, tradable catalysts, and actionable farming opportunities.
Today’s News Headlines:
Anthropic files public S-1 with the SEC
Base launches Trencher Grants of $1,000–$5,000
Soneium unveils tokenized IP vision, planned $SONEIUM token
Bloom Trading reimburses users after $947K Solana hack
JPMorgan brings JPM Coin to Ethereum
Ripple launches 24/7 AI-powered treasury management
Keystone hardware wallet breach leaks ~26K buyers’ data
Kraken parent to launch CFTC-regulated markets on Hyperliquid
BNB Standard rings Nasdaq bell with CZ
Avant opens Season 1 buyback at $0.025 per AVANT
Key Takeaways:
Regime: risk-off and not improving.
Stablecoin supply fell for a third straight week, and the cost of holding leveraged longs rose to 6.8% annualized while stablecoin borrowing sits at 4.7%. Leverage is building even as prices fall ahead of Wednesday’s Fed decision. CHECK: your workbook’s “Verdict” line was blank. This is my read from the numbers. Change it if your read differs.
Activity fell everywhere this week
DEX volume fell 12.9% to $44.7B, with 16 of 19 chains lower and gas fees down everywhere. Plasma (+28.6%) and Polygon (+12.2%) went the other way, but one app is behind much of Polygon’s gain.
Product expansions won the attention
REZ ran 39% on product launches, BABY surged after a proposal on product expansion. Beyond the price charts, the best find is a DEX with $17.6M in TVL and $1.5B in weekly volume.

Find and execute the 15%+ stablecoin yields in minutes
Save time without checking every protocol manually. DeFi Saver’s Discover page surfaces rates across Aave, Morpho, Spark, and more, lets you simulate leverage before committing, and handles the full loop in one click. Stop leaving yield on the table.
<Discover Yields on DeFi Saver> | Today in DeFi is Supported by DeFi Saver
Macro Brief:
Rates and the dollar:
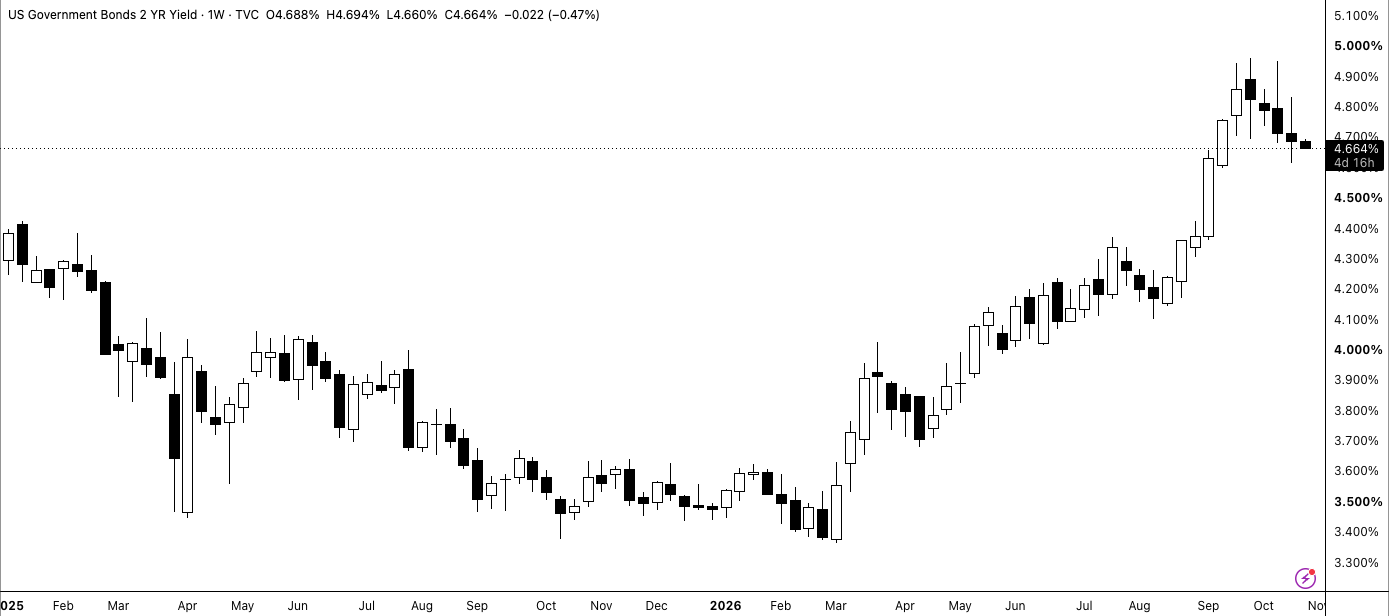
The 2-year yield, the market’s read on where the Fed rate is heading, fell to about 4.69%, and the 10-year slipped to 4.99%. Almost all of that came on Thursday, when a tech selloff sent money into Treasuries. The Fed’s rate is 3.75–4.00% after September’s hike. It decides on Wednesday (Oct 28), and CME FedWatch prices in a hike at only about 7%. The market prices in a December hike at about 78%.
Crypto vs stocks:
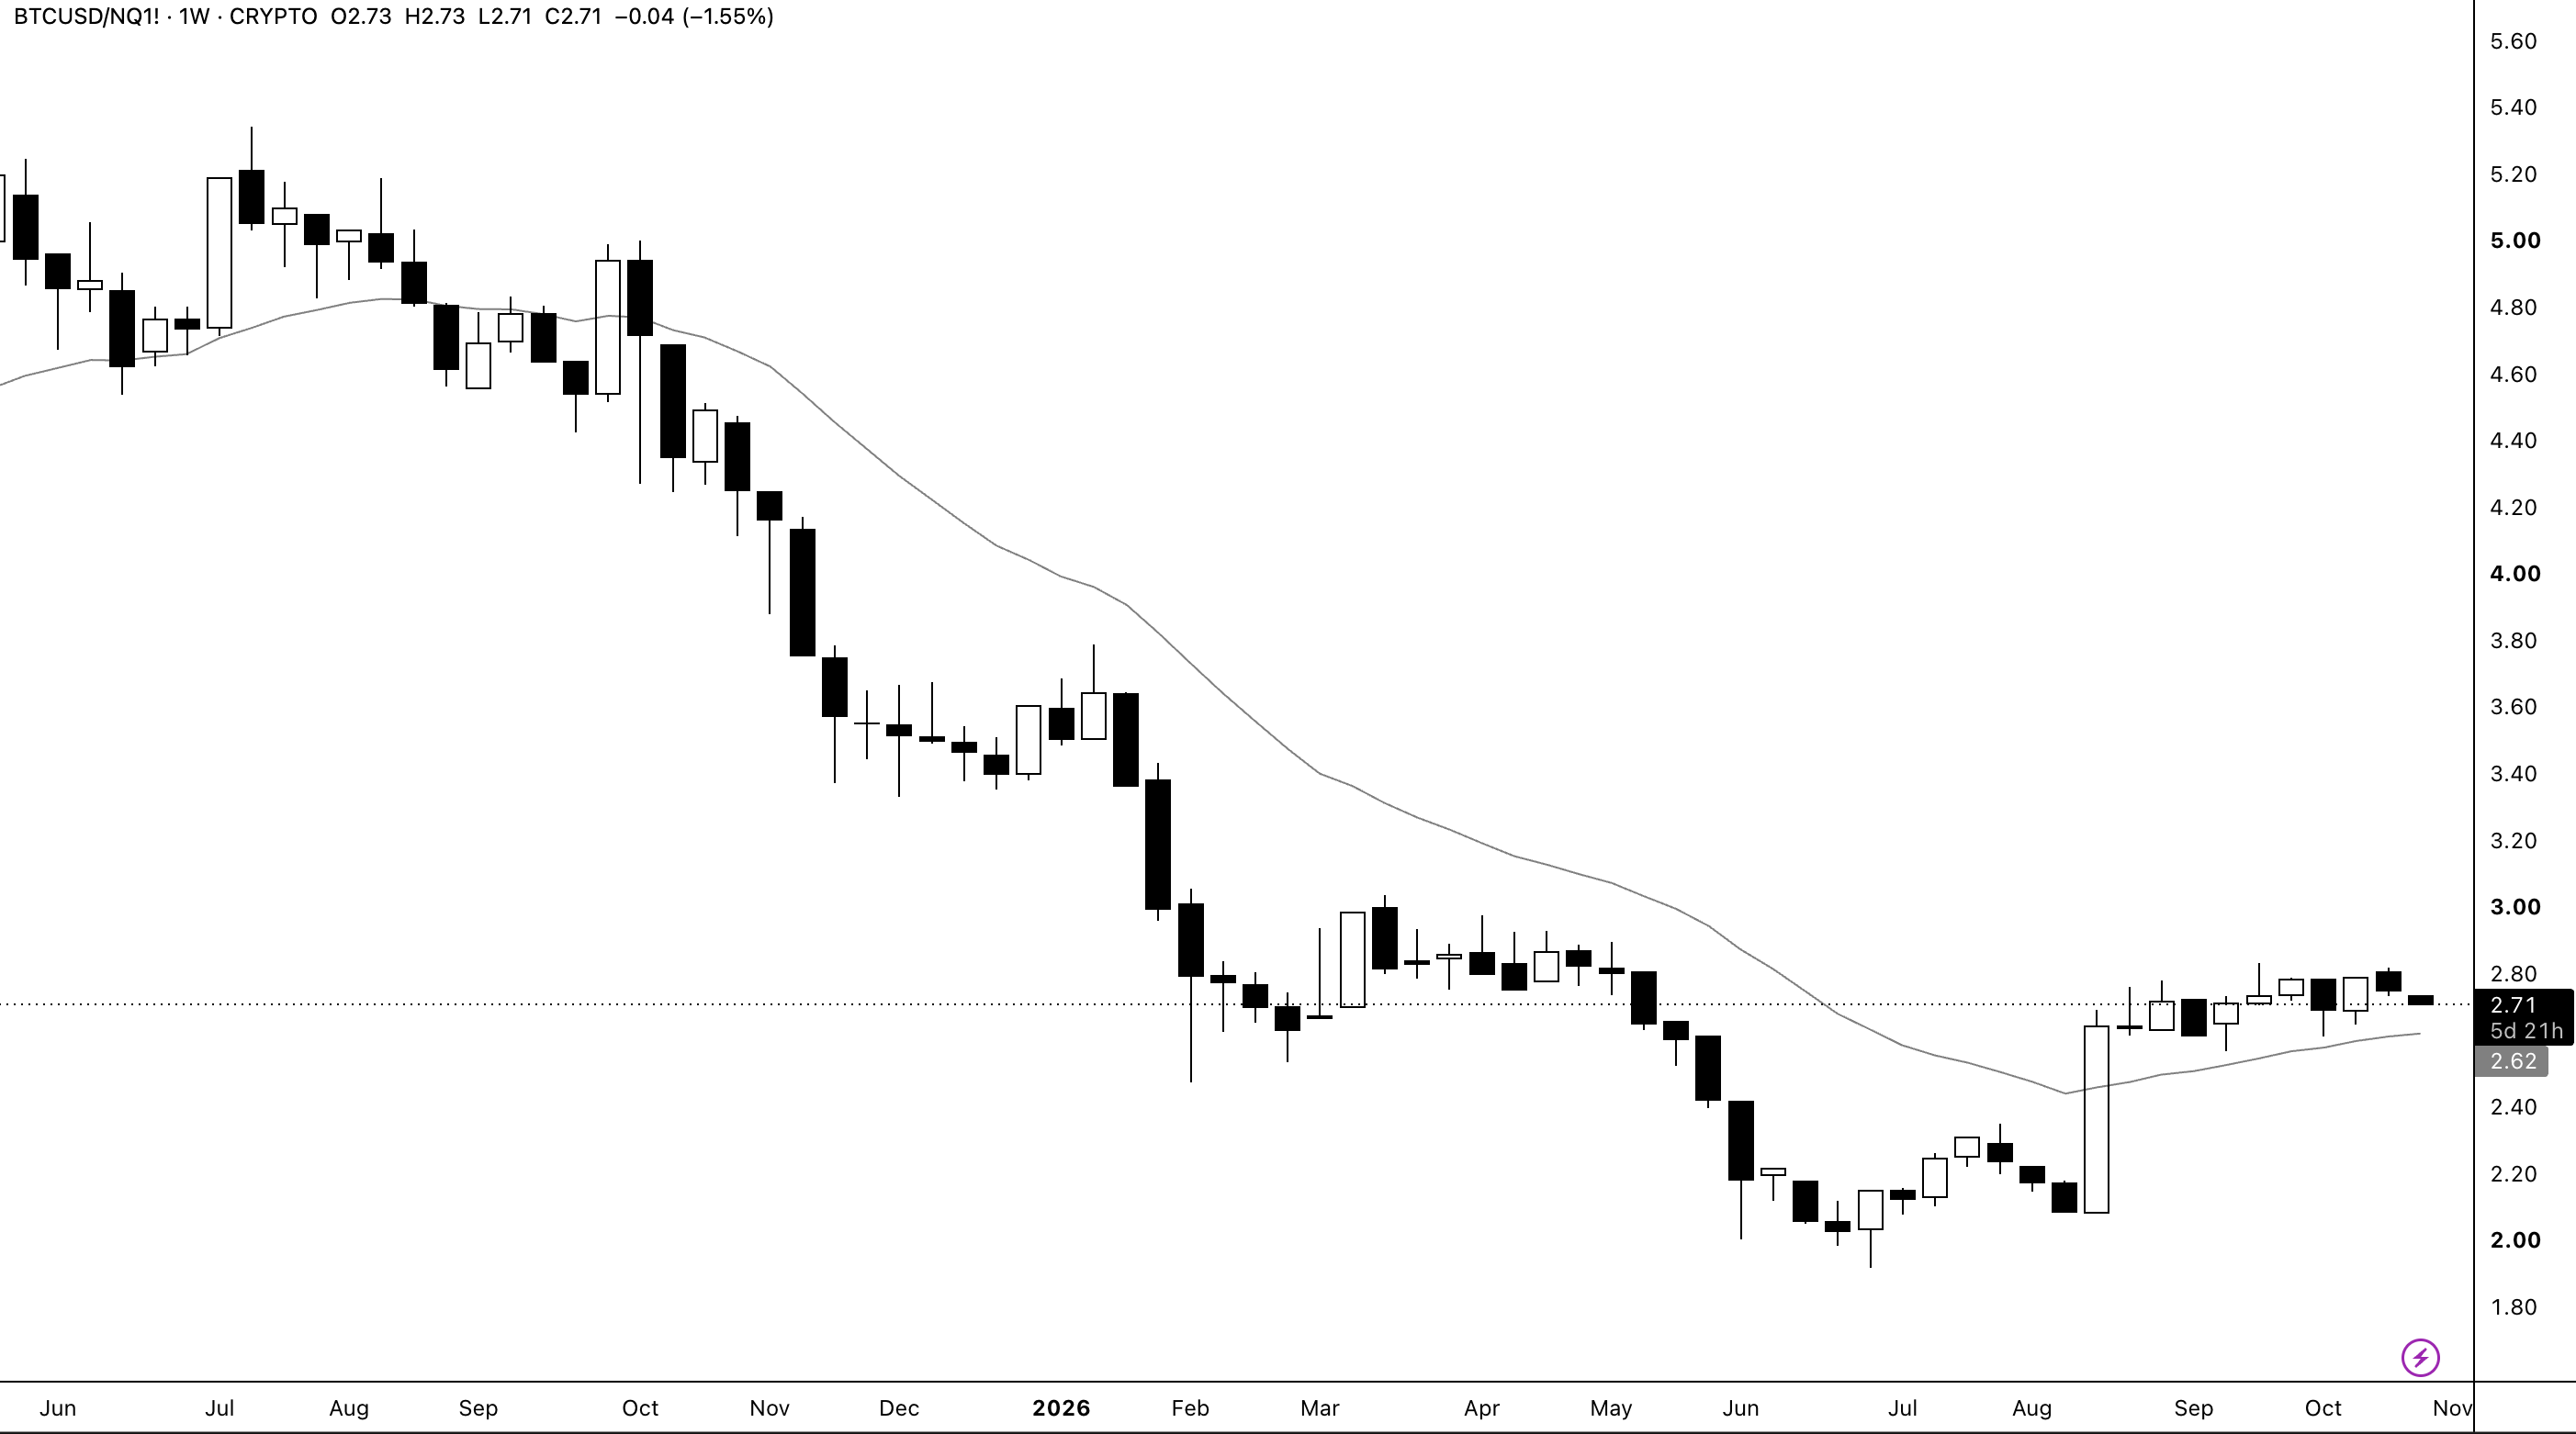
The S&P 500 fell 0.5%, and the Nasdaq Composite fell 0.7%, a second weekly loss. Thursday’s trigger was worry about how AI buildouts are financed, with Meta down about 7% and chip stocks down about 6.7%.
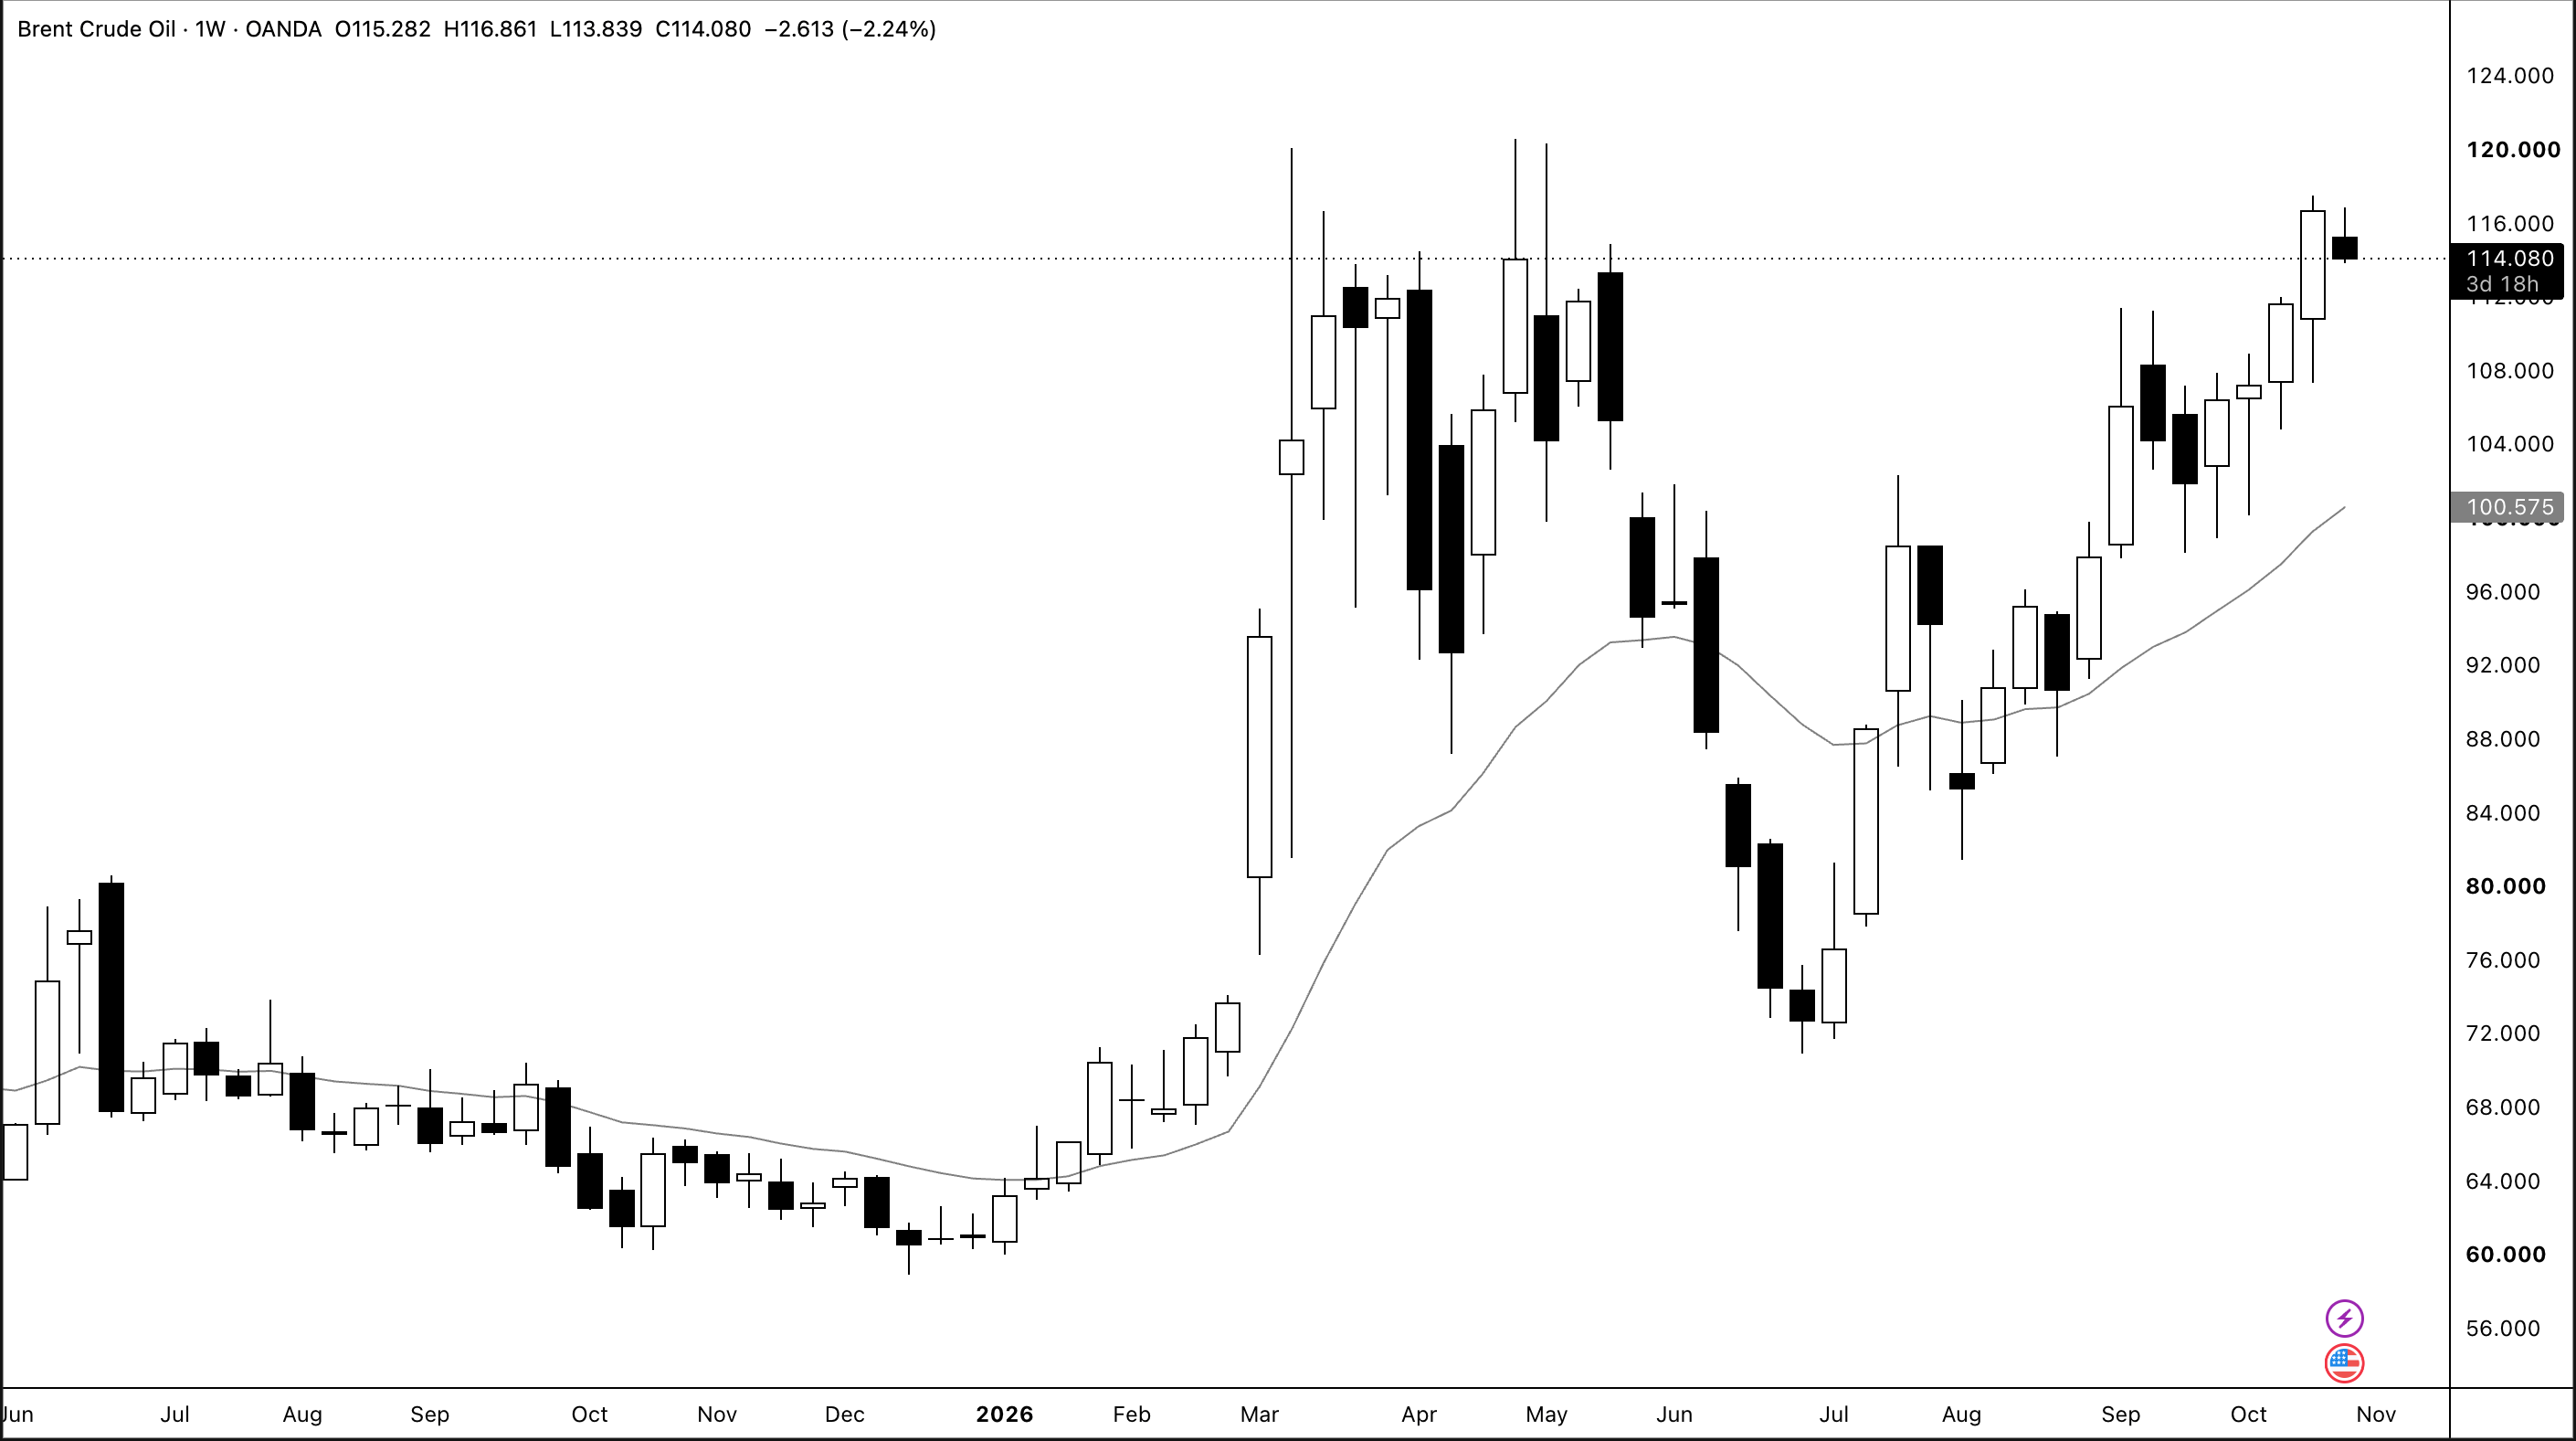
Brent oil rose about 6% to roughly $117 on Middle East escalation. Bitcoin fell 2.4% to about $80K, and Ether fell 3.4%, so BTC/NQ slipped 1.5% after the prior week’s 3.7% gain.
Crypto Capital On-Ramp
Total stablecoin supply 7d change (level + WoW)
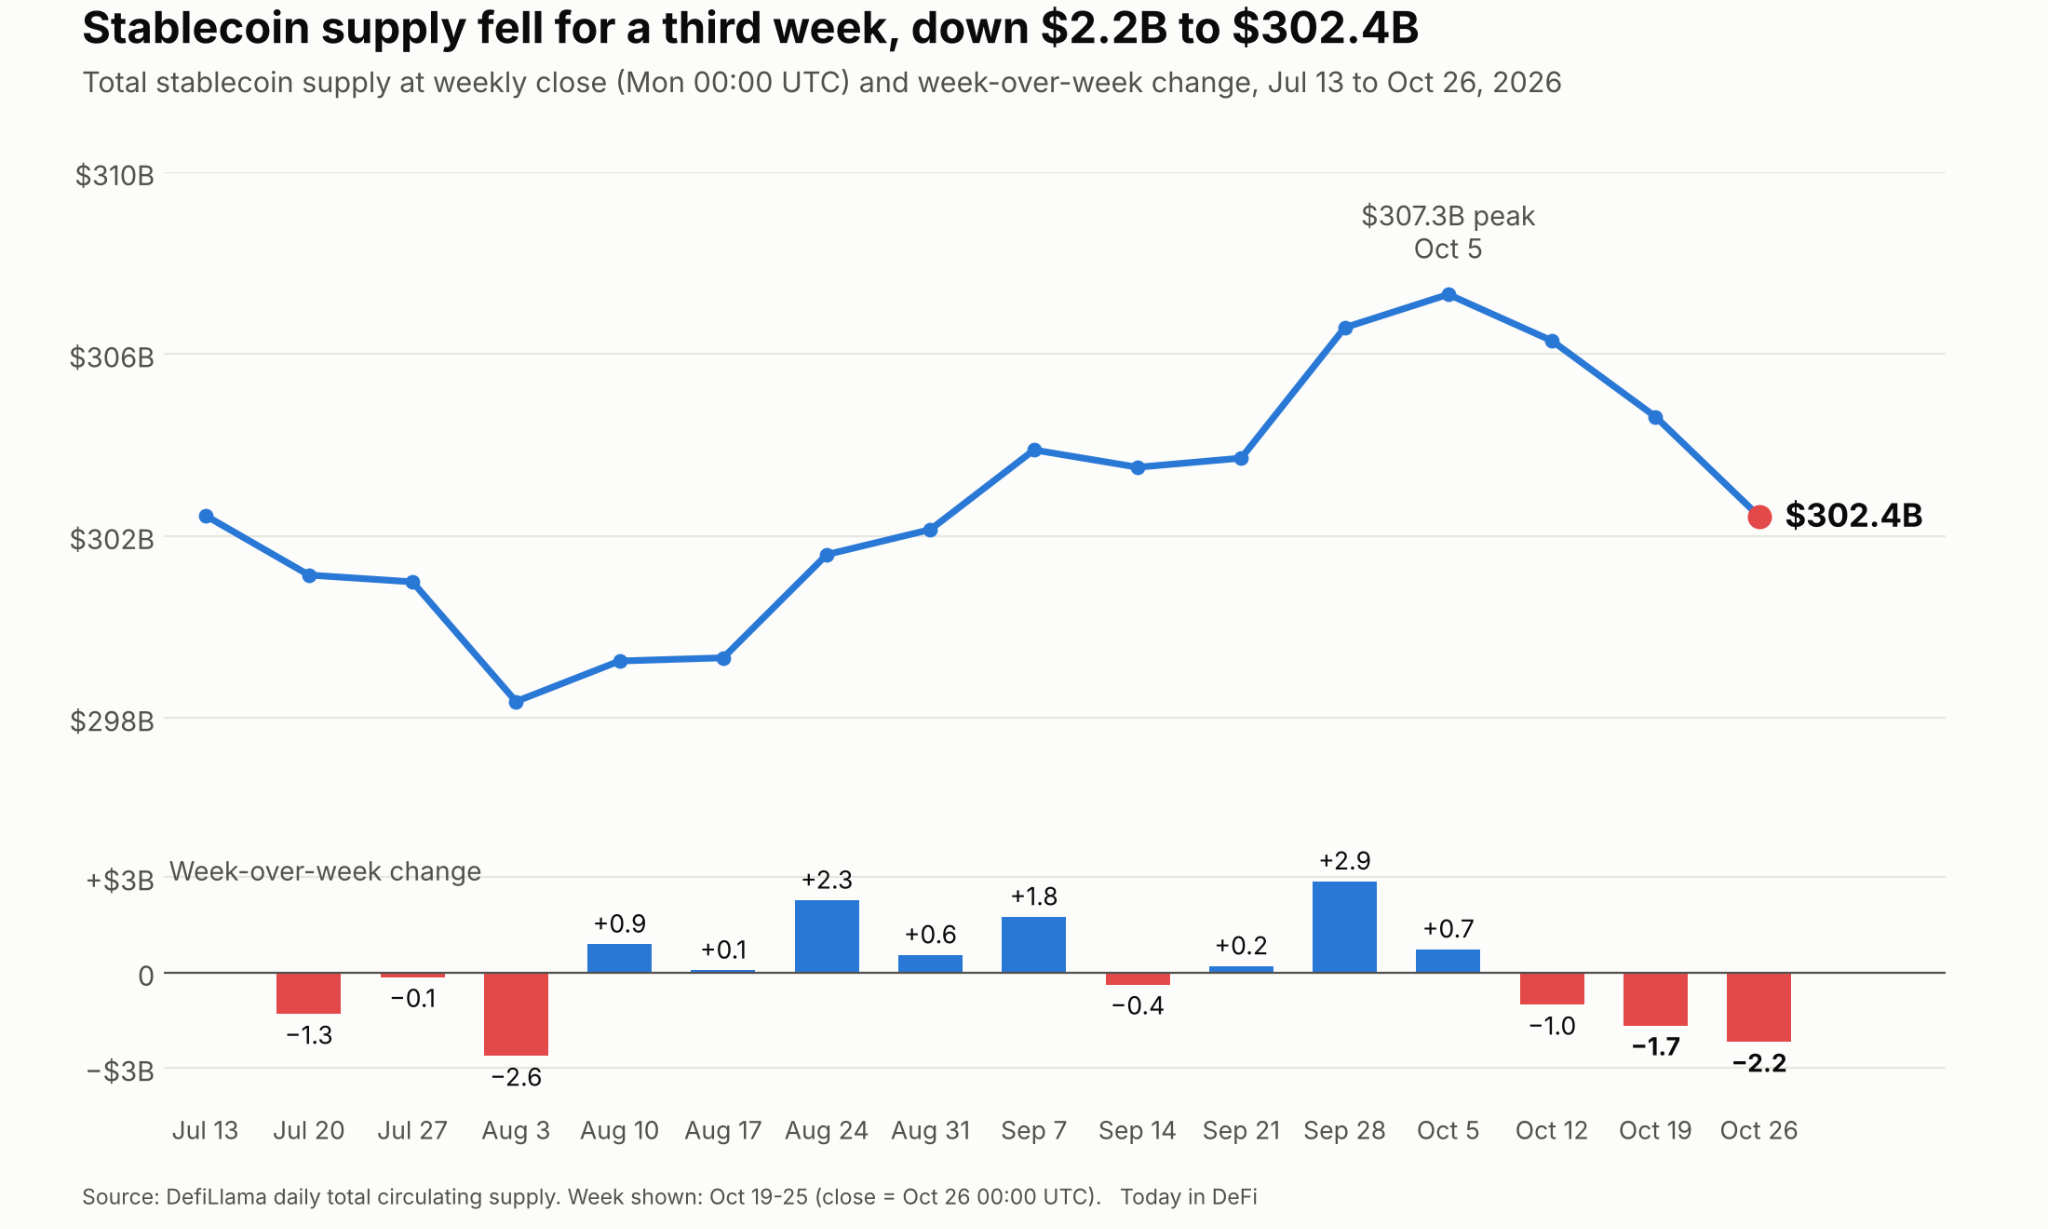
Total stablecoin supply fell $2.2B (−0.7%) to $302.4B, the third straight weekly drop. USDT (−$1.1B) and USDC (−$0.9B), the two coins that best show new trading cash, account for about 91% of the weekly drop. CHECK: your draft said supply is “down 4.9B” since Oct 5 and also “91% of the drop”. $2.0B is 91% of the $2.2B weekly drop, but only 41% of $4.9B. I used the weekly figure.
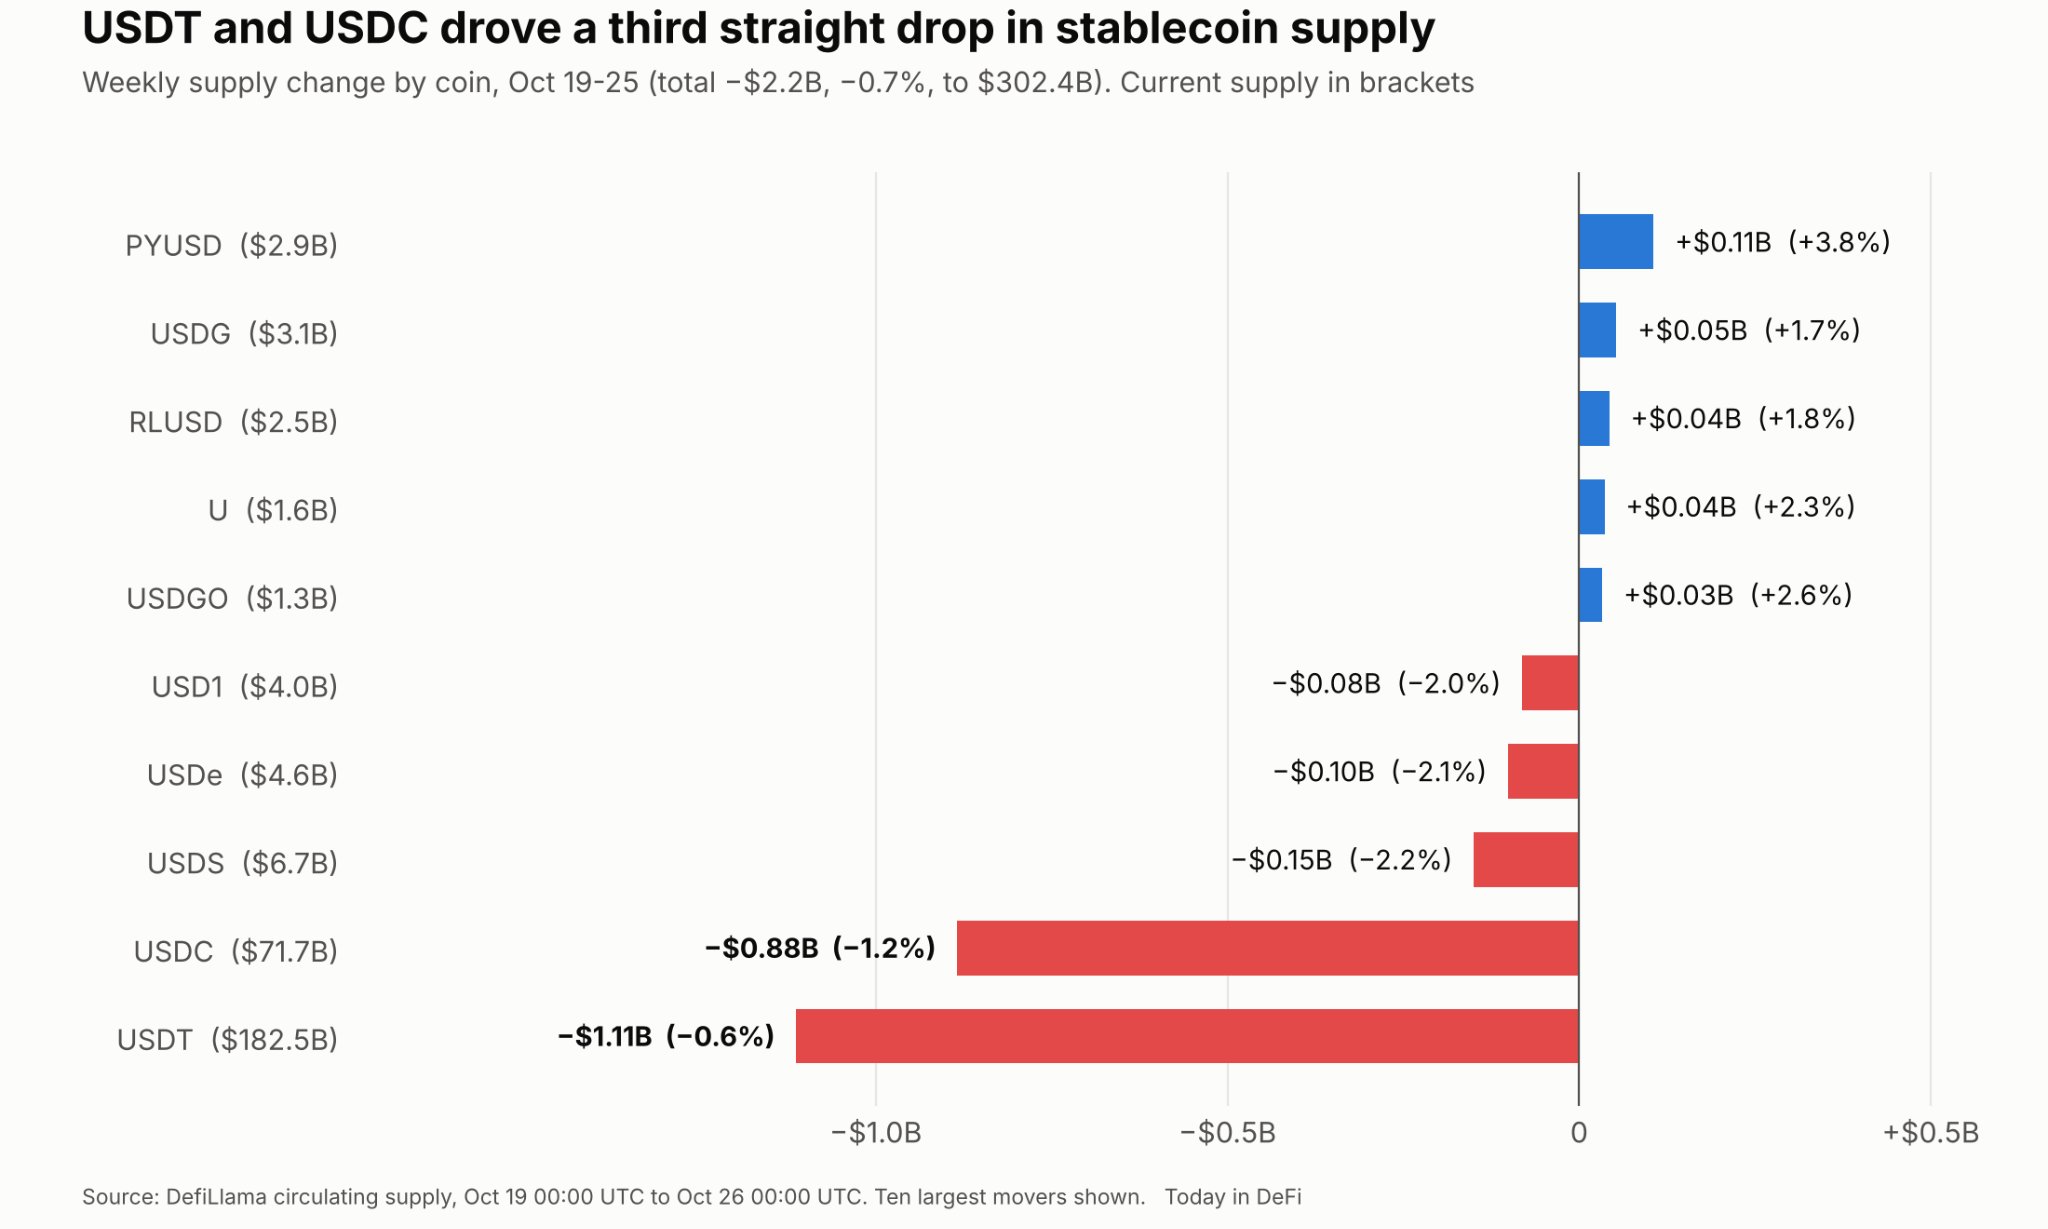
Yield-bearing stablecoins also dropped: USDS (−2.2%), USDe (−2.1%), and USD1 (−2.0%), though the dollar amounts were small. The signal is mixed and less obvious than last week’s, when risk-averse stablecoins gained, and trading-capital stablecoins lost. Two of the few that grew are used for yield farming: PYUSD (+3.8%) and USDG (+1.7%), but they didn't offset the losses.
ETF flows
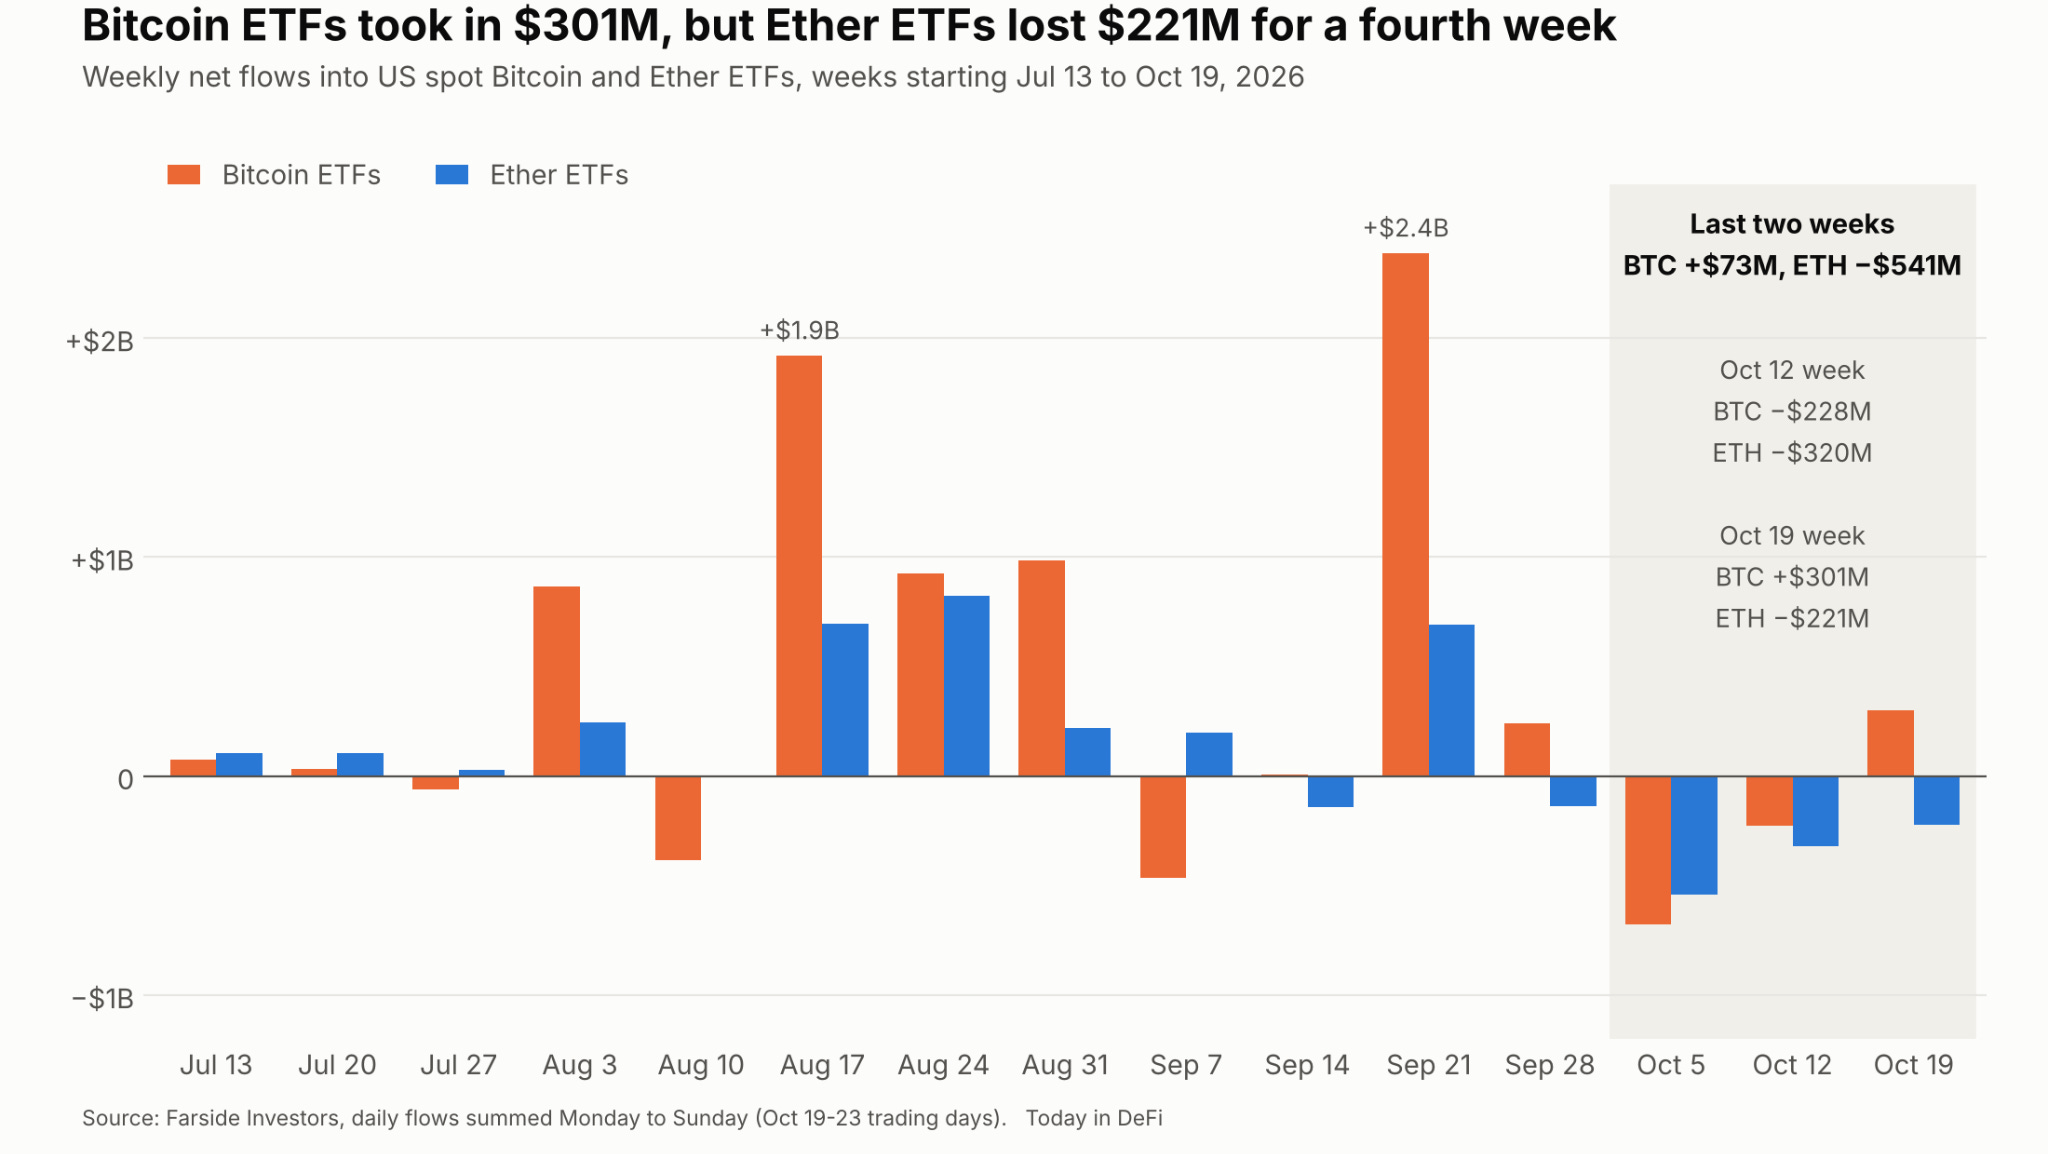
Spot ETFs split. Bitcoin funds took in $301M, their first inflow in three weeks, after −$228M last week. Two days carried it: Monday (+$527M) and Wednesday (+$525M). Thursday’s tech selloff reversed much of that with −$636M. Ether funds lost $221M, the fourth straight weekly outflow, for a total of −$ 1.2 B.
Week-Ahead Catalysts
Wed, Oct 28, 2:00 PM: Fed decision. Hold at 3.75–4.00% expected. The Warsh press conference at 2:30 PM matters most. Fed calendar
Wed, Oct 28: PancakeSwap “Flip” snapshot vote. Source
Thu, Oct 29, 8:30 AM: Q3 GDP and September PCE. GDP is expected at 3.0% (prior 2.2%). PCE is expected at 3.6% y/y headline and 3.1% core (prior 3.4% and 3.0%). A hot print makes a December hike easier.
Thu, Oct 29: Falcon (FF) unlock, 11:52 and 20:58 UTC. About $21M, 6% of circulating supply. A scheduled release, not a confirmed sale. Source
Thu, Oct 29, after the close: Strategy and Coinbase earnings, both confirmed. Watch Strategy’s bitcoin holdings. Coinbase, Strategy
Fri, Oct 30: Kamino (KMNO) unlock. About $9.6M, 3.9% of supply, to Core Contributors. The time isn’t published. Tokenomist
Sun, Nov 1: SUI (~12M) and EIGEN (~7M) unlocks. CHECK: units (tokens or dollars) were lost when you pasted. SUI, EIGEN
Onchain Risk Regime
Aave / Sphere Rates
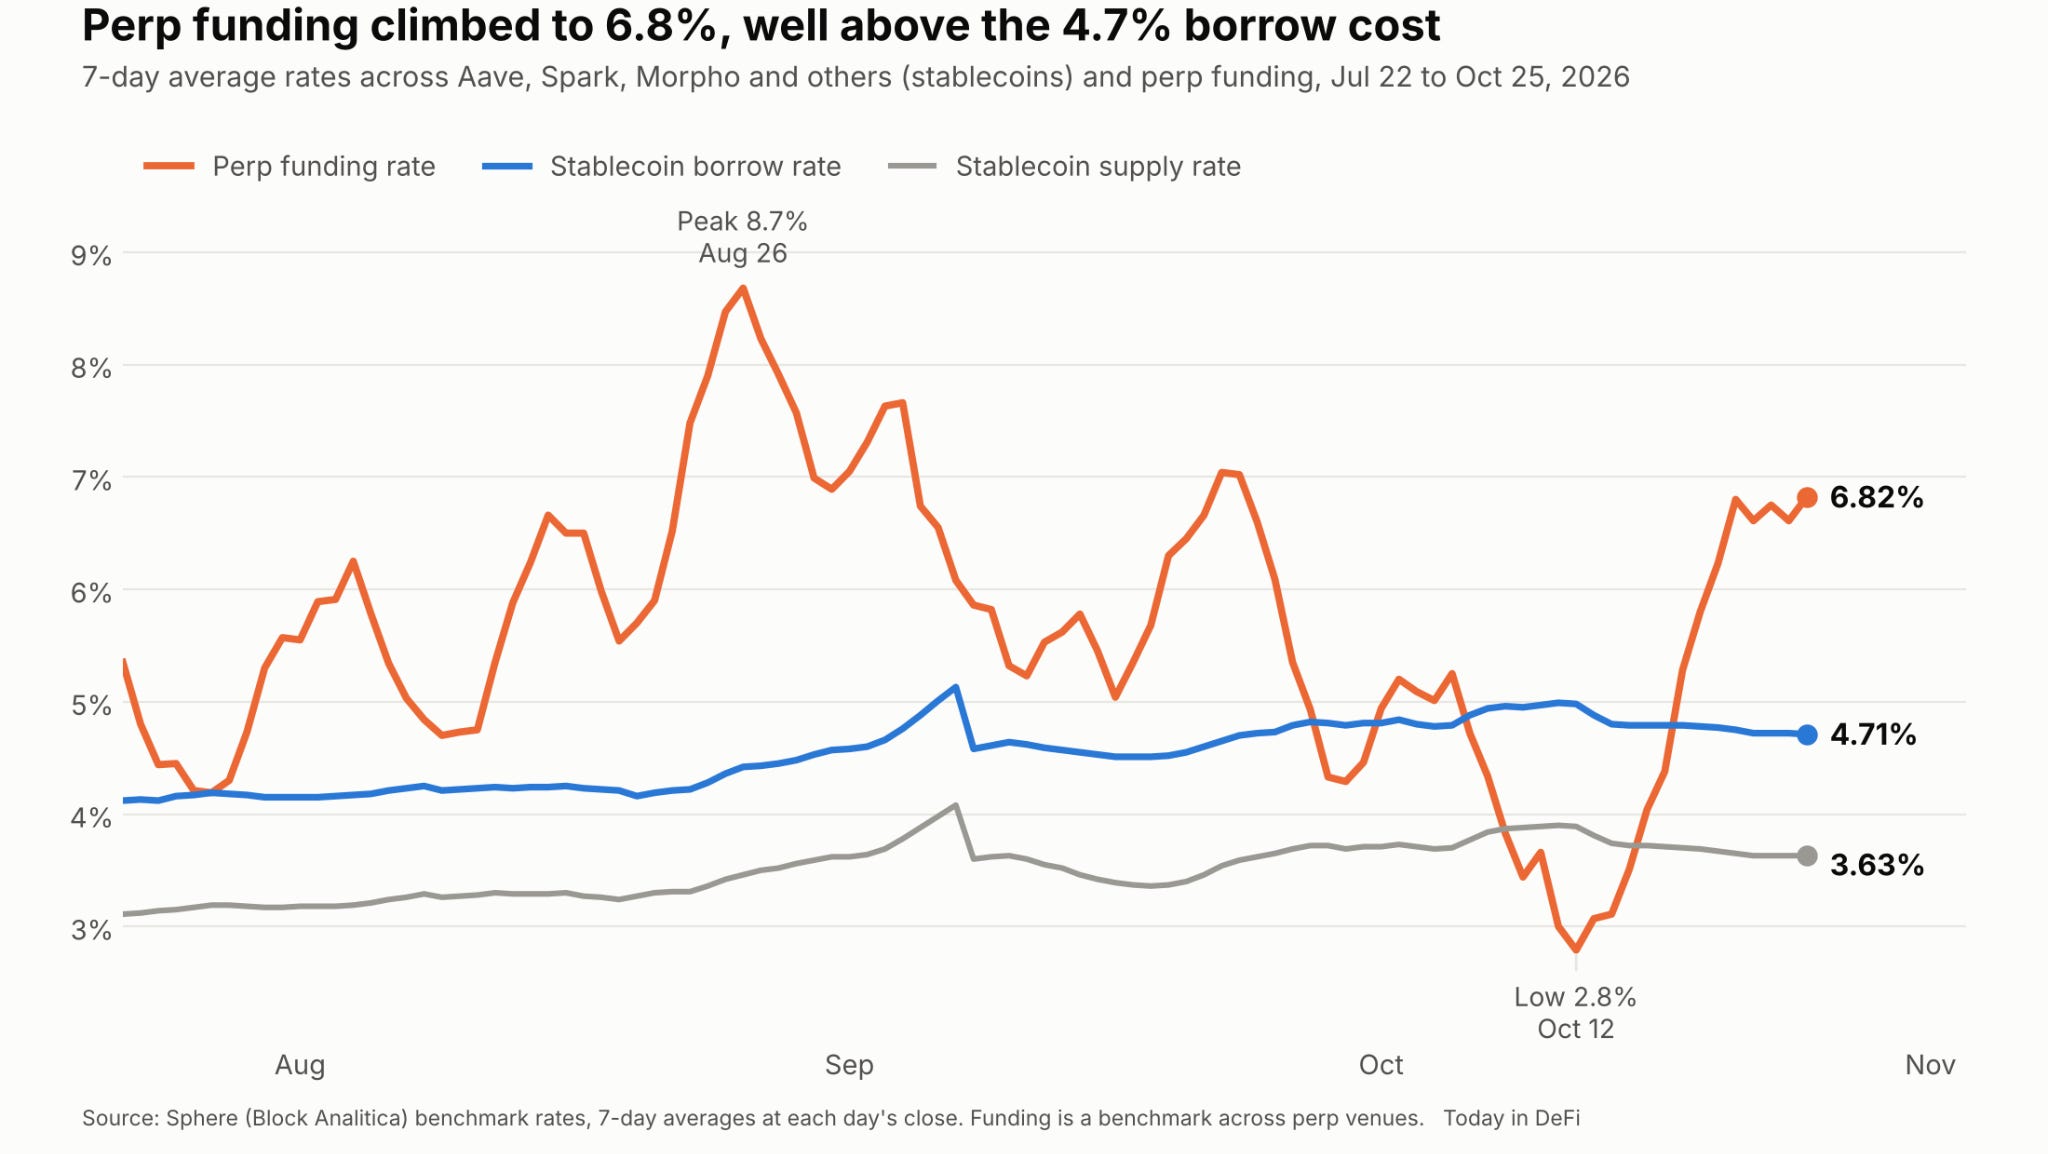
Borrowing cost barely moved, but the cost of holding leveraged longs jumped. The perpetual-futures funding rate (the fee leveraged traders pay to hold perp positions) rose to 6.8% annualized, from 5.3% a week earlier and above its 30-day average of 5.0%. Stablecoin borrow rates across lending markets slipped to 4.7% (4.8% prior), and supply rates fell to 3.6% (3.7% prior). Funding now sits 2.1 points above borrow cost, so leverage is building even as prices fall.
ETHBTC vs 20W MA
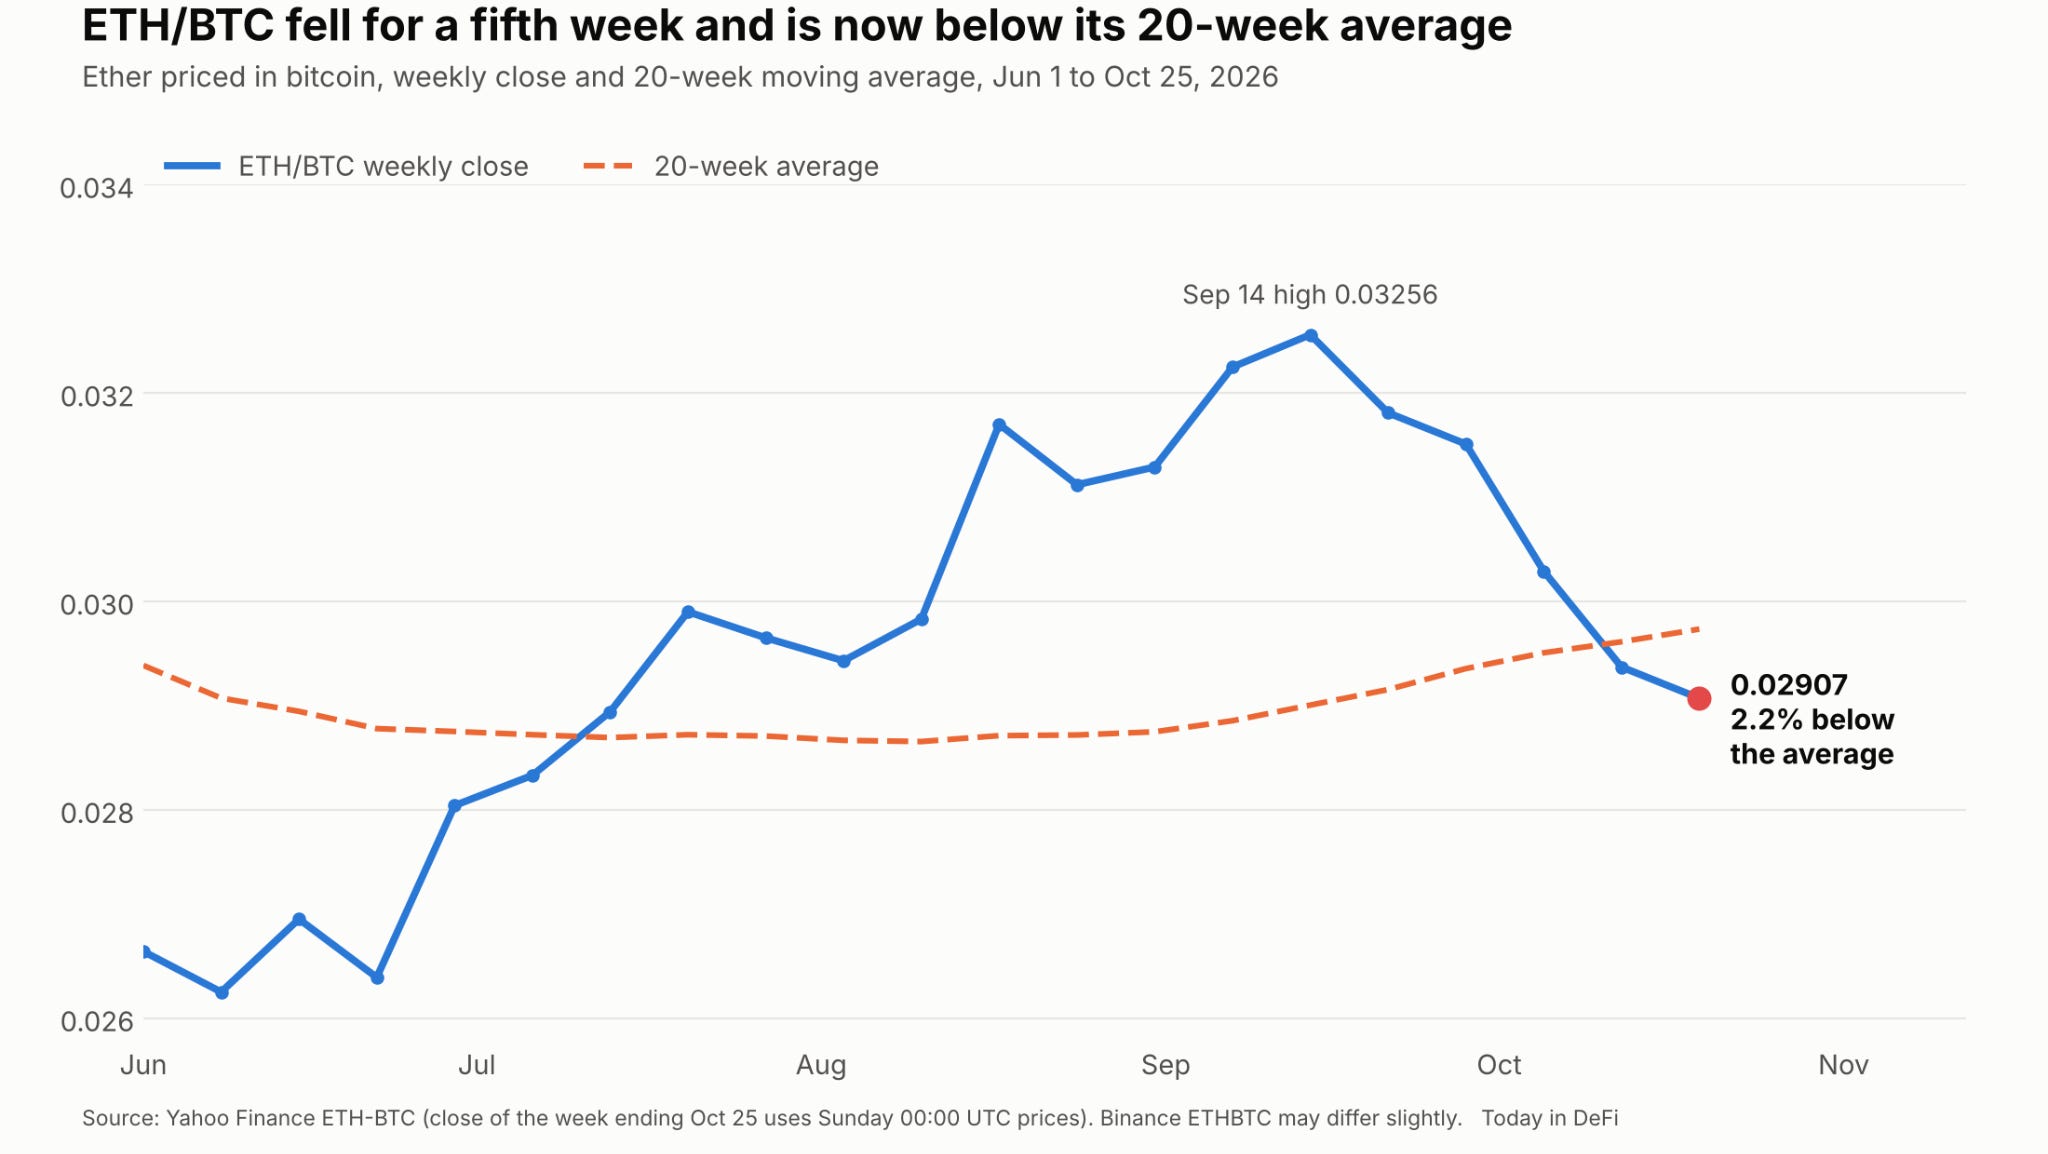
ETH continues to underperform Bitcoin for the 5th straight week. Historically not a good sign since most altcoins are trailing ETH’s movement
Verdict: Onchain regime is risk-off and not improving. Falling stablecoin supply and rising funding point the same way.
Section 3 — Chain Comparison
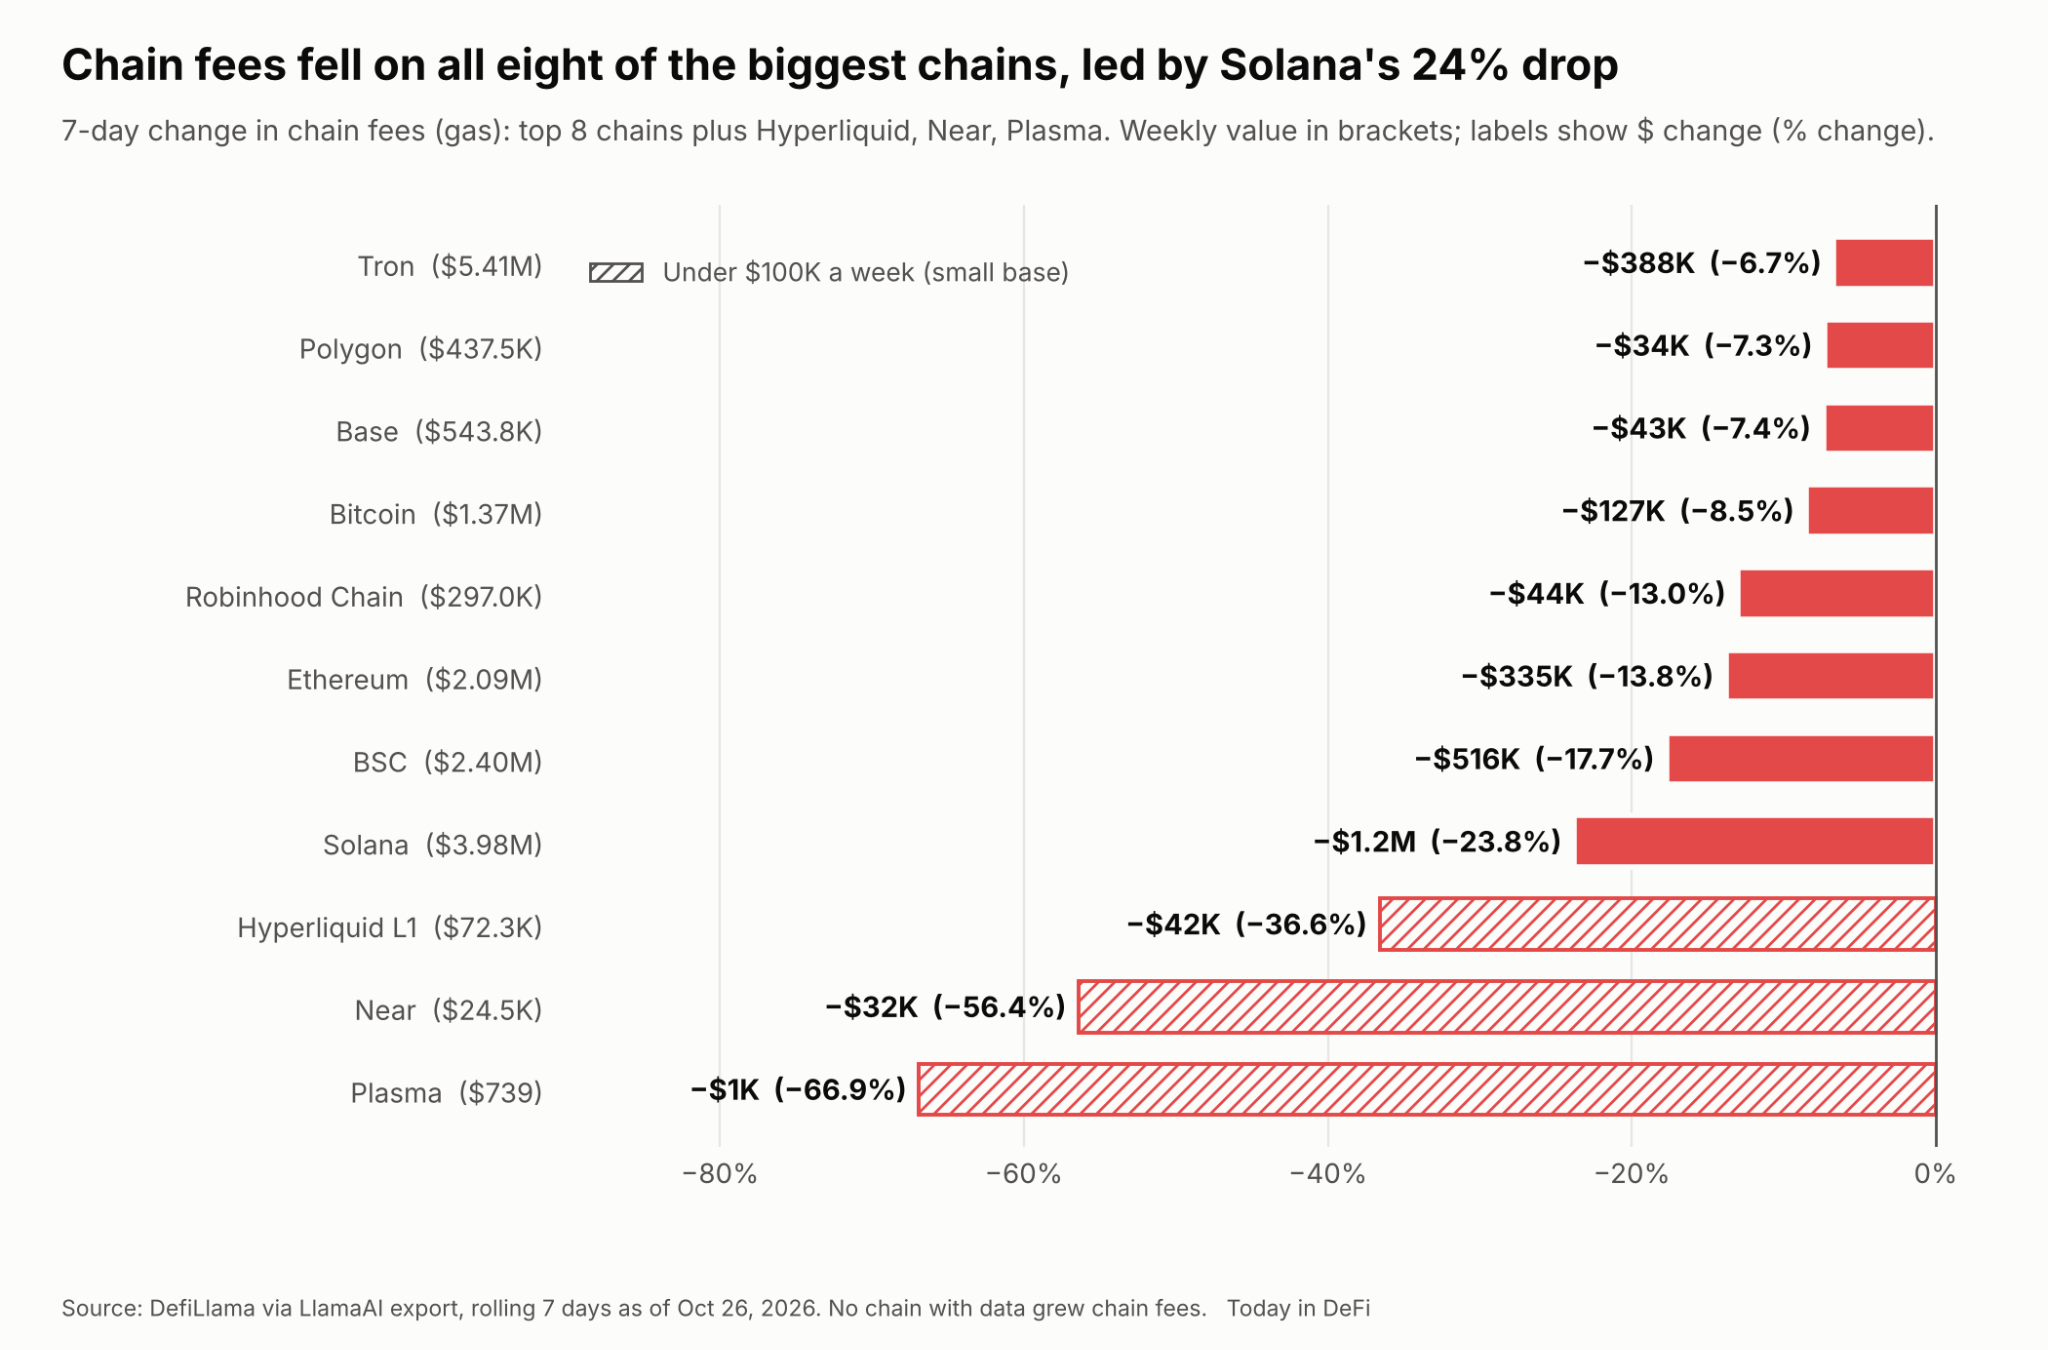
DEX volume across the 19 chains I tracked fell 12.9% to $44.7B, down about $6.6B, with 16 of 19 chains lower. Chain fees (gas) fell on every chain with data, so usage is clearly weaker, and app fees were mixed, with six of the eight biggest chains down. The chains that rose are worth a closer look, mostly for the projects behind them.
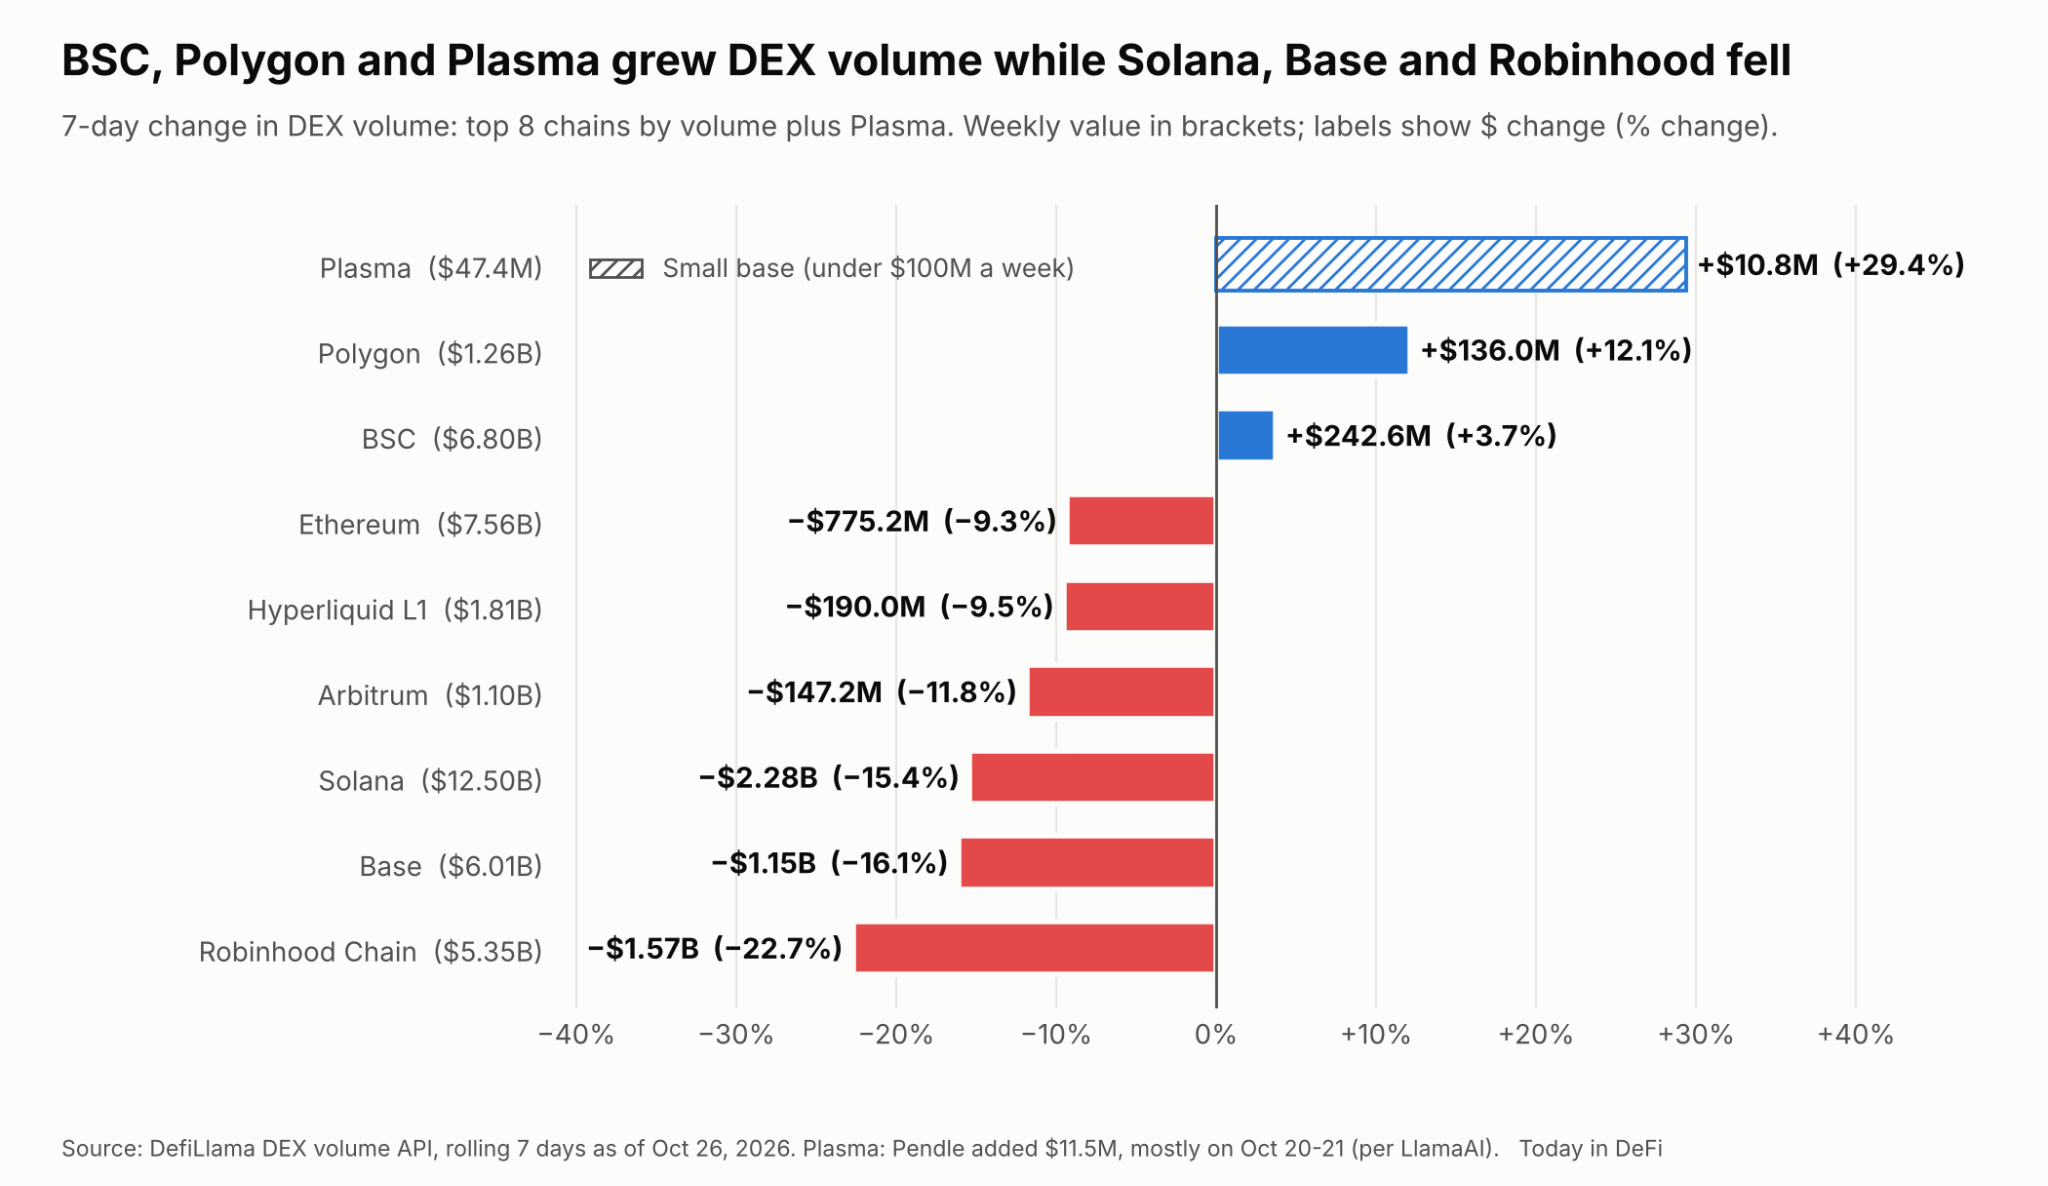
Plasma, DEX volume +28.6% to $47.4M: a move into stablecoin yield.
Pendle (+$11.45M), Curve (+$3.05M) and Fluid (+$3.59M) all peaked on Oct 22, the day of the market-wide selloff. What these have in common on Plasma is that they are mostly stablecoin products.
Pendle’s markets on Plasma are mostly stablecoin yields, and Curve on Plasma is known for stablecoin pairs (USDT0 against USDe, sUSDe, USDai, USDO and syrupUSDT), not token trading.
So this volume reads as people rotating into stablecoin yields during the selloff, a risk-averse move, not speculation.
Polygon, DEX volume +12.2% to about $1.27B: mostly Polymarket.
About $106M of the rise is Polymarket, measured by payouts to winners, not trading volume. Sports make up about 55% of its recent volume, and midterm markets are building toward November.
This week adds big macro events: the Fed decision on Wednesday and Q3 GDP and PCE on Thursday. Traders tend to pile into bets like these, so expect Polymarket activity to stay high. Without Polymarket, Polygon is +6%.
The project to know: Metric

Metric (+$61.7M) is a “propAMM” for bStocks (Binance-issued tokenized stocks). It prices around an external reference price rather than pool balances. Its public DEX launched on BNB Chain on Oct 14.
Volume mostly comes through aggregators: Delphi reported 61% of bStocks volume over the month to Sep 16 routed through Binance Wallet, with a large share through one wallet. DefiLlama shows Metric at only $17.6M TVL against $1.5B of weekly volume, roughly 86 times turnover.
Another mechanism to watch: Aethir (on Arbitrum)
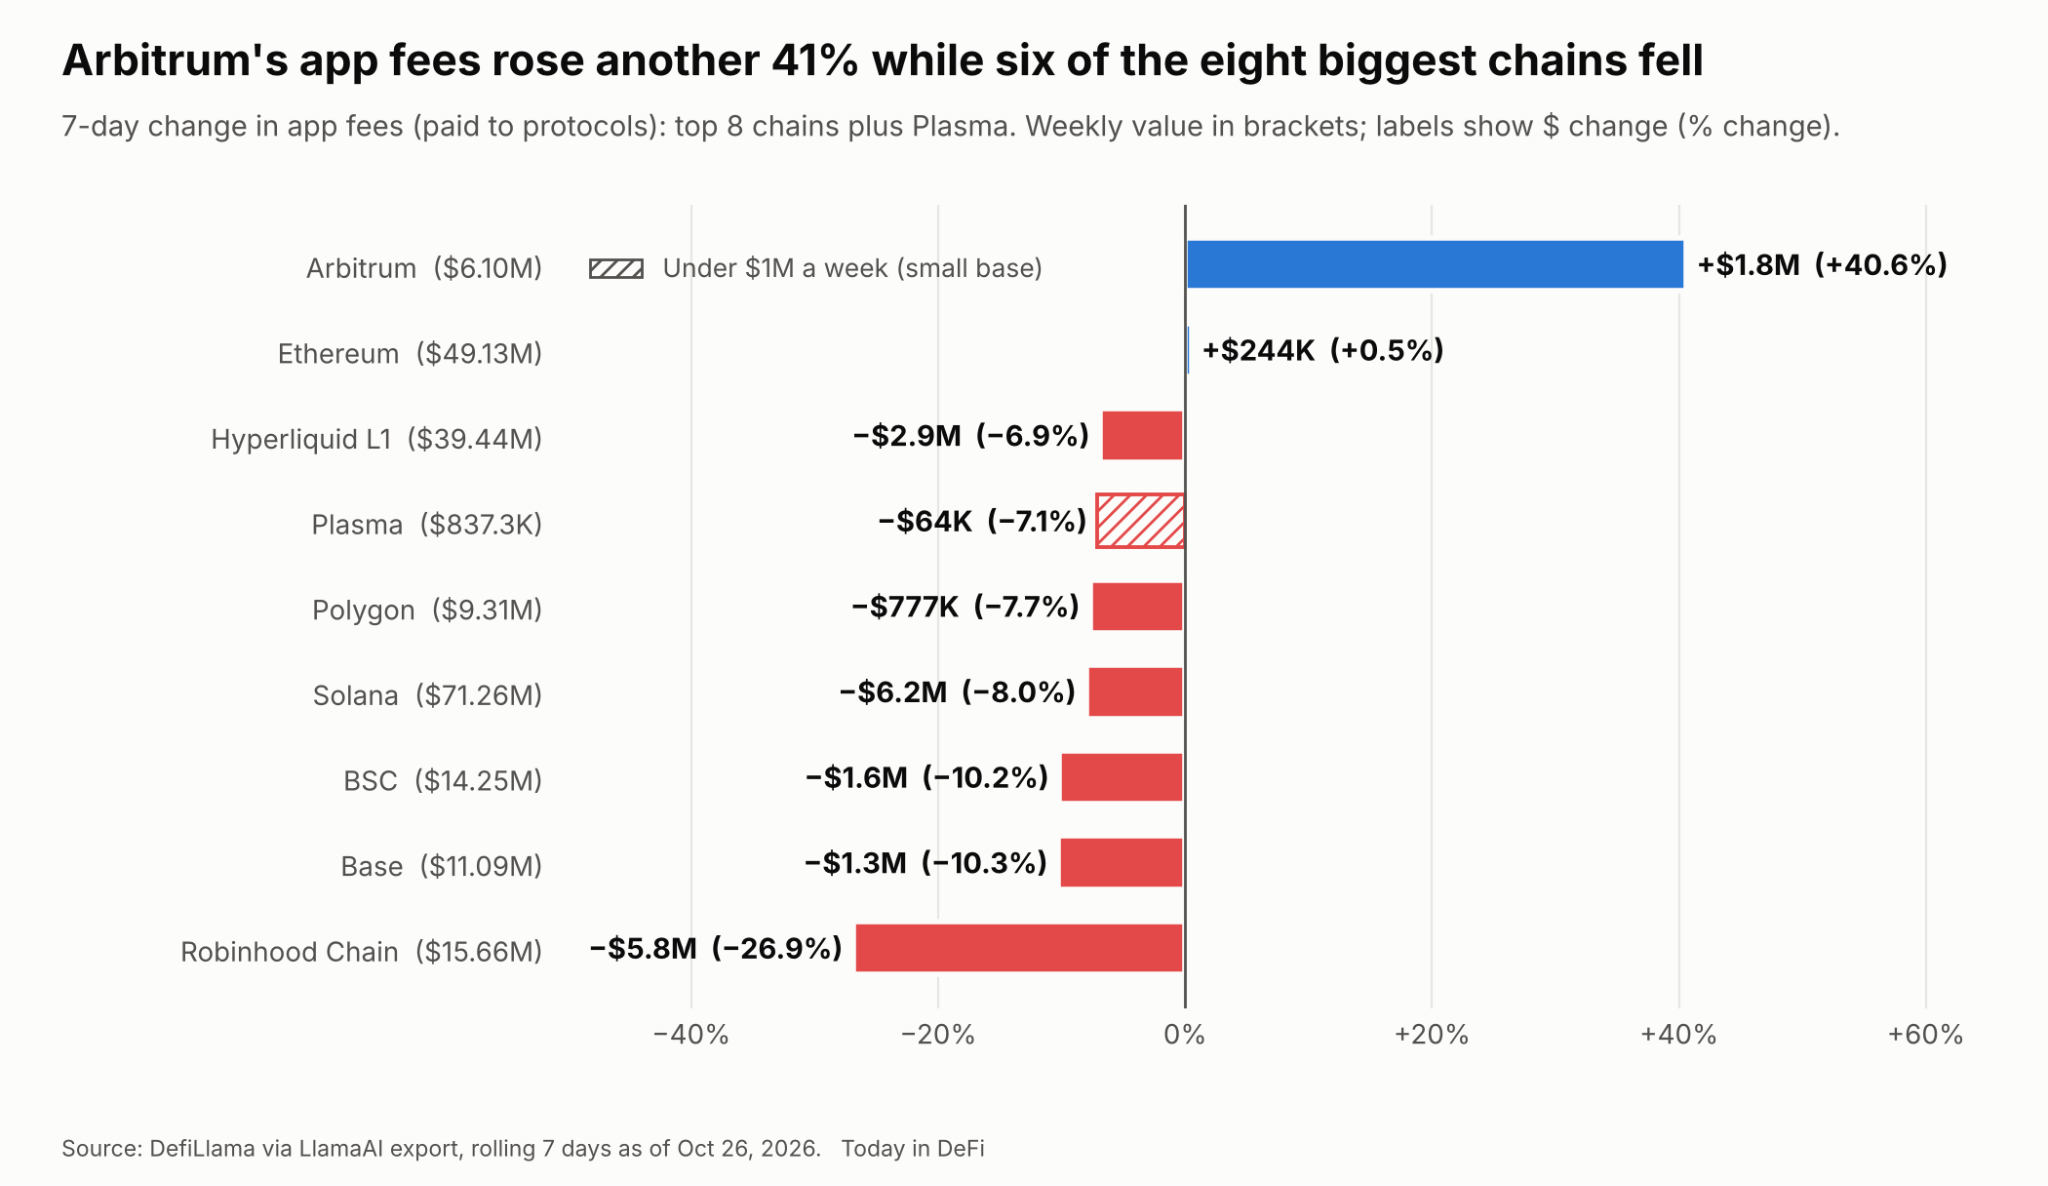
Arbitrum’s app fees went up, and Aethir is one of the protocols behind it. Aethir is a decentralized GPU cloud where customers rent compute from independent hosts, so its fees come from real customers paying for capacity, not from token incentives.
On Oct 21 Aethir announced daily ATH burns funded by network fees, plus a floating fee that falls when the market weakens and can drop to zero. Burns start in November, so the new mechanism can’t explain the Oct 23 spike. Under the new model, payments like these will fund the burns, so track those monthly lumps from November.
Section 4 — Project & Protocol Discovery
4A. Token Price Movers - Observations, not trade ideas.
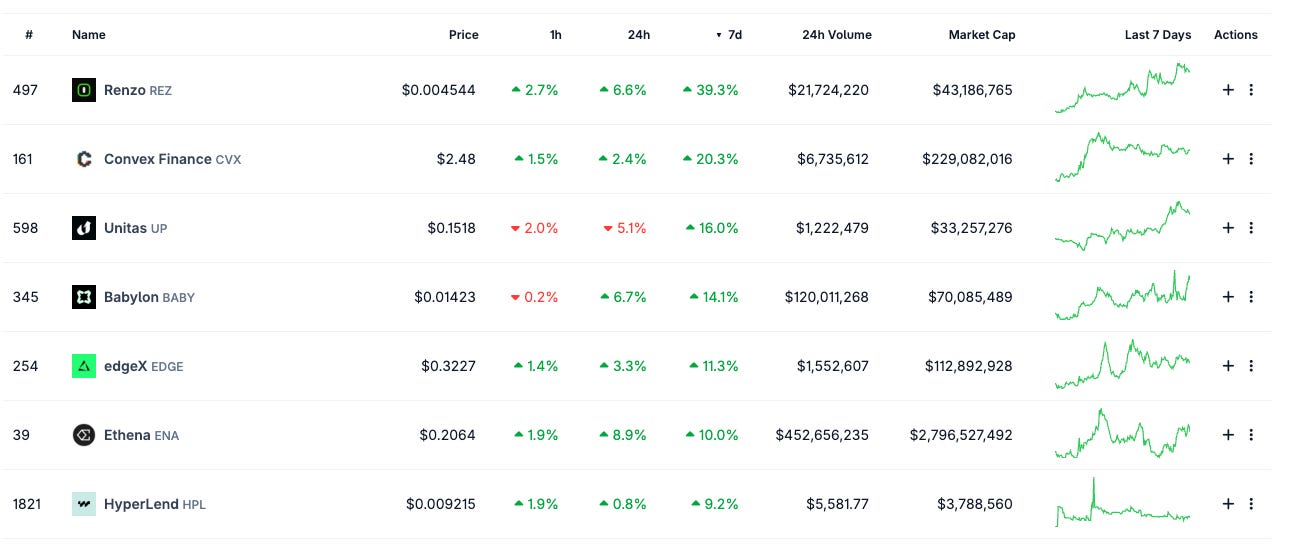
REZ, +39%: real launches, weak numbers. Renzo Finance shipped three updates for its Basis product (automated yield trades): Hyperliquid and Lighter support (Oct 22), Portfolio Margin (Oct 23), and a teaser for a new “high-yield asset category” (Oct 21).
CVX, +20%: real catalyst, an airdrop. Convex told vlCVX holders (people who lock CVX to vote) on Oct 20 that they qualify for Monolith’s swanUSD launch airdrop: 100,000 SWAN (1% of supply), shared equally among eligible wallets. Monolith launched swanUSD on Oct 22, and Convex confirmed the airdrop live on Oct 23.
ENA, +10%: distribution news plus a rising yield. Ethena put USDe on X Layer and in OKX Wallet on Oct 23, starting with an Aave v3 instance, with one-click looping coming soon. Funding rose to 6.82% from 5.28% (Sphere), and fees rose 5.5% to $4.4M, improving sUSDe’s yield.
BABY, +14%: a live proposal, not a launch. Babylon Labs proposed on Oct 18 that Aave V4 accept native Bitcoin as collateral. It is not approved yet, and I only have single-source confirmation that it passed a temperature check.