
Subscribe for daily free DeFi news covering launches, tradable catalysts, and actionable farming opportunities.
Today’s News Headlines:
Trueo migrates from Base to Ethereum mainnet
FomoPeek iOS app stole keys, delete if installed
Shadow Exchange teases V2 launch on Sonic
Kamino launches Fixed Rates on Solana with Hastra
Key Takeaways:
Crypto shrugged off a genuinely bad week.
The Fed hiked 25bp to 3.75–4.00%. Warsh’s hawkish forecast sent the S&P to six-week lows and the 10-year briefly above 5%. Add ETH’s first ETF outflow since July, and a 15% single-week BUIDL redemption, yet crypto has performed for several consecutive weeks now, absorbing hostile macro— not one lucky week.
The memecoin money re-levered into gold, oil, and a pre-IPO Anthropic perp.
Spot DEX volume fell across every chain that led August (Robinhood -22.5%, BSC -30.2%, Solana -7.9%, Base -8.1%) while perp volume grew on all four — and the new pairs are increasingly equity, index, and commodity underlyings rather than tokens. Full breakdown below.
Ethena’s rally has three supporting threads, not one.
ENA is up 52%, coinciding with continued USDe growth, a recovery in funding rates that supports higher protocol fees and revenue, and the Ethena Pay beta launch earlier this month.

Find and execute the 15%+ stablecoin yields in minutes
Save time without checking every protocol manually. DeFi Saver’s Discover page surfaces rates across Aave, Morpho, Spark, and more, lets you simulate leverage before committing, and handles the full loop in one click. Stop leaving yield on the table.
<Discover Yields on DeFi Saver> | Today in DeFi is Supported by DeFi Saver
Macro Brief:
The Fed hiked rates for the first time in three years, and the dot plot signaled more hikes to come. 25bp, unanimous, to 3.75–4.00%. 16 of 19 FOMC members project at least one more hike this year.

The 10-year briefly touched 5.016%, its highest in over 19 years, and the S&P closed the week at six-week lows once Warsh’s press conference made clear the Fed isn’t done.
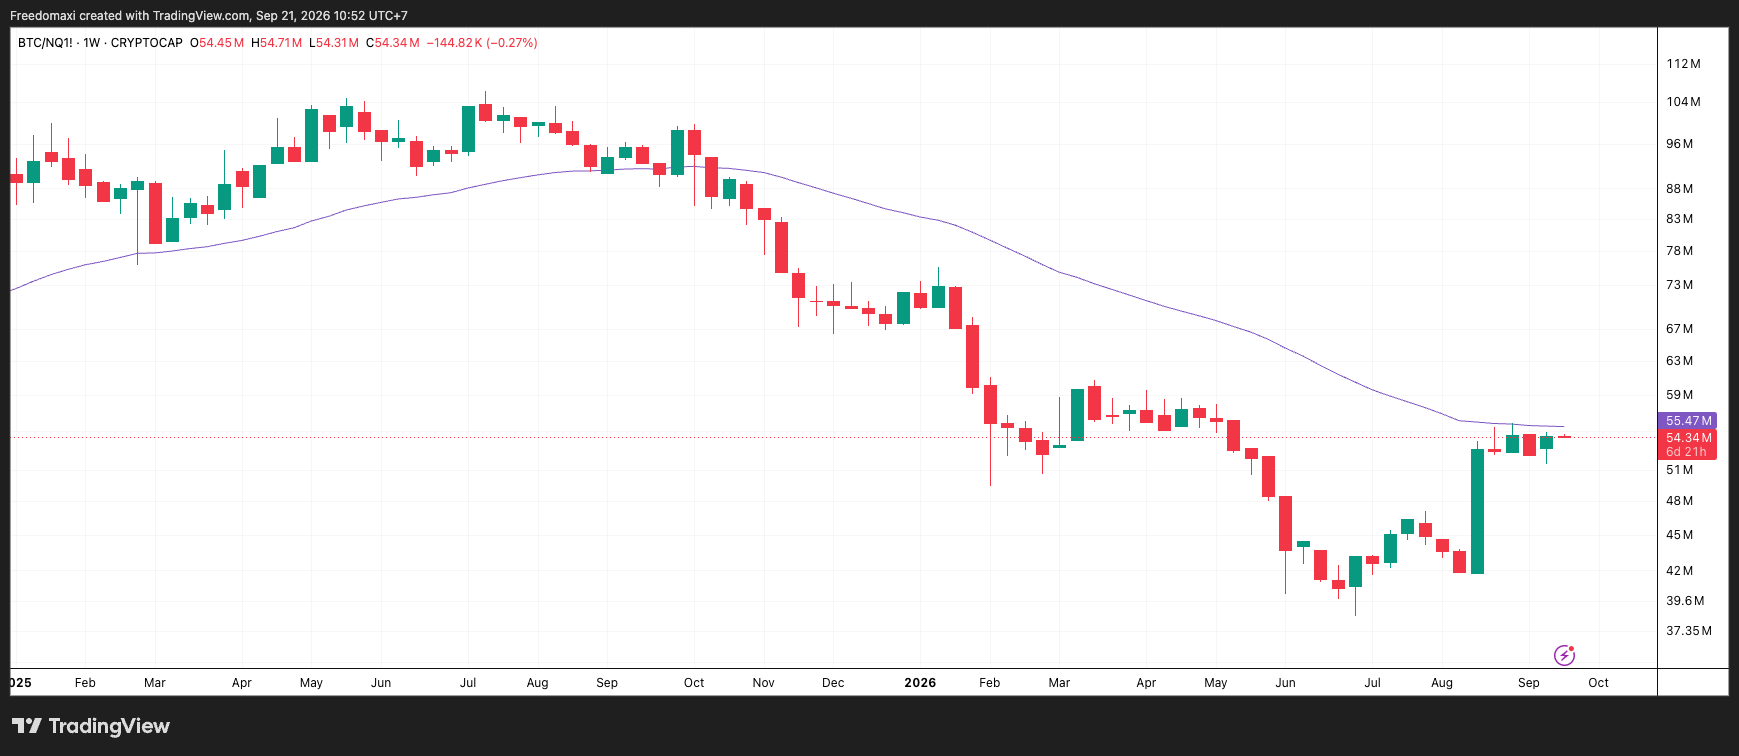
Crypto absorbed all of it and didn’t break. A real hike, a hawkish dot plot, ETH’s first ETF outflow since July, a 15% single-week BUIDL redemption — a genuine pile-up of bad-sentiment inputs — and BTC/NQ still closed roughly flat on the week, no structural break. Crypto has now shrugged off several consecutive weeks of hostile macro rather than one lucky week.
Crypto Capital On-Ramp
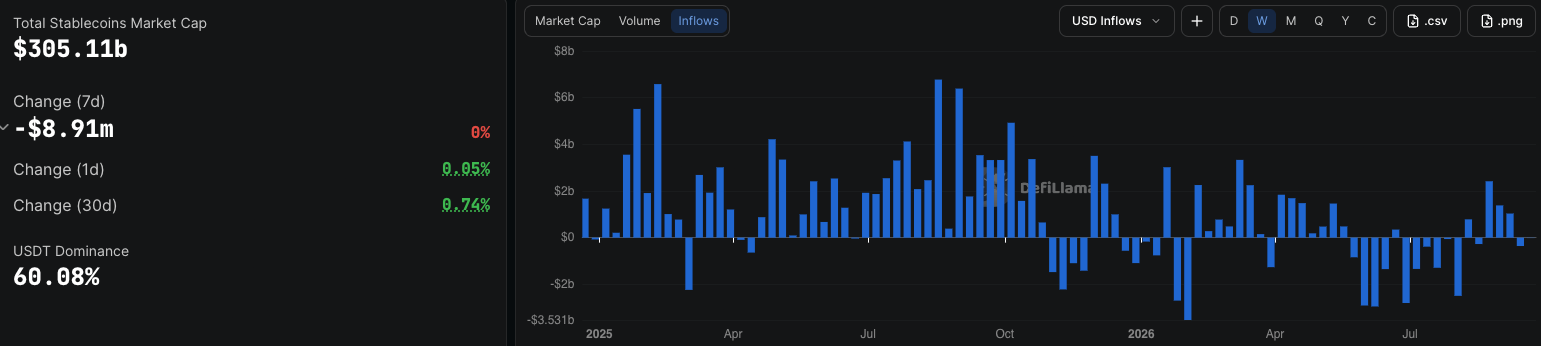
Total stablecoin supply was essentially flat, −$8.91M (~0%) — capital on the sidelines rather than moving either direction.
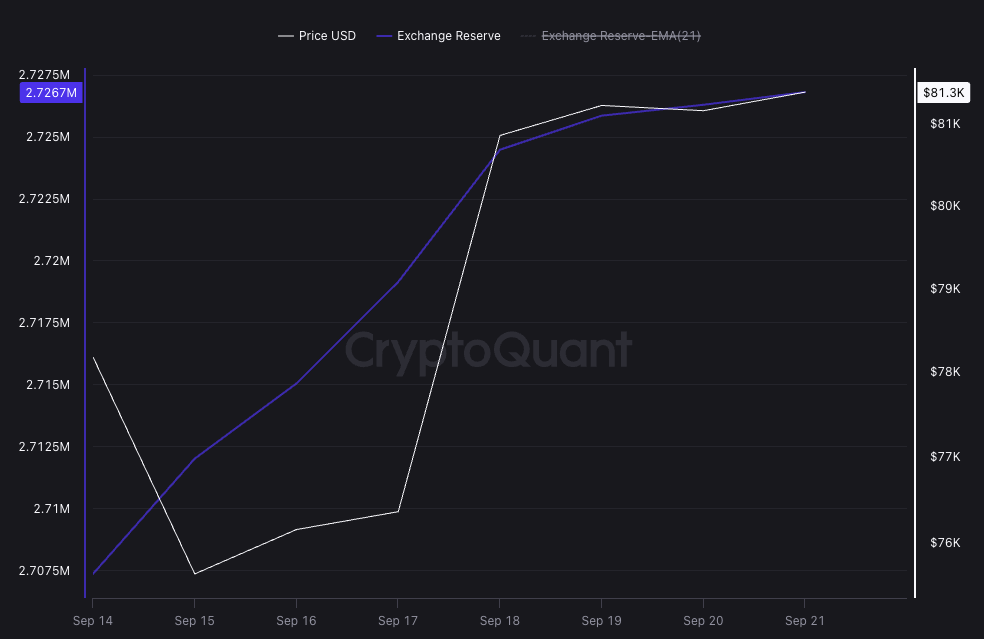
BTC and ETH diverged for the first time in a few issues. Bitcoin reserves climbed from ~2.7075M to 2.7267M in lockstep with price recovering from ~$76K to ~$81.3K — coins moving toward exchanges as the market rallied.
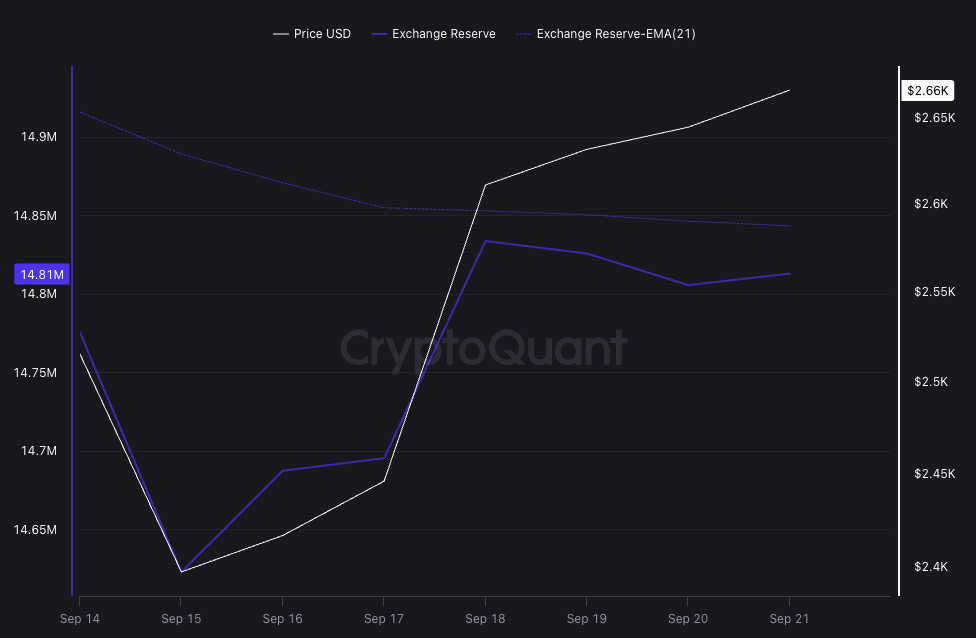
Ethereum reserves followed the same path through Sept 18, then plateaued and ticked down even as price kept climbing — holders pulling back once the rally extended, which BTC didn’t show.
ETF flows
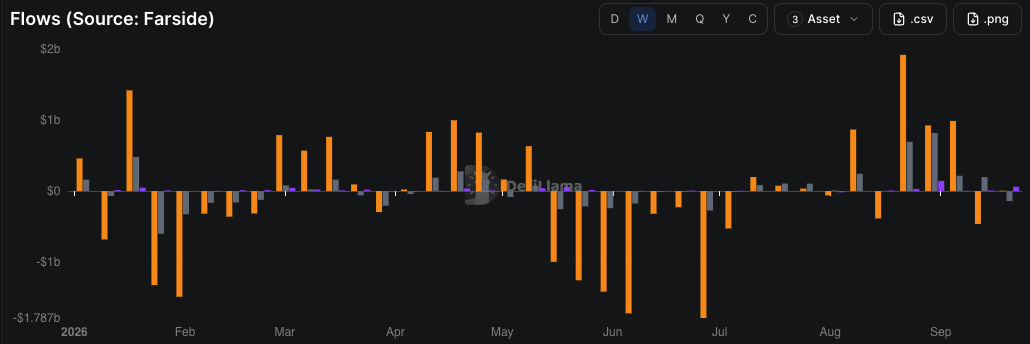
Bitcoin ETFs were roughly flat at +$6.1M for the week. Solana ETFs had a strong week at +$60.7M. But Ethereum ETFs posted −$140.9M — the first weekly outflow since July, breaking one of the most consistent bright spots of the past several issues. The regulated bid soured on ETH even as its on-chain picture stayed intact.
Week-Ahead Catalysts
Tue, Sept 22 — AVAX’s Helicon mainnet upgrade: shortens minimum validator lockup from 14 days to 48 hours, starts a 90-day taper of minimum rewards from 10% to 7.5%.
Thu, Sept 24 — INJ’s Meridian upgrade: regulated token implementations tied to SEC transfer-agent registration, unified RWA/tokenized-stock perp markets.
Fri–Tue, Sept 25–29 — Balancer’s wind-down vote: pause development, move pools to withdrawals-only, distribute ~$9M of treasury to holders who burn BAL. A major protocol voting on shutdown is rare regardless of outcome.
Sept 29 — HYPE’s largest unlock of the month (14.2M HYPE, ~$1.2–1.3B notional) — though the comparable Sept 6 tranche saw only 0.19% of float actually claimed on-chain.

Your Rate Doesn’t Move Unless You Move It
Aave and Morpho set your borrow rate by utilization — it can spike overnight. Liquity V2 lets you set your own fixed rate, with up to 91% LTV and up to 11x multiplier on ETH exposure.
<Open a position now on DeFi Saver> | Today in DeFi is supported by Liquity
This Week’s Signal: The Memecoin Money Went Into Oil and Gold
Spot DEX volume fell together on every chain that led August — Robinhood -22.5%, BSC -30.2%, Solana -7.9%, Base -8.1% — and in every case the drawdown sat in the speculative leg, not blue chips and major coins.
On Robinhood, GMGN (-57%) and Pons (-45%) led the decline. On BSC, the Binance Alpha wash-cycle deflated on schedule. Solana’s drop is the corporate-name memecoin frenzy normalizing.
Here’s the part that matters: perp volume grew on all four of those same chains — and the new pairs aren’t crypto.
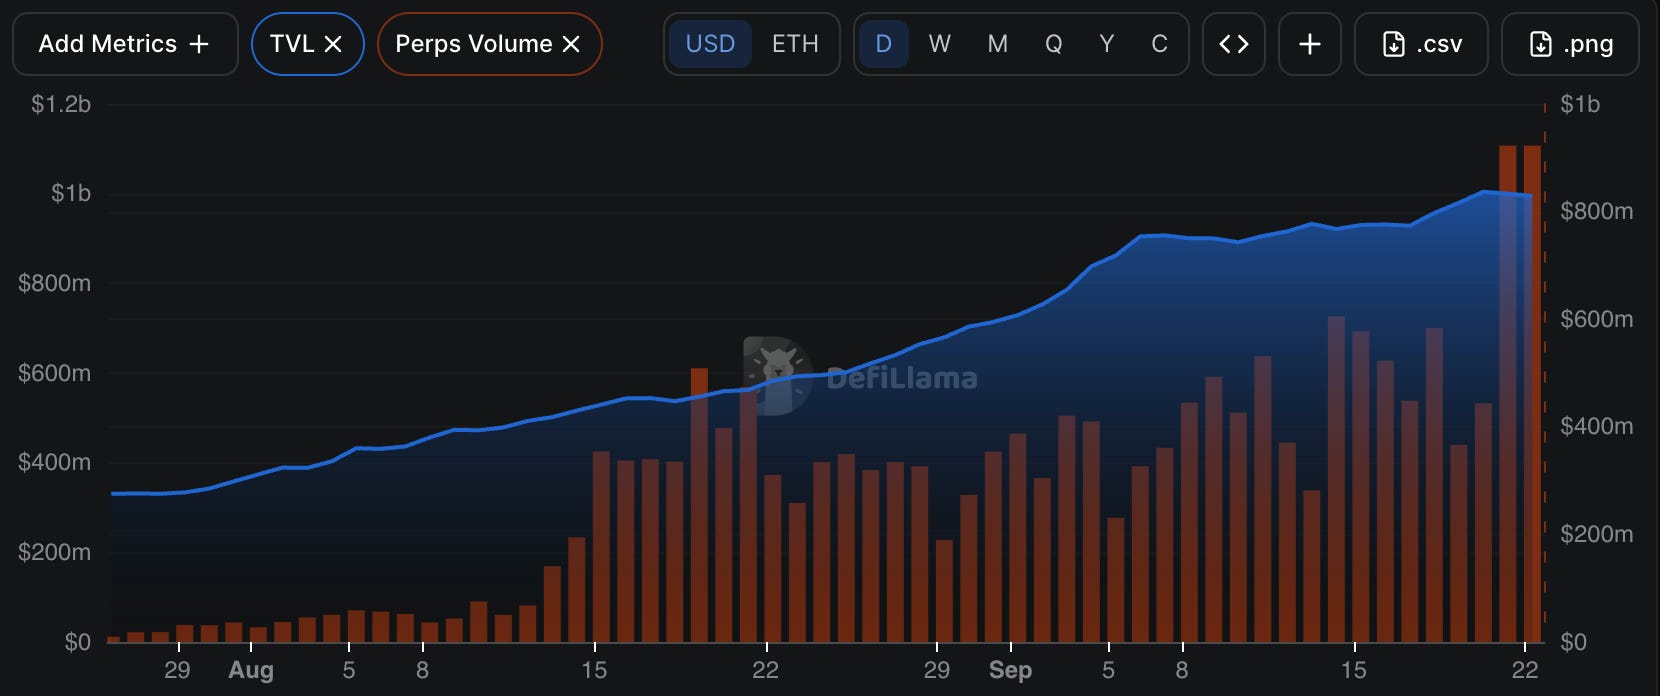
On Robinhood, Lighter did $2.95B (+17%) on a book still led by BTC and ETH, but with a distinctly TradFi tail: WTI crude, gold, a Nasdaq-100 index market, and an ANTHROPIC pre-IPO perp each printing $13–22M a day, plus a $38M ZEC market. Arcus, the dYdX-team venue built with Robinhood Crypto, grew +52% to $601M.

On Base, Avantis — freshly rebranded to Veranta — jumped +71% to $836M on zero-fee blue-chip and exotic markets (FX, commodities) plus a new “Upside Perps” product that only charges if you win. Solana’s growth came from GMTrade ($7.17B, +21%, running crypto alongside RWA markets) and Jupiter (+29%).
The read: the memecoin churn that left spot didn’t exit the system — it re-levered into perps, increasingly on equity, index, and commodity underlyings rather than tokens. Traders who were flipping corporate-name memecoins a month ago are now taking leveraged positions on crude oil and pre-IPO equity through the same venues.
Separately, three chains grew for three different reasons: Arbitrum (+33%) organically; Uniswap V3 and Pendle flow (Pendle V2 +117%) driven by ETH volatility. Polygon (+75%) almost entirely on one Uniswap V4 stable-stable pool (+422% WoW) — low-fee rotation, not retail. Ink (+46% spot, +36% perps) on its native CLOB, Nado, running 70x the chain’s spot volume.
Project & Protocol Discovery
Token Price Movers - Observations, not trade ideas.
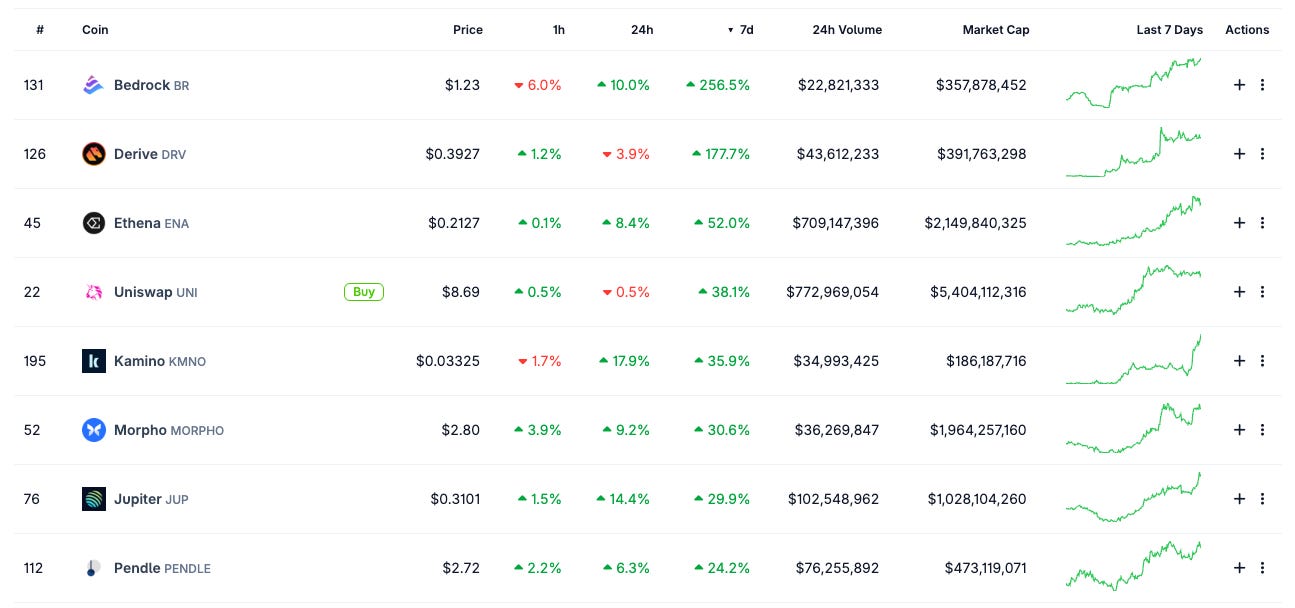
Derive (DRV), +177.7%. We flagged Derive's V3 proposal in our Sept 15 letter —with planned mainnet custody on Ethereum, expanded buybacks, plus a weekly buyback program now in its 84th consecutive week, funded by 35% of protocol fees. Volume also spiked to 2x, from $145M to $315M on a volatile market week.
Ethena (ENA), +52%. ENA’s rally coincided with continued USDe growth, a recovery in funding rates that supports higher protocol fees and revenue, and the Ethena Pay beta launch earlier this month. Recent ENA unlocks added some supply but were a smaller factor than the underlying growth and improving funding environment.
Uniswap (UNI) - Uniswap sustained the volume from Robinhood’s tokenized stocks. We previously covered UNI and its exposure to the growth of tokenized-stock activity on Robinhood Chain in our Sept. 1 analysis, as well as the Arc-confirmed deployment.